Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
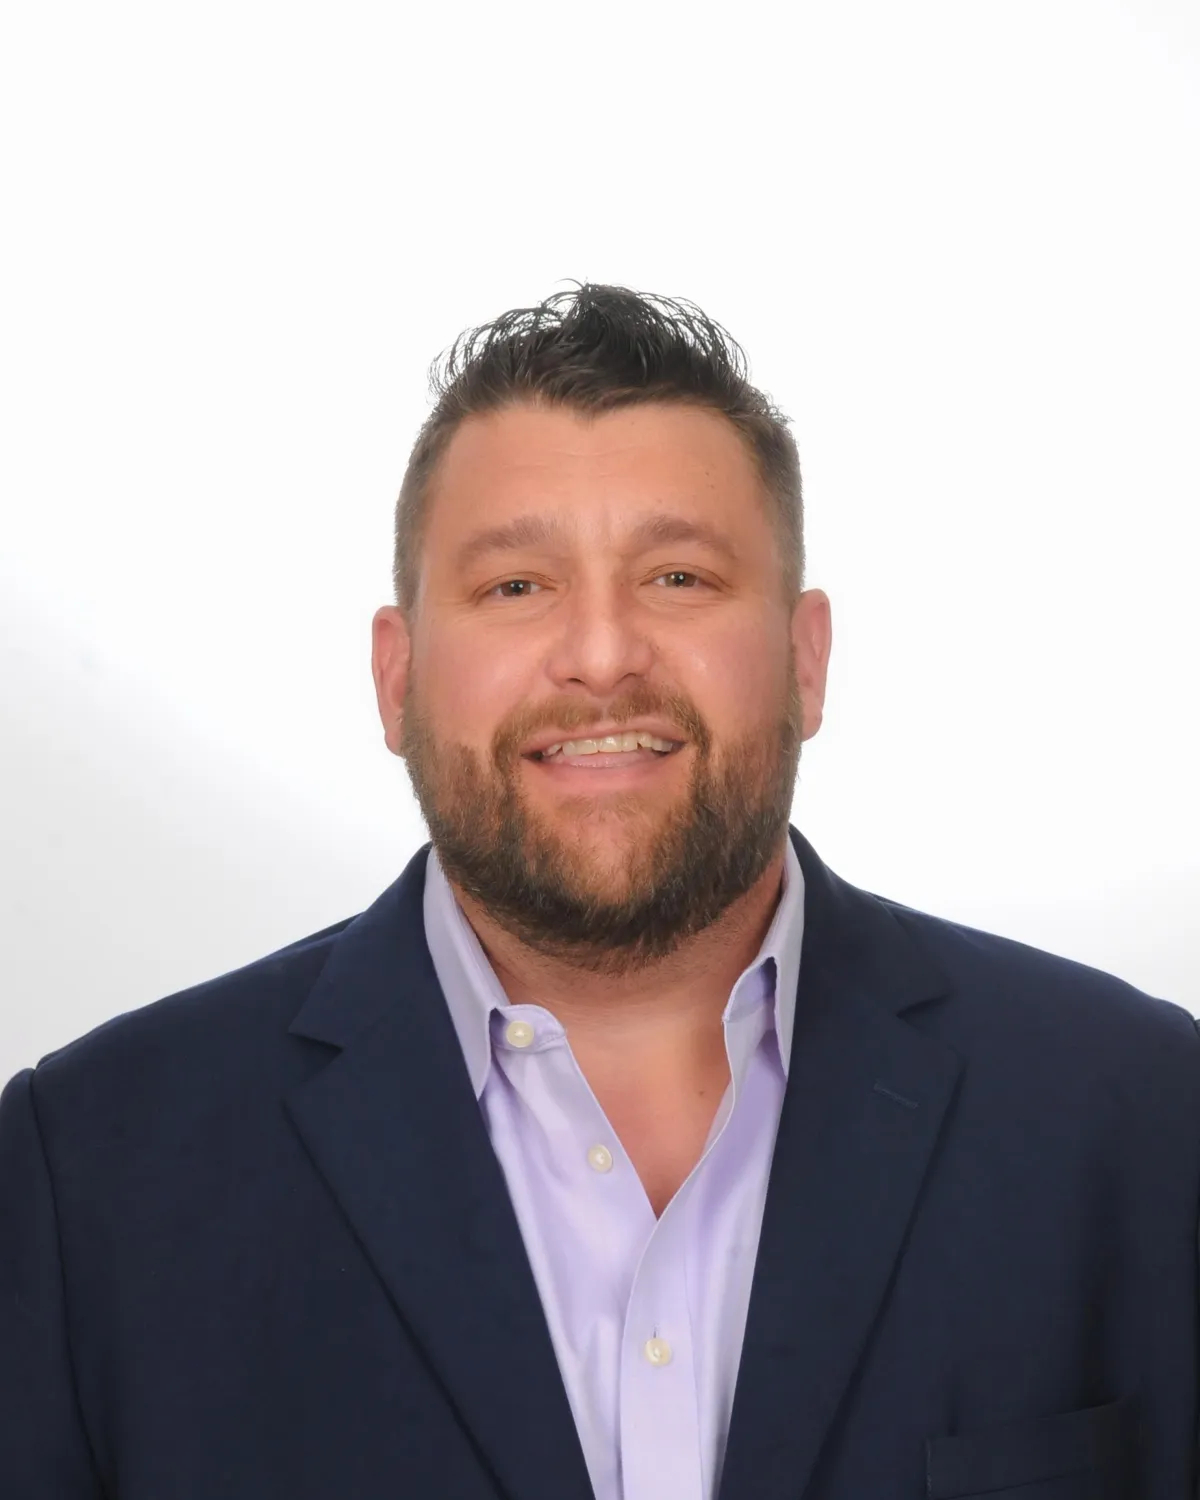
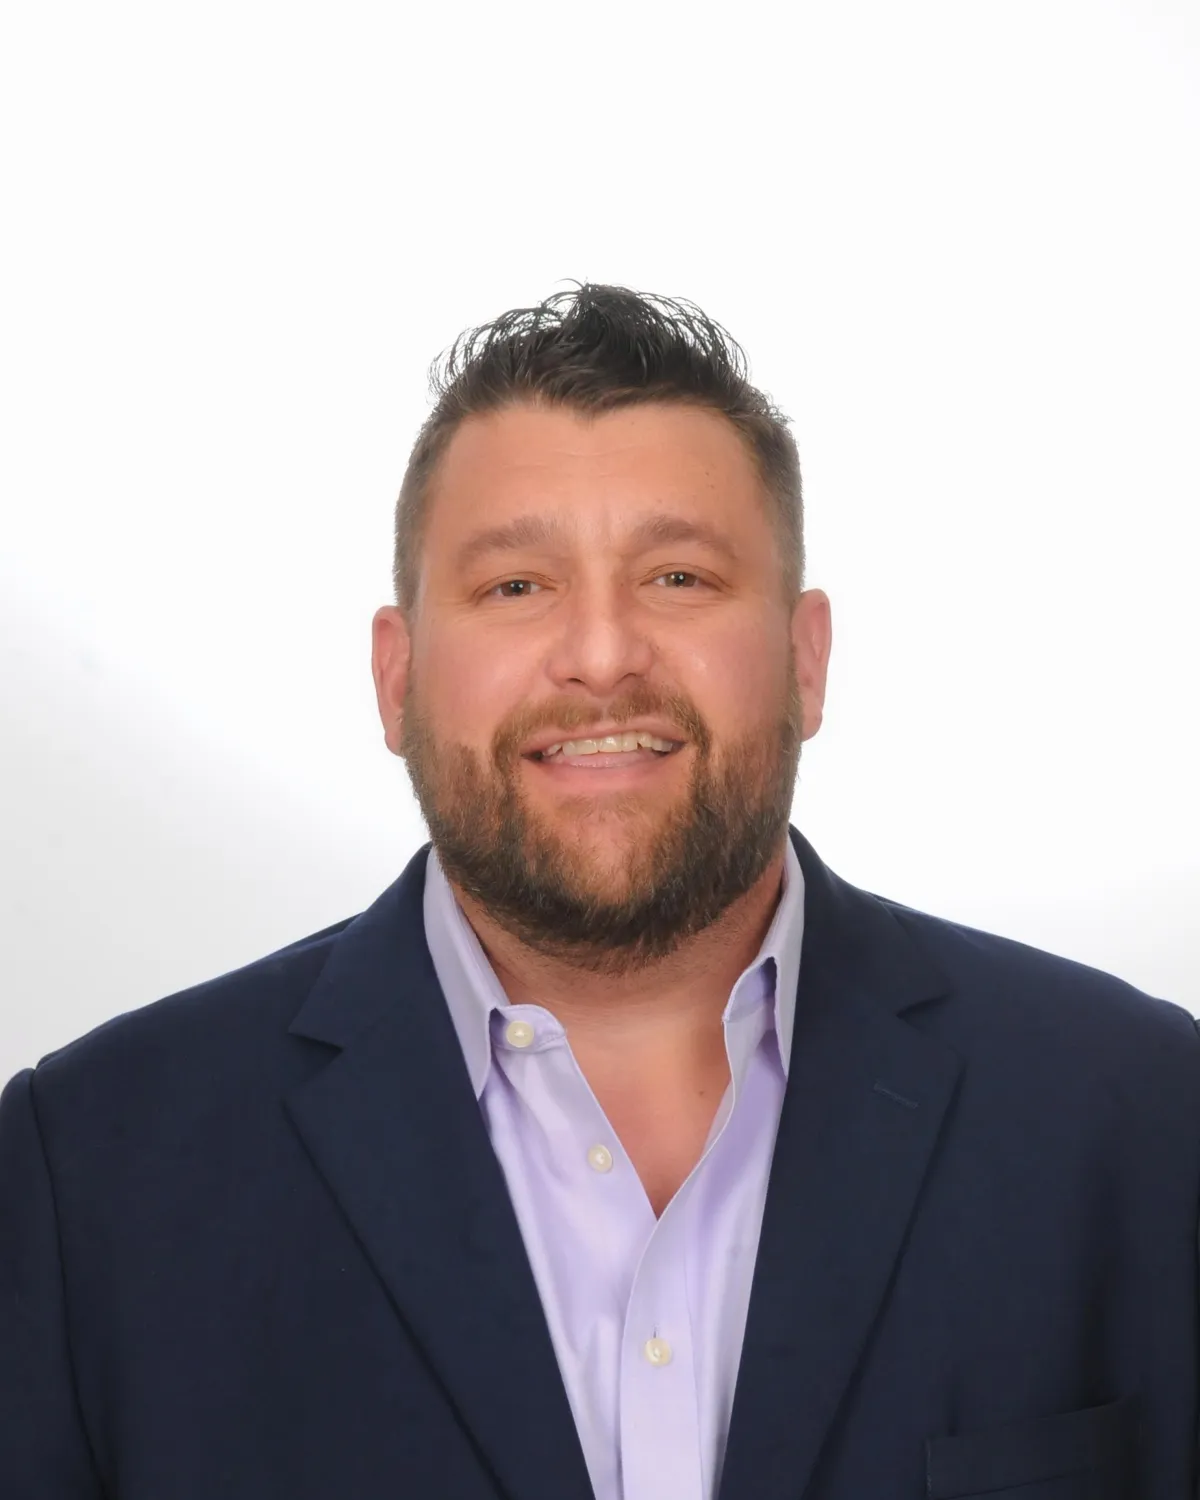
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
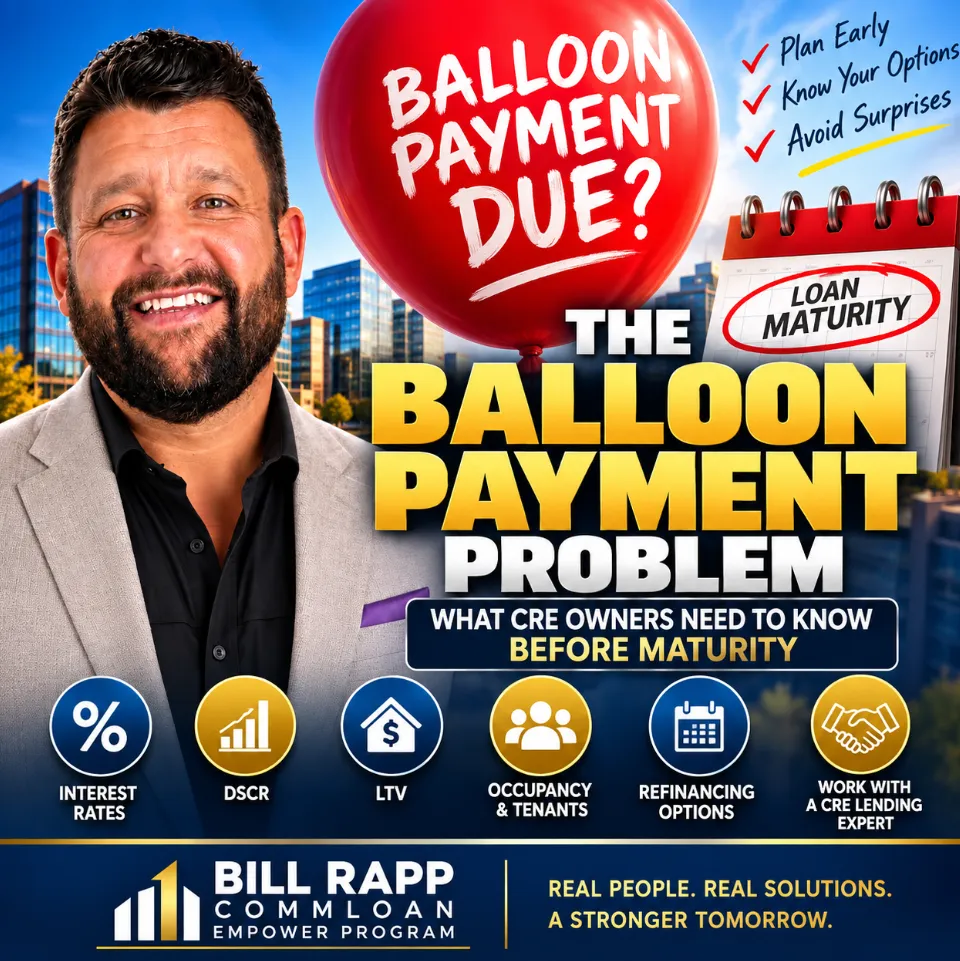
🎈 The Balloon Payment Problem: What CRE Owners Need to Know Before Loan Maturity 🏢
🎈 The Balloon Payment Problem: What CRE Owners Need to Know Before Loan Maturity 🏢
⏰ Commercial Real Estate Loan Maturity Is Coming: How to Prepare for the Balloon Payment 💰
________________________________________________________________________________
The Balloon Payment Problem: What CRE Owners Need to Know Before Maturity
A commercial real estate loan can feel manageable for years—until the maturity date suddenly becomes the most important date on your calendar.
Unlike many residential mortgages that fully amortize over 15 or 30 years, commercial real estate loans frequently have a loan term that is shorter than the amortization schedule. That means the monthly payments may be calculated using a longer amortization period, but the remaining principal balance becomes due when the loan reaches maturity.
That remaining balance is the balloon payment.
For commercial property owners, the real problem is not simply that a balloon payment exists. The problem is reaching maturity without having a viable strategy for paying it off, refinancing it, or repositioning the property.
How a Commercial Real Estate Balloon Payment Works
Consider a simplified example.
Assume an investor obtains a commercial mortgage with a 25-year amortization schedule but a 5-year loan term.
The monthly principal and interest payments are calculated as though the borrower has 25 years to repay the loan. However, the loan matures after only five years.
At maturity, the outstanding principal doesn't disappear.
It becomes due.
Most commercial property owners don't plan to write a check for the entire remaining balance. Instead, the strategy is often to refinance the property, sell it, pay down the debt with available capital, or negotiate another solution with the existing lender.
That makes the maturity date a capital-markets event—not merely another payment date.
Why Refinancing May Be Harder Than Expected
One of the biggest mistakes a CRE owner can make is assuming:
"I qualified for this loan before, so refinancing shouldn't be a problem."
The new lender is underwriting the property and borrower based on conditions that exist today, not when the original loan was made.
Several factors can change during the loan term.
1. Interest Rates
If your existing commercial mortgage was originated in a lower-rate environment, refinancing at a higher rate can significantly increase the property's annual debt service.
Higher debt service can reduce the loan amount supported by the property's cash flow.
2. DSCR
Debt Service Coverage Ratio, or DSCR, measures the relationship between a property's net operating income and its required debt payments.
A common formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose your property generates $250,000 of NOI and the proposed loan requires $200,000 of annual debt service.
Your DSCR would be:
$250,000 ÷ $200,000 = 1.25x
If higher interest rates increase the required debt service, the same property income may support a smaller loan.
That can create a refinancing gap.
3. Property Value and LTV
Loan-to-value still matters.
If your property was previously valued at $5 million but is now worth $4.5 million, a lender applying a 70% LTV limit would produce maximum proceeds of approximately:
$4.5 million × 70% = $3.15 million
But even that amount isn't guaranteed.
DSCR, debt yield, property type, tenant quality, lease rollover, borrower strength and lender guidelines may further limit proceeds.
The maximum LTV is a ceiling—not necessarily the loan amount you will receive.
4. Occupancy and Tenant Rollover
A property can be performing well today while still creating concerns for a lender.
For example, imagine a retail center that is 90% occupied.
That sounds strong.
But what happens if several major tenants have leases expiring within the next 12 to 24 months?
The lender may analyze:
·Tenant concentration
·Lease expiration schedules
·Remaining lease terms
·Historical tenant retention
·Above- or below-market rents
·Tenant credit quality
·Future capital expenditures
·Potential downtime and leasing costs
Occupancy alone doesn't tell the entire underwriting story.
The Refinancing Gap
One of the most important concepts for CRE owners approaching maturity is the refinancing gap.
Suppose your existing loan has a $3.5 million balloon balance.
After analyzing today's interest rates, NOI, DSCR, LTV and debt yield, a new lender determines that the property supports only $3.1 million.
You now have a:
$400,000 refinancing gap.
That difference generally must be addressed somehow.
Potential strategies could include bringing additional equity to closing, increasing property NOI, restructuring the financing, negotiating with the current lender, finding a lender with a different credit box, selling the property or exploring alternative capital structures.
The earlier you identify the gap, the more options you generally have to evaluate.
Don't Wait Until 30 Days Before Maturity
Commercial refinancing takes time.
Financial documents need to be collected. The property needs to be underwritten. Lenders need to evaluate the transaction. Third-party reports may be required. Appraisals, environmental reports, title work, legal review and closing documentation can all affect the timeline.
That is why CRE owners should consider evaluating their refinancing strategy well before maturity.
Depending on the transaction, beginning the analysis 6 to 12 months before maturity can provide time to understand the property's current financing position and address potential problems.
The objective isn't necessarily to refinance immediately.
It is to understand your options before the maturity date controls your decisions.
Know Your Numbers Before Approaching the Market
Before refinancing, CRE owners should understand several critical metrics:
Current NOI: What income is the property actually generating?
Current loan balance: What will the estimated payoff be at maturity?
DSCR: How much debt can the property's cash flow reasonably support?
LTV: How much leverage does the property's current value support?
Debt yield: How does the property's NOI compare with the proposed loan amount?
Occupancy and lease rollover: Are tenants stable, and when do major leases expire?
Capital expenditures: Are significant repairs or improvements coming?
These numbers help determine whether refinancing is straightforward or whether a different strategy may be necessary.
One Bank's Answer Isn't the Entire Capital Market
Commercial real estate financing isn't a single-product marketplace.
Banks, credit unions, agency lenders, CMBS lenders, bridge lenders, debt funds and other capital sources can evaluate transactions differently.
One lender may focus heavily on sponsor liquidity.
Another may have a conservative LTV requirement.
Another may be uncomfortable with the property type.
Another may have geographic restrictions.
And another may simply have reached an internal concentration limit for that asset class.
That is why a "no" from one lender doesn't necessarily mean a transaction is unfinanceable.
It means you need to understand why the lender declined or reduced the requested proceeds and determine whether another capital source better matches the transaction.
Your Maturity Date Shouldn't Be a Surprise
The best time to discover a refinancing problem is not two weeks before your balloon payment is due.
Commercial property owners should treat loan maturity as part of their long-term asset management strategy.
Know the maturity date.
Monitor the property's NOI.
Understand the lease rollover schedule.
Watch your leverage.
Evaluate DSCR.
Estimate your potential refinance proceeds.
Then compare those proceeds with your projected balloon balance.
If there is a gap, you want time to develop a strategy.
Start With the Deal, Not the Loan Product
At the Bill Rapp – CommLoan Empower Program, the objective is not simply to find a loan product.
It is to understand the transaction first.
What is the property worth?
What does the cash flow support?
What is the existing debt?
What is the borrower's objective?
How much leverage makes sense?
And what type of capital source is appropriate for that particular transaction?
If you own commercial real estate with a loan approaching maturity, don't wait until the balloon payment is staring you in the face.
Start evaluating the capital structure early.
Bill Rapp – CommLoan Empower Program
Commercial Real Estate Financing | Capital Advisory
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok