Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
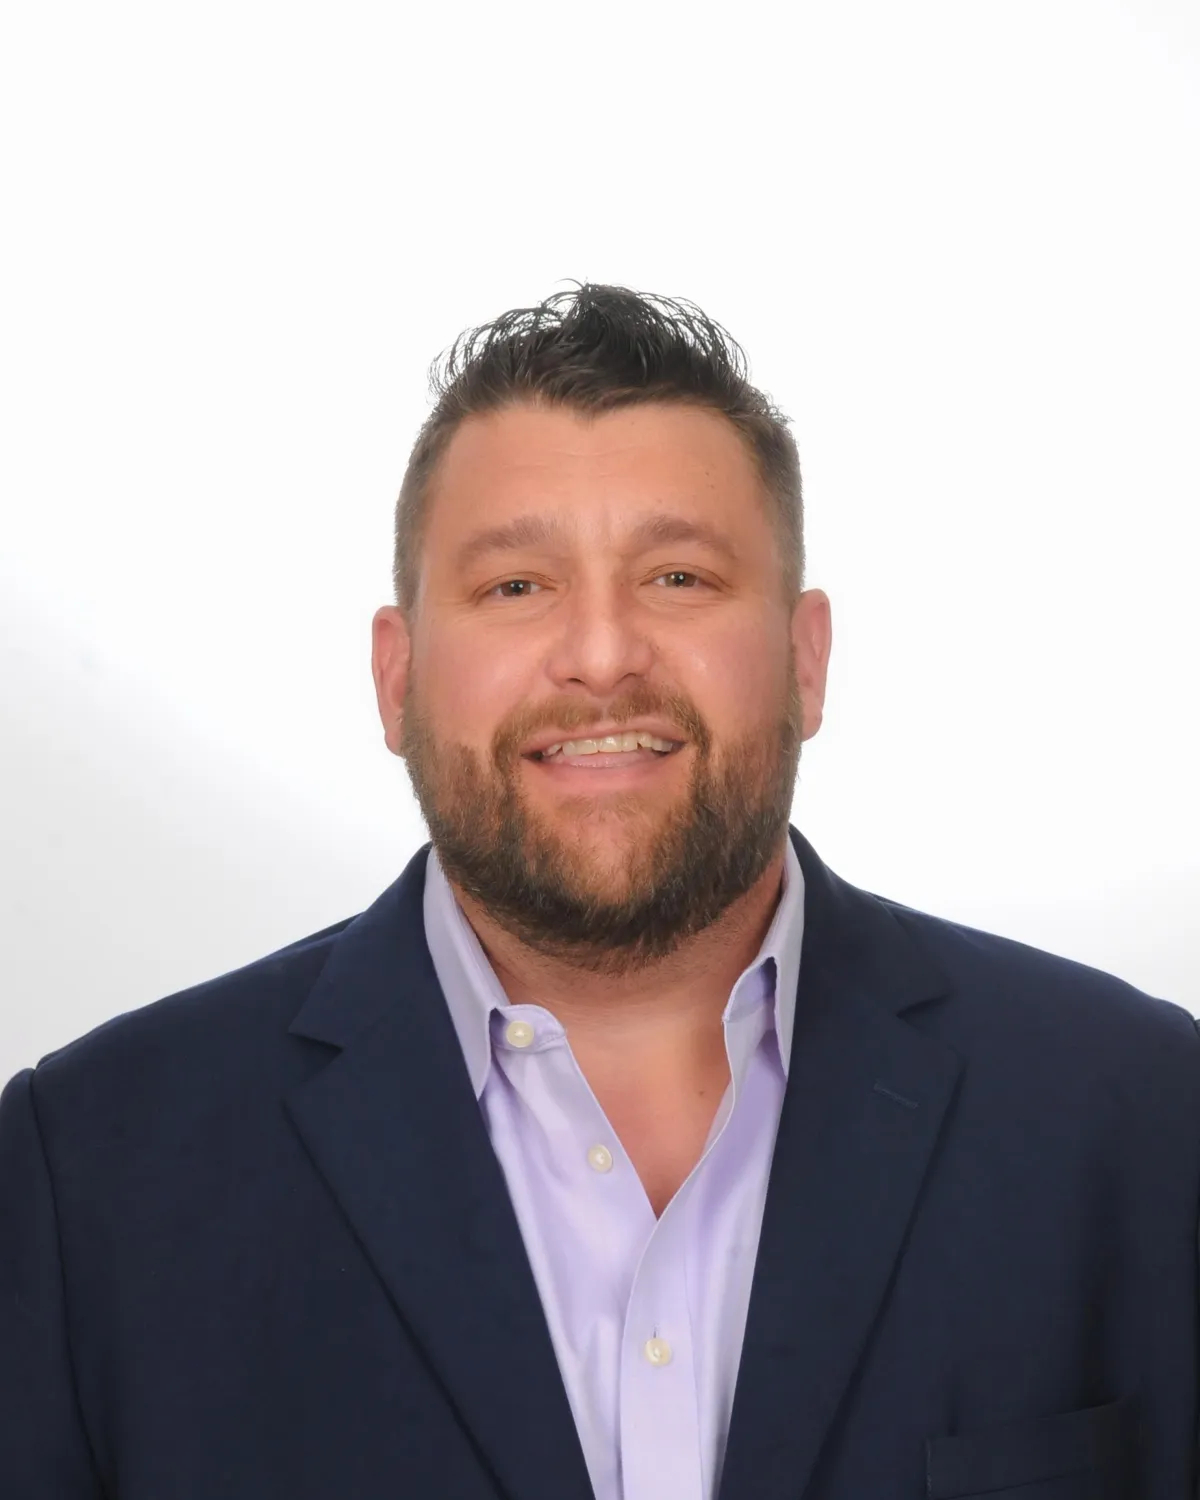
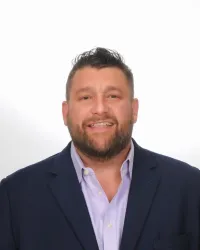
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 Commercial Real Estate Loans: The Complete Borrower’s Guide to CRE Financing 💰
🏢 Commercial Real Estate Loans: The Complete Borrower’s Guide to CRE Financing 💰
💵 How Commercial Real Estate Loans Work: Financing Options, DSCR, LTV & More 🏦
Commercial Real Estate Loans: The Complete Borrower’s Guide
Financing commercial real estate is very different from getting a residential mortgage.
Whether you're buying an office building, retail center, industrial property, multifamily asset, or property for your own business, the lender will typically evaluate both you as the borrower and the economics of the property.
And while interest rate matters, it is only one component of a commercial real estate loan.
Loan proceeds, amortization, term, recourse, prepayment structure, cash requirements, Debt Service Coverage Ratio (DSCR), Loan-to-Value (LTV), and lender underwriting standards can have just as much impact on whether a financing structure works.
This guide explains the fundamentals commercial real estate investors and business owners should understand before approaching the capital markets.
What Is a Commercial Real Estate Loan?
A commercial real estate loan, or CRE loan, is financing secured by real estate used primarily for business or investment purposes.
Common property types include:
·Office buildings
·Retail centers
·Industrial and warehouse properties
·Multifamily properties
·Medical and dental offices
·Mixed-use properties
·Hotels and hospitality properties
·Self-storage facilities
·Owner-occupied commercial buildings
·Certain special-purpose properties
Commercial loans may be used for acquisitions, refinances, construction, renovations, business expansion, or repositioning an existing property.
The appropriate financing structure depends heavily on the property, borrower, business plan and source of repayment.
How Commercial Real Estate Loans Differ From Residential Mortgages
Residential mortgages tend to be standardized. Commercial real estate lending is considerably more customized.
A commercial lender may analyze:
Property cash flow: How much Net Operating Income does the property produce?
Borrower financial strength: What are the borrower's liquidity, net worth, credit history and contingent liabilities?
Property value: How much is the collateral worth relative to the requested loan?
Debt service: Does the property or business generate enough cash flow to comfortably make the loan payments?
Experience: Does the borrower have experience owning or operating this type of property?
Business plan: Is this a stabilized acquisition, value-add investment, construction project or transitional asset?
Two borrowers purchasing seemingly similar buildings can therefore receive very different financing proposals.
Understanding Loan-to-Value — LTV
Loan-to-Value compares the loan amount with the property's value.
The formula is:
LTV = Loan Amount ÷ Property Value
For example, assume a property is valued at $2,000,000 and the proposed loan is $1,400,000.
The LTV would be:
$1,400,000 ÷ $2,000,000 = 70% LTV
That leaves approximately $600,000 of borrower equity before considering closing costs and other transaction expenses.
But an important distinction exists:
Maximum LTV does not necessarily equal maximum loan proceeds.
Cash flow constraints can result in a lender offering less than its stated maximum LTV.
Understanding Debt Service Coverage Ratio — DSCR
DSCR measures the property's ability to cover its debt payments.
The basic calculation is:
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose a property generates $150,000 in annual NOI and annual principal and interest payments total $120,000.
The DSCR is:
$150,000 ÷ $120,000 = 1.25x
That means the property generates $1.25 of NOI for every $1.00 of annual debt service.
Higher DSCR generally means a greater cash-flow cushion.
This is why a strong appraisal does not automatically produce a larger commercial real estate loan. A property can support the requested loan from an LTV standpoint but fail to support it from a DSCR standpoint.
Don't Forget Debt Yield
Debt yield is another important underwriting metric, particularly in commercial real estate lending.
The calculation is:
Debt Yield = NOI ÷ Loan Amount
For example:
·NOI: $150,000
·Loan: $1,500,000
·Debt Yield: 10%
Unlike DSCR, debt yield is not directly affected by the interest rate or amortization period.
It gives the lender another way to evaluate the risk associated with its loan basis.
Major Types of Commercial Real Estate Loans
There isn't one universal "commercial mortgage."
Borrowers may encounter several financing categories.
Bank and Credit Union Loans
Banks and credit unions remain major sources of commercial real estate financing.
These loans can work particularly well for stabilized properties and borrowers with strong financial profiles and banking relationships.
Depending on the institution and transaction, loans may include personal guarantees, financial covenants and periodic reporting requirements.
SBA 7(a) Loans
SBA 7(a) financing can be particularly useful for eligible businesses acquiring owner-occupied commercial real estate.
Financing may potentially incorporate real estate alongside other eligible business needs, depending on the transaction and applicable SBA requirements.
SBA 504 Loans
SBA 504 financing is designed primarily for eligible fixed assets, including owner-occupied commercial real estate and certain equipment.
For qualifying business owners, it can provide an attractive alternative to conventional commercial financing.
Agency Multifamily Loans
Larger stabilized multifamily properties may qualify for financing through agency programs.
These loans can offer attractive structures but involve specific underwriting standards concerning occupancy, property condition, operating history and borrower qualifications.
Bridge Loans
A commercial bridge loan is short-term financing generally used when a property or transaction does not yet qualify for permanent financing.
Common scenarios include:
·Lease-up
·Renovations
·Repositioning
·Time-sensitive acquisitions
·Properties requiring stabilization
The critical question with bridge financing isn't simply how you get into the loan.
It's how you get out.
Borrowers should stress-test the refinance or sale strategy before closing.
Construction Loans
Commercial construction financing can fund ground-up development and major redevelopment projects.
Lenders generally examine land basis, total development cost, borrower equity, experience, construction budget, contingencies, leasing assumptions and the eventual exit strategy.
Owner-Occupied vs. Investment Commercial Real Estate
This distinction can significantly affect financing.
An owner-occupied property is primarily used by the borrower's operating business.
An investment property generates income primarily through third-party tenants.
The lender's analysis may therefore differ.
For an investment property, emphasis may be placed on:
·Rent roll
·Tenant credit
·Lease expirations
·Occupancy
·NOI
·DSCR
·Market rents
For an owner-user transaction, lenders may also place significant emphasis on:
·Business cash flow
·Historical financial performance
·Global debt service
·Guarantor strength
·Industry outlook
How Much Down Payment Do You Need?
There isn't a universal down payment requirement for commercial real estate.
Equity requirements depend on factors including:
·Property type
·Occupancy
·Borrower strength
·Loan program
·Cash flow
·Location
·Tenant concentration
·Property condition
·Business plan
·Lender risk tolerance
A lender advertising a particular maximum LTV doesn't necessarily mean every transaction qualifies for that leverage.
Again, the actual loan may be constrained by LTV, DSCR, debt yield or another underwriting requirement.
What Documents Should Borrowers Expect to Provide?
Requirements vary, but preparing a comprehensive package early can significantly improve the financing process.
Documents frequently requested include:
·Personal Financial Statement
·Schedule of Real Estate Owned
·Tax returns
·Bank or brokerage statements
·Entity documents
·Purchase contract
·Rent roll
·Historical operating statements
·Current year-to-date operating statement
·Existing loan information
·Property information
·Borrower résumé or ownership experience
Owner-occupied transactions may also require business tax returns, balance sheets, profit-and-loss statements and other operating-company information.
Complete documentation allows lenders to evaluate a transaction more efficiently.
Why the Lowest Commercial Mortgage Rate Isn't Always the Best Loan
Borrowers naturally focus on interest rates.
But consider two hypothetical proposals.
Loan A offers the lower rate but provides substantially less proceeds and includes restrictive prepayment terms.
Loan B carries a slightly higher rate but provides the proceeds necessary to execute the investment strategy, offers a longer term and has a more suitable prepayment structure.
Which is better?
That depends on the borrower's objectives.
A commercial loan should generally be evaluated across at least five dimensions:
Rate. Proceeds. Term. Recourse. Prepayment.
The lowest interest rate doesn't automatically create the best economic outcome.
Fixed vs. Floating Interest Rates
Commercial borrowers may also have a choice between fixed- and floating-rate financing.
A fixed-rate loan provides greater payment predictability.
A floating-rate loan changes according to its underlying benchmark and loan spread.
Floating-rate financing can make sense for certain transitional strategies, but borrowers should understand how higher rates could affect:
·Monthly payments
·DSCR
·Cash flow
·Refinance proceeds
·Investment returns
Interest-rate caps or other hedging requirements may also apply to some floating-rate structures.
Recourse vs. Non-Recourse Commercial Loans
With recourse financing, the borrower or guarantor may have personal liability for repayment subject to the loan documents.
With non-recourse financing, the lender's recovery is generally focused on the collateral, although non-recourse loans commonly contain carve-outs for specified acts.
Non-recourse financing can be attractive, but borrowers should evaluate the entire structure rather than assuming non-recourse is automatically superior.
Commercial Loan Prepayment Penalties
Prepayment structure is particularly important if you expect to sell or refinance before maturity.
Commercial loans may include mechanisms such as:
·Step-down prepayment penalties
·Yield maintenance
·Defeasance
·Lockout periods
·Other negotiated structures
A loan offering a very attractive rate can become expensive if its prepayment structure conflicts with your anticipated holding period.
What Commercial Real Estate Lenders Look For
Strong transactions generally tell a coherent story.
The lender wants to understand:
Who is borrowing the money?
What property secures the loan?
How will the loan be repaid?
What can go wrong?
How much borrower equity is at risk?
What is the exit strategy?
Borrowers who address these questions proactively can make a transaction easier for lenders to evaluate.
The Importance of Matching the Deal to the Right Capital Source
One of the biggest challenges in commercial real estate financing is that lenders have different credit boxes.
A transaction that doesn't fit one lender may potentially fit another.
The objective shouldn't simply be:
"Can this lender make the loan?"
A better question is:
"Which capital source and financing structure best fit this transaction?"
That shift turns commercial mortgage shopping into a capital strategy.
Before Applying for a Commercial Real Estate Loan
Know these numbers before approaching lenders:
1.Purchase price or current property value
2.Requested loan amount
3.Current NOI
4.Projected NOI, when applicable
5.Occupancy
6.Requested term
7.Desired amortization
8.Borrower liquidity
9.Borrower net worth
10.Exit strategy
The more clearly these elements are defined, the easier it becomes to evaluate potential financing structures.
Final Thoughts
Commercial real estate financing isn't simply about finding the lowest advertised rate.
It's about finding the right capital structure for the property, borrower and investment strategy.
Understand the interaction between LTV, DSCR, debt yield, proceeds, term, amortization, recourse and prepayment before selecting a loan.
Whether you're purchasing, refinancing, developing or repositioning commercial real estate, evaluate the financing as carefully as you evaluate the property itself.
Explore Commercial Real Estate Financing with Bill Rapp
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok