Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
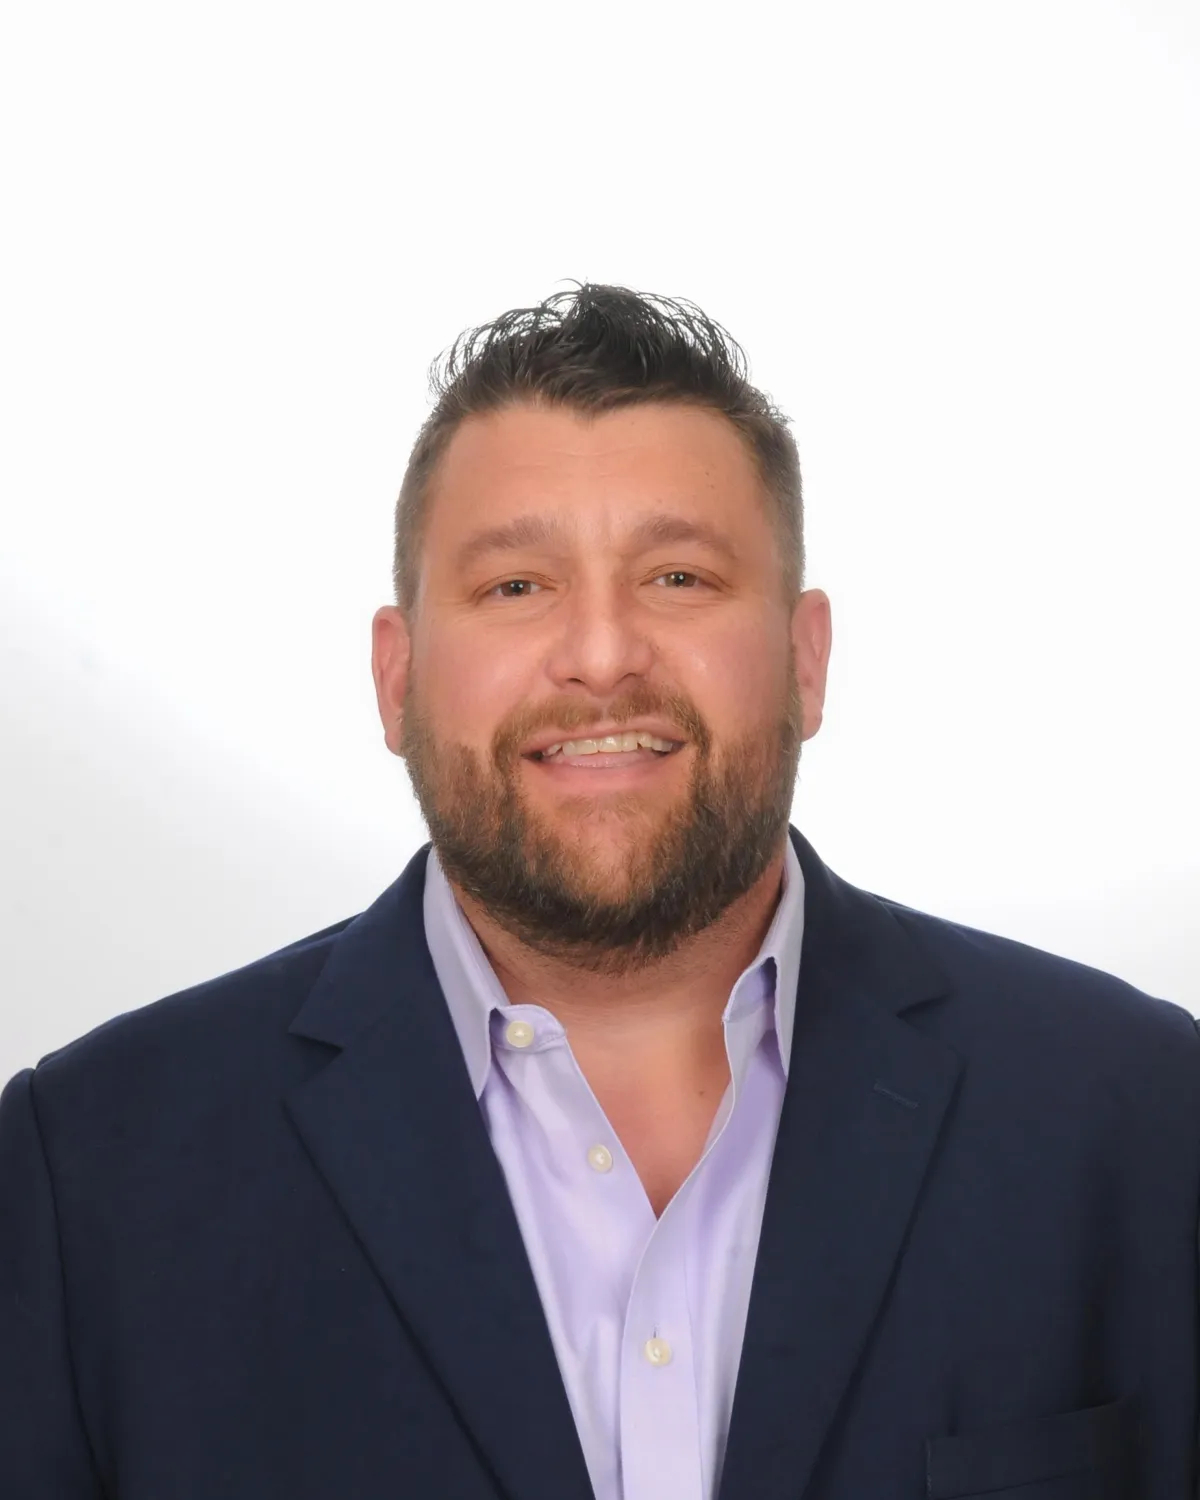
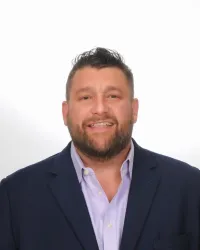
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 Multifamily Loans: The Complete Investor’s Guide to Apartment Financing 💰
🏢 Multifamily Loans: The Complete Investor’s Guide to Apartment Financing 💰
💵 How to Finance an Apartment Building: Multifamily Loans, DSCR, LTV & Investor Strategies 🏘️
Multifamily Loans: Complete Investor’s Guide
Multifamily real estate can be an attractive way to build a commercial property portfolio, but buying the right apartment property is only half the equation.
The other half is structuring the financing correctly.
A multifamily loan is not simply a larger version of a residential mortgage. Commercial multifamily lenders evaluate the property's income, expenses, occupancy, market, physical condition and ability to support the proposed debt. They also evaluate the sponsor's experience, liquidity, net worth and business plan.
For investors, understanding how multifamily loans, DSCR, LTV, debt yield, occupancy and lender requirements work can make the difference between a transaction that closes and one that falls apart during underwriting.
This guide covers the major concepts investors should understand before financing an apartment building.
What Is a Multifamily Loan?
In commercial real estate finance, multifamily generally means an apartment property containing five or more residential units. Fannie Mae's conventional multifamily program, for example, applies to existing stabilized properties with at least five units. Fannie Mae
Properties with one to four residential units generally fall into the residential mortgage world, while properties with five or more units are typically evaluated as commercial multifamily investments.
That distinction changes the underwriting process substantially.
Instead of focusing primarily on the borrower's personal income, a commercial multifamily lender pays significant attention to the property's ability to generate sustainable Net Operating Income (NOI).
The Major Types of Multifamily Financing
There is no single "multifamily loan." Investors may have several potential capital sources depending on the property and transaction.
1. Bank and Credit Union Loans
Banks and credit unions remain important multifamily lenders, particularly for smaller and middle-market apartment properties.
Their underwriting can vary considerably from institution to institution.
A local or regional bank may offer competitive pricing and flexibility, particularly when the borrower has an established banking relationship. However, loans may include personal guarantees, shorter maturities or balloon payments.
2. Fannie Mae Multifamily Loans
Fannie Mae provides financing through approved Delegated Underwriting and Servicing lenders.
Its current conventional multifamily term sheet lists:
·Terms of 5–30 years
·Amortization up to 30 years
·Fixed- and variable-rate options
·Maximum 80% LTV
·Minimum 1.25x DSCR
·Non-recourse execution available for most loans over $750,000
Fannie Mae generally expects conventional properties to have stabilized occupancy, typically around 90%, for 90 days before funding, although some pre-stabilized situations may be considered separately. Fannie Mae
Its Small Mortgage Loan Program currently provides streamlined financing of up to $9 million nationwide for qualifying properties. Fannie Mae
These are program parameters—not a promise that every qualifying property will receive maximum leverage.
3. Freddie Mac Multifamily Loans
Freddie Mac is another major source of multifamily capital.
Freddie Mac's published underwriting guidance shows that conventional fixed-rate loans generally have maximum LTVs of 80% and minimum DSCR requirements of 1.25x, although specific executions and exceptions can differ. Freddie Mac Multifamily
Both Fannie Mae and Freddie Mac can be important options for stabilized apartment properties.
4. FHA/HUD Multifamily Financing
HUD-insured financing can provide another option for qualifying apartment projects.
For example, FHA Section 223(f) provides mortgage insurance for the purchase or refinancing of existing multifamily rental housing that does not require substantial rehabilitation. HUD defines eligible multifamily properties under this program as containing at least five residential units with complete kitchens and baths. HUD
HUD financing can be attractive for certain long-term investment strategies, although investors should account for the additional documentation, requirements and transaction timeline associated with the execution.
5. Bridge Loans
What happens when an apartment property isn't stabilized?
That is where multifamily bridge financing may enter the capital stack.
Bridge loans are commonly considered for situations involving:
·Low occupancy
·Heavy renovations
·Lease-up
·Deferred maintenance
·Value-add acquisitions
·Repositioning
·Significant operational changes
Instead of underwriting only today's performance, a bridge lender may also evaluate the property's future stabilized NOI and the borrower's business plan.
The trade-off is generally a higher cost of capital and shorter loan duration than permanent financing.
The investor therefore needs a credible exit strategy.
6. Private and Debt-Fund Financing
Private lenders and debt funds can provide capital for transactions that don't fit traditional bank or agency credit boxes.
These lenders may offer greater flexibility regarding property condition, stabilization, leverage or borrower circumstances, but that flexibility can come with higher interest rates, fees or other structural requirements.
The Four Numbers Multifamily Investors Need to Understand
Investors frequently begin their financing search by asking:
"What's the interest rate?"
That matters, but it isn't the only question.
Four metrics can have a major influence on multifamily financing.
1. Net Operating Income — NOI
NOI measures the property's income after operating expenses but before debt service and certain other items.
A simplified formula is:
Effective Gross Income − Operating Expenses = NOI
For example, assume an apartment property generates $600,000 in effective annual income and has $250,000 in operating expenses.
The NOI would be:
$600,000 − $250,000 = $350,000
That $350,000 becomes one of the central numbers in the lender's underwriting.
2. Debt Service Coverage Ratio — DSCR
DSCR measures how comfortably property income supports debt payments.
DSCR = NOI ÷ Annual Debt Service
Suppose NOI is $350,000 and annual debt service is $280,000.
$350,000 ÷ $280,000 = 1.25x DSCR
A 1.25x DSCR means the property generates $1.25 of NOI for every $1.00 of debt service.
That explains why interest rates matter beyond simply determining the borrower's monthly payment.
If rates increase, debt service increases.
If debt service increases while NOI remains unchanged, DSCR falls.
And when DSCR becomes the binding underwriting constraint, the lender may reduce the available loan proceeds.
3. Loan-to-Value — LTV
LTV compares the loan amount with the property's value.
LTV = Loan Amount ÷ Property Value
For example:
Property value: $5,000,000
Proposed loan: $3,500,000
LTV:
$3.5 million ÷ $5 million = 70%
But an important point is often overlooked:
The lender's maximum LTV does not necessarily equal the amount you can borrow.
A loan program may allow 75% or 80% LTV, but DSCR or another underwriting constraint could produce a smaller loan.
4. Debt Yield
Debt yield compares NOI with the loan amount.
Debt Yield = NOI ÷ Loan Amount
Using our previous example:
NOI: $350,000
Loan: $3,500,000
Debt yield:
$350,000 ÷ $3,500,000 = 10%
Unlike DSCR, debt yield is not directly dependent on the interest rate or amortization period.
This makes it another useful way for lenders to evaluate leverage and property cash flow.
Why Occupancy Matters
Occupancy can dramatically change the financing options available to a multifamily investor.
A stabilized apartment complex with consistent collections and a strong operating history may qualify for permanent financing.
A 60%-occupied property undergoing renovations presents a completely different credit profile.
That does not necessarily make the property a bad investment.
It may simply require a different financing strategy.
One possible capital plan might look like:
Acquire → Renovate → Lease Up → Stabilize → Refinance
For qualifying larger properties approaching stabilization, Fannie Mae even maintains a near-stabilization execution; its current term sheet calls for at least 75% physical occupancy at rate lock, among other requirements. Fannie Mae
The important point is to match the loan structure to the property's current stage of the business plan.
How Multifamily Lenders Underwrite a Deal
Although every lender has its own credit box, underwriting commonly considers both the property and the sponsorship.
Property Analysis
Expect lenders to evaluate items such as:
·Current rent roll
·Historical operating statements
·T-12 financials
·Occupancy
·Collections
·Market rents
·Operating expenses
·Real estate taxes
·Insurance
·Repairs and maintenance
·Capital expenditures
·Deferred maintenance
·Property condition
·Market fundamentals
Sponsor Analysis
Lenders may also evaluate:
·Credit
·Net worth
·Post-closing liquidity
·Multifamily ownership experience
·Property management experience
·Real estate owned
·Contingent liabilities
·Global cash flow
·Ownership structure
Strong property economics are important, but sponsorship still matters.
Recourse vs. Non-Recourse Multifamily Loans
Another major consideration is recourse.
With a recourse loan, the lender may have claims against the guarantor beyond the collateral, subject to the loan documents.
A non-recourse loan generally limits the lender primarily to the property collateral, although standard carve-outs for specified "bad acts," such as fraud, can still create liability.
For example, Fannie Mae currently states that non-recourse execution is available for most conventional multifamily loans greater than $750,000, with standard carve-outs. Fannie Mae
Investors should evaluate recourse alongside rate, proceeds, amortization and prepayment—not as an afterthought.
Don't Ignore Prepayment Structure
One of the most overlooked parts of multifamily financing is the prepayment provision.
Depending on the loan, an investor may encounter structures such as:
·Yield maintenance
·Declining prepayment premiums
·Lockout periods
·Other negotiated prepayment provisions
Fannie Mae, for example, identifies yield maintenance for fixed-rate conventional loans and declining prepayment premiums for variable-rate loans among its options. Fannie Mae
This matters if your strategy involves selling or refinancing before maturity.
A loan with a slightly lower interest rate isn't automatically better if its prepayment structure conflicts with your investment strategy.
How Much Cash Do You Need?
Your equity requirement is not simply:
Purchase Price − Loan Amount.
Investors should also budget for items such as closing costs, lender fees, third-party reports, reserves, renovation costs, operating shortfalls and working capital.
That means a property financed at 75% LTV does not automatically mean your total cash requirement is exactly 25%.
This is particularly important on value-add apartment acquisitions.
Documents to Prepare Before Seeking Multifamily Financing
A well-organized financing package can make the lender review substantially easier.
Depending on the transaction, be prepared to provide:
·Rent roll
·T-12 operating statement
·Historical P&Ls
·Purchase contract
·Offering memorandum
·Capital expenditure budget
·Sources and uses
·Schedule of real estate owned
·Personal financial statements
·Entity documents
·Borrower and guarantor information
·Renovation scope
·Property management information
·Sponsor resume
·Current debt information for refinances
For agency financing, standard third-party reports can include an appraisal, Phase I Environmental Site Assessment and Property Condition Assessment. Fannie Mae
Why Comparing Multifamily Lenders Matters
Commercial lending is fragmented.
One lender may like the property type but dislike the market.
Another may like the market but require lower leverage.
A third may provide higher proceeds but require recourse.
Another may offer non-recourse financing but impose a prepayment structure that doesn't match your planned exit.
Therefore, investors should compare more than interest rates.
Compare:
Loan proceeds + rate + amortization + term + recourse + prepayment + reserves + fees + execution certainty.
The objective isn't simply to find a loan.
It's to find a capital structure aligned with the investment.
The Bottom Line
Multifamily financing becomes much easier to understand once investors stop thinking about the loan as a single interest rate.
Start with the property.
What is the NOI?
What is the current occupancy?
What does the rent roll look like?
Is the property stabilized or value-add?
What leverage can the cash flow support?
What is the business plan?
Then determine which segment of the capital markets fits the transaction.
Whether you're purchasing, refinancing or repositioning an apartment property, understanding NOI, DSCR, LTV, debt yield, lender requirements and exit strategy gives you a much stronger foundation for evaluating financing options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok