Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
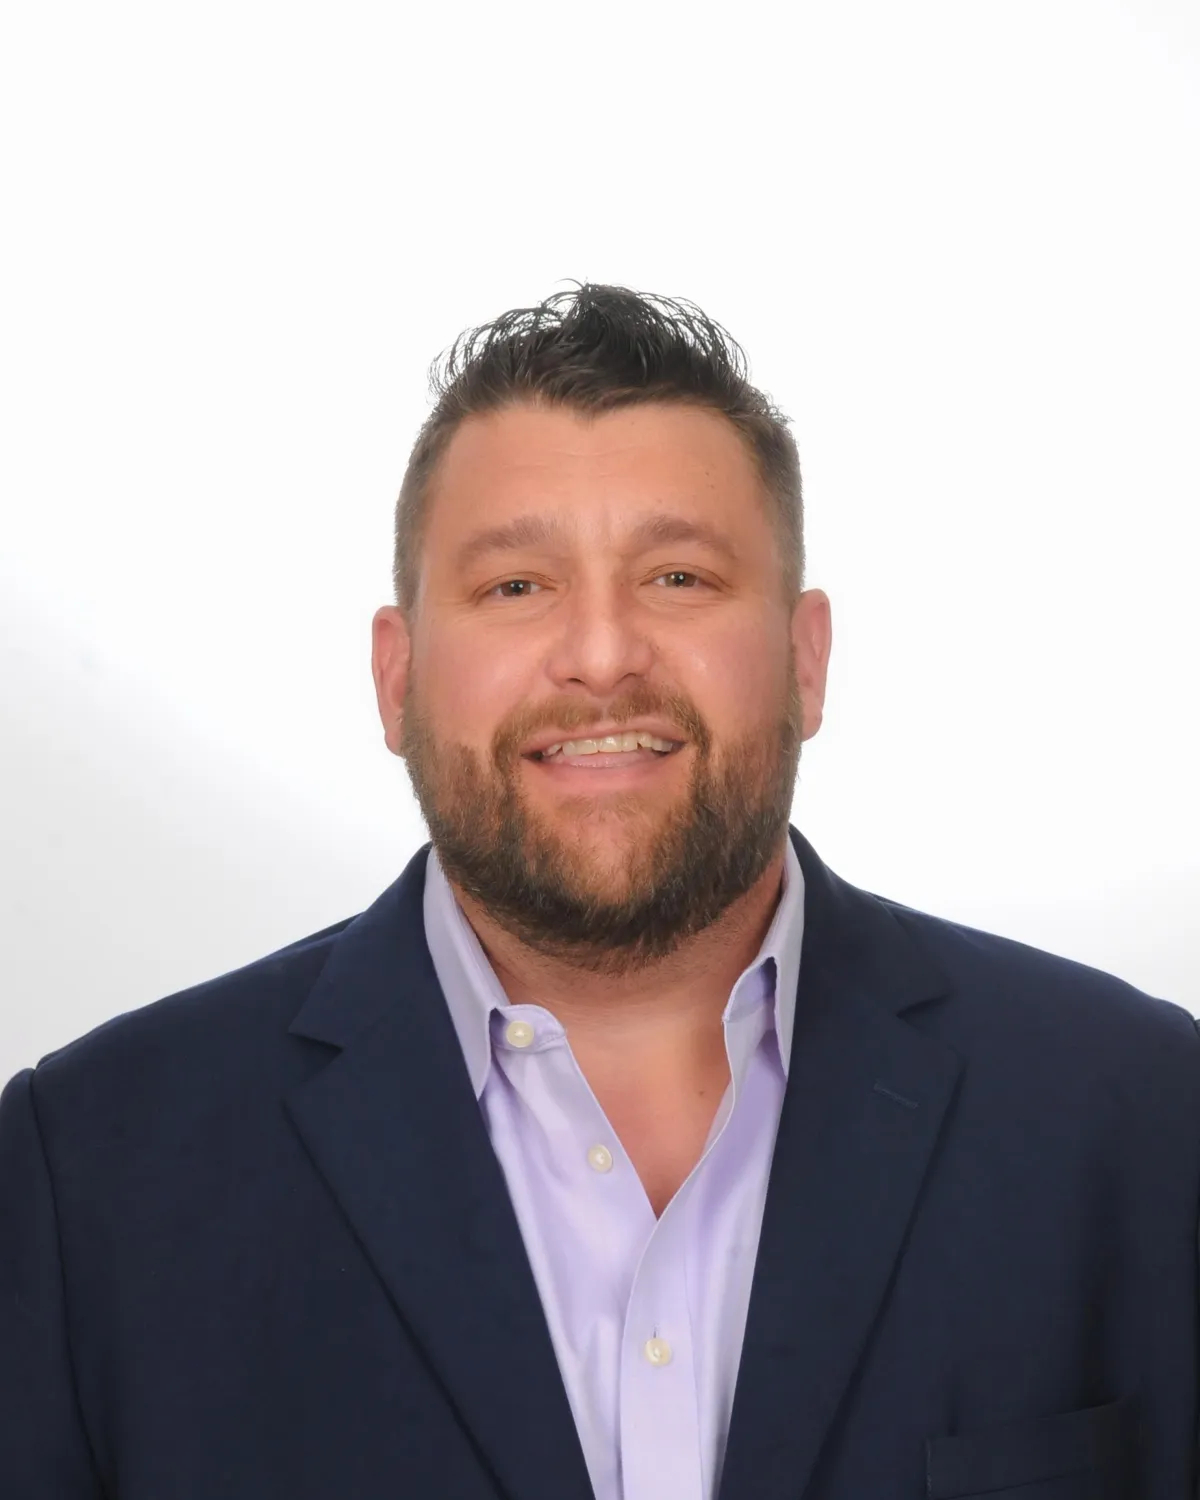
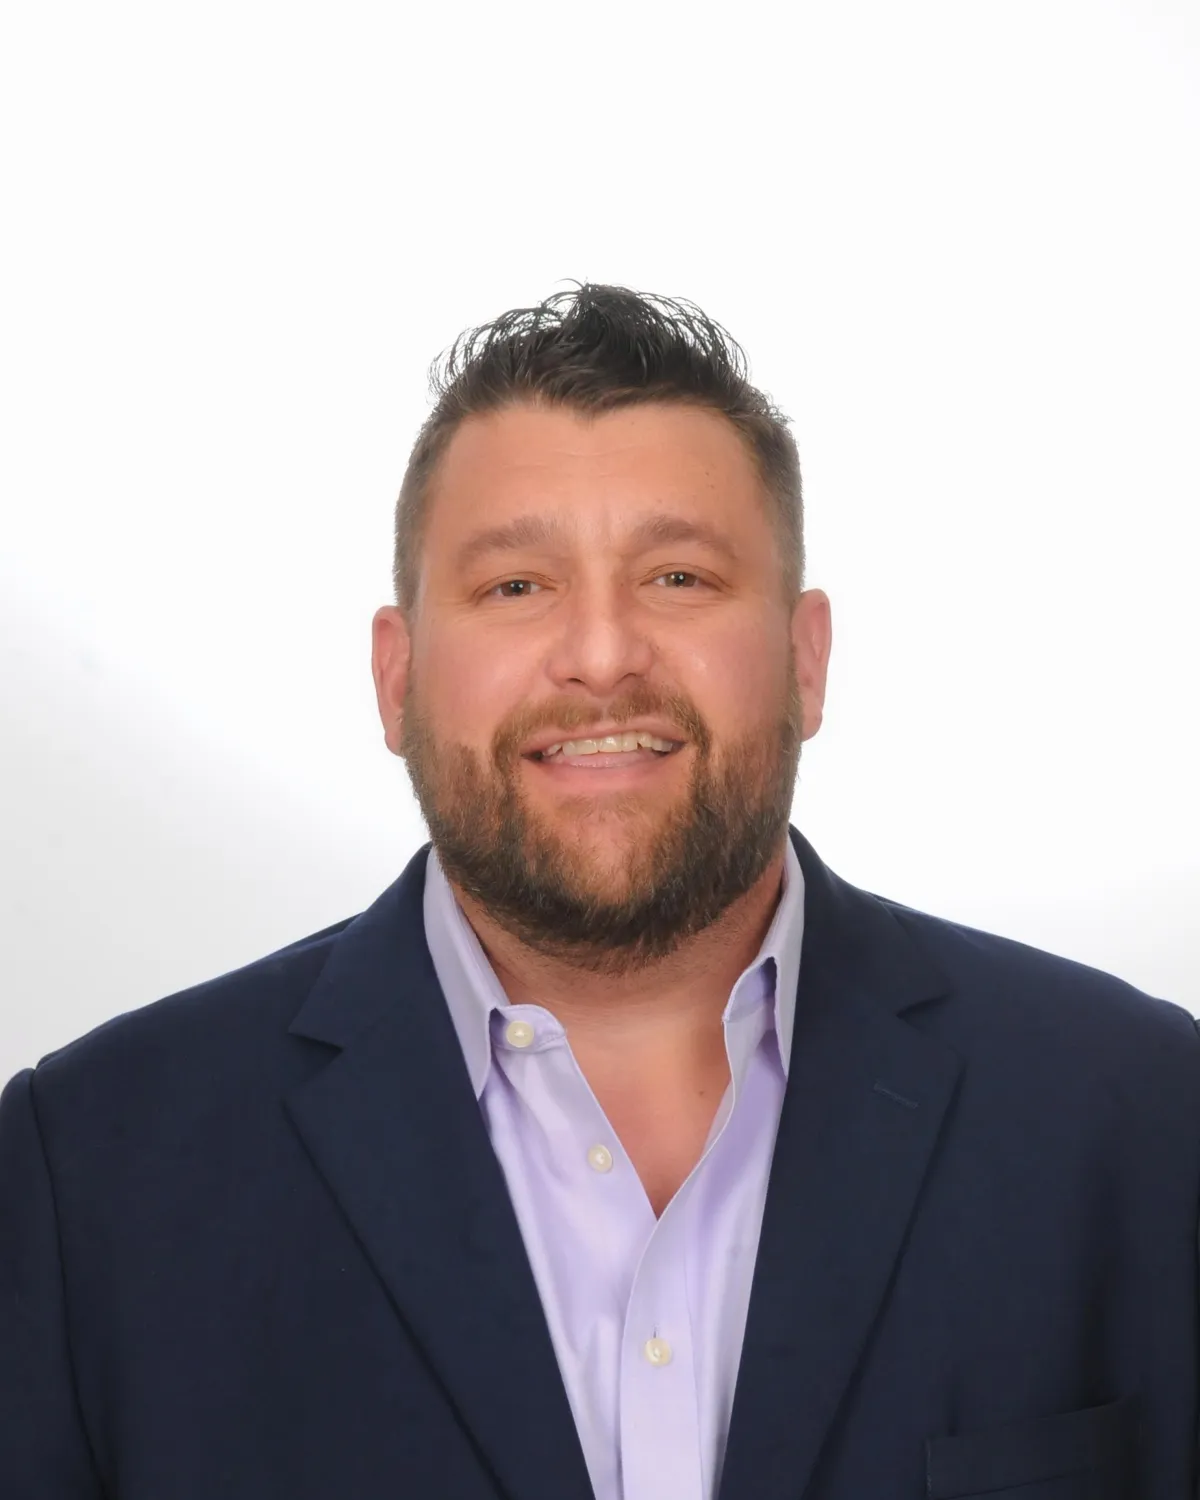
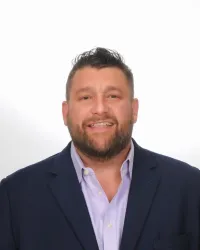
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
💰 Why CRE Brokers Must Learn Financing 🏢
💰 Why CRE Brokers Must Learn Financing 🏢
🚀 CRE Financing: Close More Deals 🔑
_____________________________________________________________________________
Why Commercial Real Estate Brokers Should Learn CRE Financing
By Bill Rapp, CCIM | CommLoan
In commercial real estate, finding the right property is only half the battle. The other half is finding the capital to make the transaction happen.
A commercial real estate broker can identify an excellent investment, negotiate favorable purchase terms, and bring a qualified buyer to the table. But if the financing falls apart, the entire transaction can collapse.
That is why understanding commercial real estate financing is one of the most valuable skills a CRE broker can develop.
Whether you specialize in industrial properties, multifamily investments, retail centers, office buildings, or owner-occupied commercial real estate, knowing how lenders evaluate transactions can help you close more deals, deliver greater value to clients, and differentiate yourself from the competition.
1. Financing Is Often the Difference Between Closing and Losing a Deal
Commercial real estate transactions are significantly more complex than residential home purchases.
Commercial lenders evaluate not only the borrower but also the property, its income, operating expenses, tenant quality, market conditions, and overall investment risk.
A property that appears attractive to an investor may not meet a lender's underwriting requirements.
Common reasons commercial real estate loans encounter problems include:
Insufficient debt service coverage ratio (DSCR)
Excessive loan-to-value ratio (LTV)
Weak borrower liquidity or net worth
High vacancy or unstable rental income
Environmental concerns
Short remaining lease terms
Significant deferred maintenance
Property-specific lending restrictions
A commercial real estate broker who understands these factors can identify potential financing challenges before a client spends thousands of dollars on inspections, appraisals, legal fees, and due diligence.
Instead of waiting until financing becomes a problem, knowledgeable brokers can help clients address capital requirements from the beginning.
2. Understanding Commercial Loan Programs Creates More Opportunities
Not every commercial property fits the same loan program.
One of the biggest mistakes real estate professionals make is assuming that traditional bank financing is the only available option.
The commercial lending market includes a wide variety of capital sources, each with different underwriting standards, risk tolerances, and loan structures.
Conventional Commercial Loans
Traditional banks and credit unions often provide financing for stabilized commercial properties and financially qualified borrowers.
These loans can be attractive for investors and business owners seeking competitive pricing and established banking relationships.
SBA 7(a) and SBA 504 Loans
Small Business Administration financing can be an excellent option for eligible business owners purchasing commercial real estate for their own operations.
Depending on the program, property type, borrower qualifications, and project structure, SBA financing may offer lower equity requirements and longer amortization periods than conventional financing.
This can be particularly valuable for:
Medical and dental practices
Manufacturing companies
Restaurants
Professional service firms
Automotive businesses
Owner-operated industrial facilities
A broker who understands SBA financing may help a business owner recognize that purchasing a building is more achievable than they originally believed.
Bridge Loans
Bridge financing can help investors acquire or reposition properties that do not currently qualify for permanent financing.
These loans may be appropriate for properties with vacancy, renovation requirements, lease-up opportunities, or other transitional characteristics.
However, borrowers must evaluate higher financing costs, shorter loan terms, and the feasibility of their exit strategy.
CMBS Loans
Commercial mortgage-backed securities, or CMBS loans, can provide financing for qualifying income-producing commercial properties.
These loans may offer competitive fixed-rate structures and nonrecourse financing, subject to standard carve-outs and other requirements.
Borrowers should also understand potential prepayment restrictions and servicing complexities.
Agency Multifamily Loans
Fannie Mae and Freddie Mac financing programs can provide attractive options for qualifying multifamily properties.
These programs often feature longer amortization periods and competitive financing structures, although property eligibility and underwriting requirements vary.
Private Credit and Alternative Financing
Private lenders and alternative capital providers may offer solutions for transactions that fall outside traditional bank lending guidelines.
These options can be valuable for complex acquisitions, redevelopment projects, and time-sensitive opportunities.
Understanding the advantages and limitations of each loan program allows CRE brokers to help clients explore financing strategies that align with their investment objectives.
3. Learn the Financial Metrics That Drive Commercial Lending
Commercial real estate brokers do not need to become full-time underwriters. However, they should understand the financial metrics lenders use to evaluate a transaction.
Net Operating Income (NOI)
Net operating income represents the property's operating revenue minus its operating expenses, before debt service, depreciation, and income taxes.
NOI is fundamental to commercial property valuation and loan underwriting.
Debt Service Coverage Ratio (DSCR)
DSCR measures a property's ability to cover its annual loan payments.
DSCR = Net Operating Income ÷ Annual Debt Service
For example, a property generating $250,000 in annual NOI with annual loan payments of $200,000 has a DSCR of 1.25x.
Many commercial lenders seek minimum DSCR levels around 1.20x to 1.35x, although requirements vary by lender, property type, and loan program.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's value.
LTV = Loan Amount ÷ Property Value
A $3 million loan secured by a property valued at $4 million represents a 75% LTV.
Debt Yield
Debt yield measures the property's NOI relative to the loan amount.
Debt Yield = Net Operating Income ÷ Loan Amount
Unlike DSCR, debt yield is not directly affected by the interest rate or amortization schedule.
Some commercial lenders use debt yield to limit loan proceeds and evaluate their exposure to property-level cash flow.
Understanding these metrics helps brokers identify potential financing limitations before submitting an offer or negotiating a purchase agreement.
4. Real-World Example: When the Financing Changes the Deal
Consider an investor purchasing a multi-tenant industrial property for $4 million.
The property generates $280,000 in annual NOI.
The buyer expects to obtain a loan at 75% LTV, requiring $1 million in equity before closing costs.
Here is the proposed financing:
Financing Metric | Amount |
Purchase price | $4,000,000 |
Annual NOI | $280,000 |
Requested loan | $3,000,000 |
Requested LTV | 75% |
Illustrative interest rate | 7.00% |
Amortization | 25 years |
Annual debt service | Approximately $254,440 |
DSCR | Approximately 1.10x |
If the lender requires a minimum DSCR of 1.25x, the requested loan does not qualify under these assumptions.
The maximum allowable annual debt service would be:
$280,000 ÷ 1.25 = $224,000
At the same illustrative interest rate and amortization, the maximum loan amount would be approximately $2.64 million.
The investor would need approximately $1.36 million in equity instead of $1 million, excluding closing costs and reserves.
That represents an additional equity requirement of approximately $359,000.
A broker who understands commercial financing could identify this potential shortfall before the purchase agreement is finalized.
Possible solutions might include:
Negotiating a lower purchase price
Increasing the buyer's equity contribution
Exploring alternative lenders
Evaluating a longer amortization period
Improving documented property cash flow
Restructuring the transaction
The lesson is simple: the maximum advertised LTV does not necessarily determine the actual loan amount.
Cash flow and lender underwriting can be equally important.
5. Financing Knowledge Makes Brokers More Valuable to Investors
Experienced commercial real estate investors expect their brokers to understand more than property availability and comparable sales.
They want professionals who understand how an acquisition fits into their overall investment strategy.
Financing directly affects:
Cash-on-cash returns
Leveraged investment returns
Equity requirements
Cash flow after debt service
Refinancing risk
Capital expenditure reserves
Exit strategies
A broker who understands financing can help investors evaluate opportunities more effectively.
For example, two properties may have identical capitalization rates but produce significantly different cash-on-cash returns because of differences in loan terms, interest rates, amortization, and lender requirements.
The right financing strategy can materially influence the performance of a commercial real estate investment.
6. Help Business Owners Transition From Leasing to Ownership
Commercial real estate brokers frequently work with business owners who assume leasing is their only realistic option.
However, eligible owner-occupants may qualify for financing structures that make purchasing commercial real estate more accessible.
Consider a dentist leasing office space for a growing practice.
Instead of renewing another long-term lease, the dentist could explore purchasing a medical office building using an eligible SBA or conventional commercial loan.
Ownership may offer opportunities to:
Build equity over time
Gain greater control over occupancy costs
Customize the property for business operations
Create a long-term real estate asset
Potentially generate retirement income through future leasing
Ownership is not always the right choice. Business owners must also consider maintenance costs, taxes, insurance, liquidity requirements, and the opportunity cost of investing capital in real estate.
Nevertheless, a broker who understands financing can help clients evaluate the lease-versus-buy decision more comprehensively.
7. Financing Knowledge Helps Brokers Protect Their Transactions
Commercial real estate transactions can take months to complete.
When financing is addressed too late, brokers may encounter unnecessary delays, contract extensions, renegotiations, or failed closings.
A financing-aware broker can improve the transaction process by encouraging clients to:
Obtain an early financing assessment
Prepare financial documentation
Review property operating statements
Evaluate borrower liquidity
Understand lender due diligence requirements
Establish realistic closing timelines
Identify backup financing strategies
These steps can reduce uncertainty and improve communication among buyers, sellers, lenders, attorneys, and other transaction participants.
Financing knowledge does not eliminate risk, but it helps brokers identify and manage that risk earlier.
8. Create Additional Business Opportunities Through Commercial Lending
Learning commercial real estate financing can also help brokers expand their professional relationships and business opportunities.
A commercial real estate transaction may generate future financing needs long after the initial closing.
These opportunities include:
Commercial mortgage refinancing
Cash-out refinancing
Construction financing
Acquisition financing
Portfolio financing
Business expansion loans
Bridge financing
Commercial loan maturity and balloon payment solutions
By developing relationships with experienced commercial mortgage professionals, brokers can remain valuable resources throughout their clients' investment and business ownership journeys.
Where permitted by applicable laws, licensing requirements, brokerage policies, and compensation agreements, commercial real estate professionals may also explore structured referral or commercial lending opportunities.
The objective should always be to provide appropriate financing solutions while maintaining transparency and protecting the client's interests.
9. How the CommLoan Empower Program Can Help
Commercial real estate brokers do not have to build an entire commercial lending platform from scratch.
The CommLoan Empower Program provides an opportunity for real estate professionals to explore commercial mortgage financing resources, education, technology, and lender access.
CommLoan's commercial mortgage marketplace and CUPID™ technology are designed to help connect commercial borrowers with financing options across a broad range of property types and transaction structures.
Working with experienced commercial financing professionals can help brokers:
Better understand commercial loan programs
Identify potential financing solutions
Recognize underwriting challenges
Strengthen relationships with investors and business owners
Expand their commercial real estate knowledge
Explore additional business opportunities
Combining brokerage expertise with capital markets knowledge can create a more comprehensive client experience.
Frequently Asked Questions About CRE Financing for Brokers
Do commercial real estate brokers need to understand financing?
Yes. Understanding financing helps brokers evaluate transaction feasibility, identify potential underwriting challenges, and guide clients toward appropriate commercial lending resources.
Can a commercial real estate broker also arrange commercial loans?
Depending on the jurisdiction, transaction type, licensing requirements, and brokerage policies, real estate professionals may be able to participate in commercial financing activities or establish referral relationships. Applicable regulations and compensation requirements should be reviewed before engaging in these activities.
What is the most important commercial lending metric?
There is no single metric that determines every loan approval. Lenders commonly evaluate DSCR, LTV, debt yield, borrower financial strength, property condition, and other risk factors together.
Can learning CRE financing help brokers close more transactions?
It can help brokers identify financing problems earlier, improve transaction preparation, and connect clients with suitable capital sources. However, financing approval and transaction completion are never guaranteed.
What commercial loan programs should brokers understand?
Brokers should become familiar with conventional commercial mortgages, SBA 7(a), SBA 504, bridge financing, CMBS loans, agency multifamily financing, and alternative commercial lending options.
Final Thoughts: Become More Than a Transactional Broker
The most valuable commercial real estate professionals understand both the property and the capital required to acquire it.
Learning commercial real estate financing can help you become a better advisor, identify stronger investment opportunities, protect transactions, and build lasting relationships with clients.
You do not have to become a full-time commercial mortgage broker to benefit from financing knowledge.
You simply need to understand how capital works, how lenders evaluate risk, and where to find the appropriate financing resources.
Are you a commercial real estate broker interested in expanding your financing knowledge and growing your business?
Explore the CommLoan Empower Program and discover how commercial real estate financing can complement your brokerage business.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok