Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
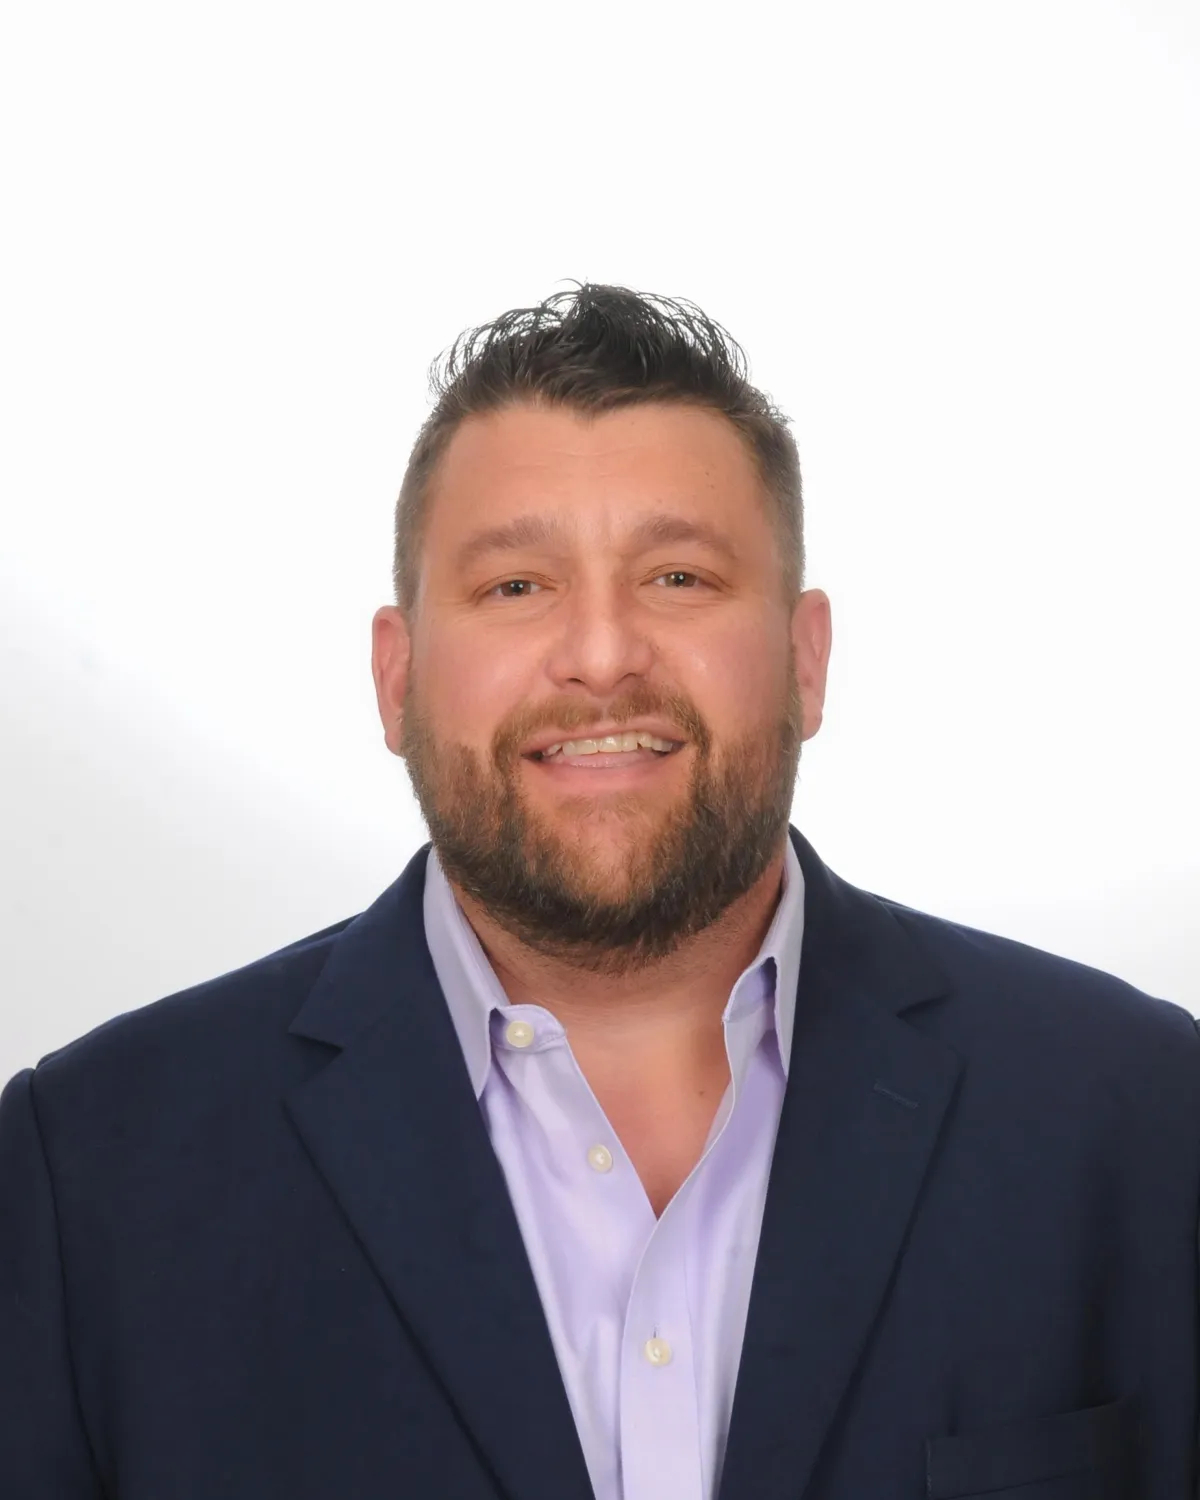
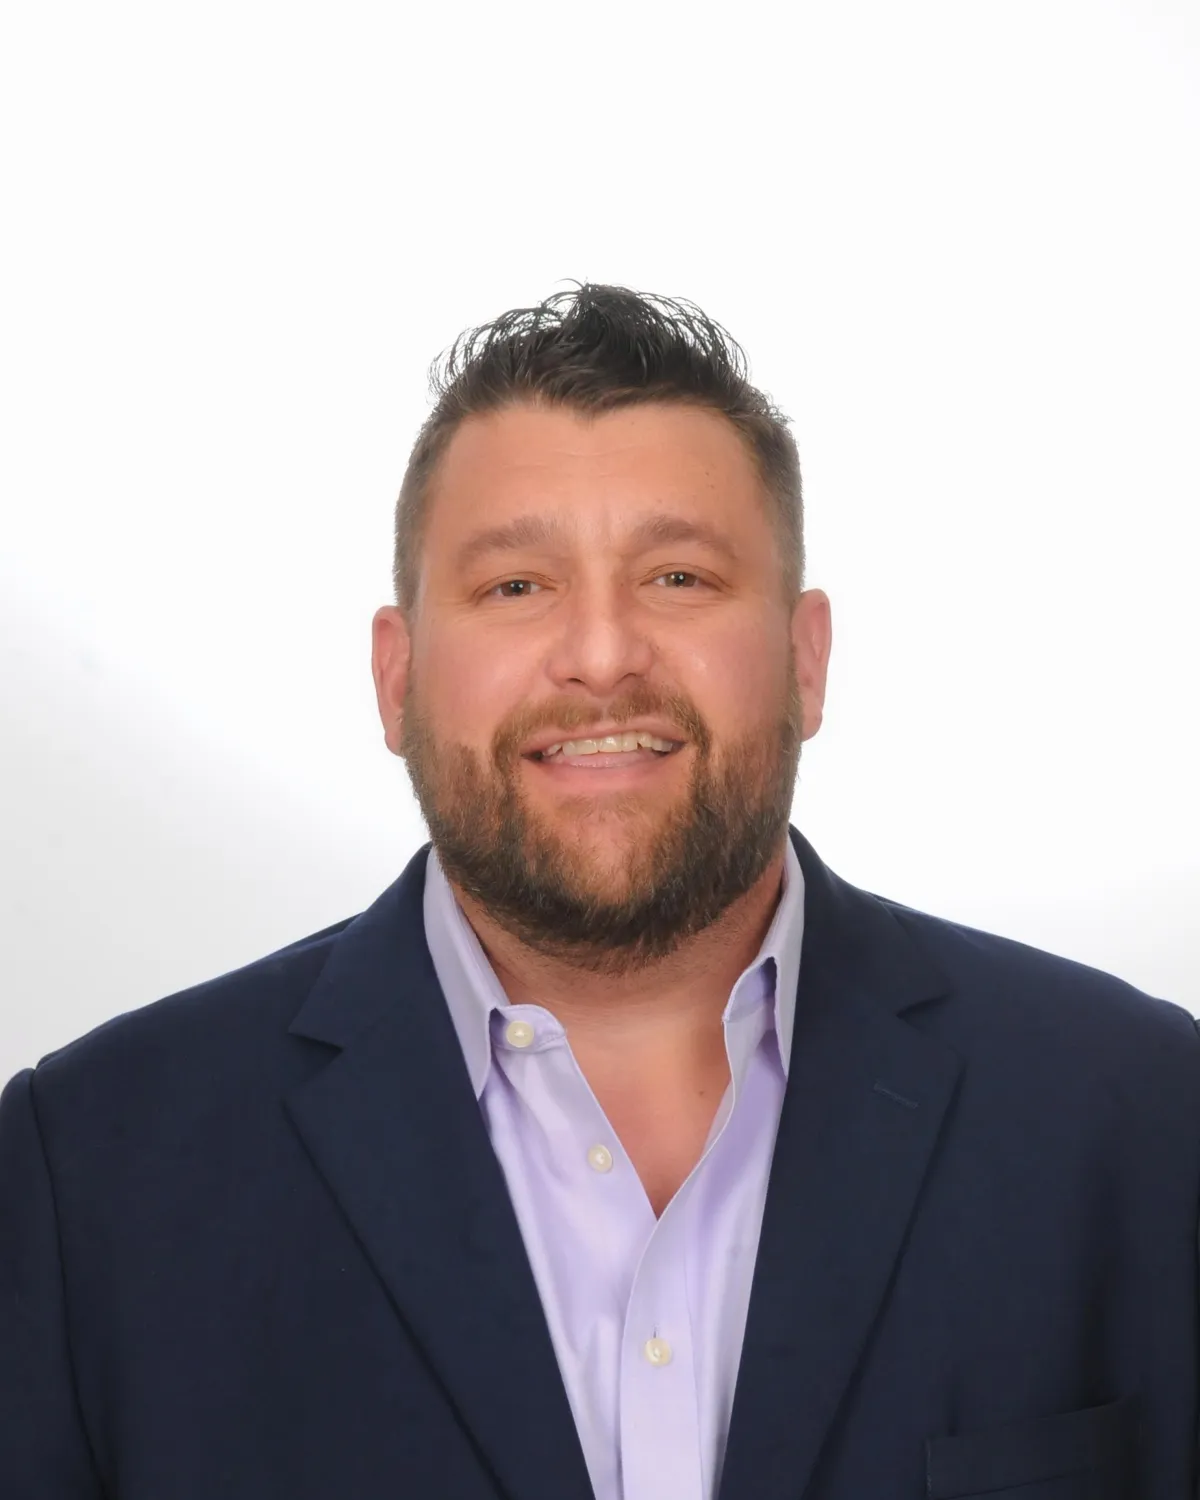
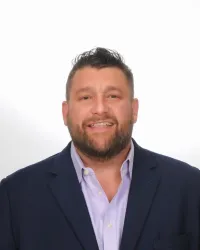
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
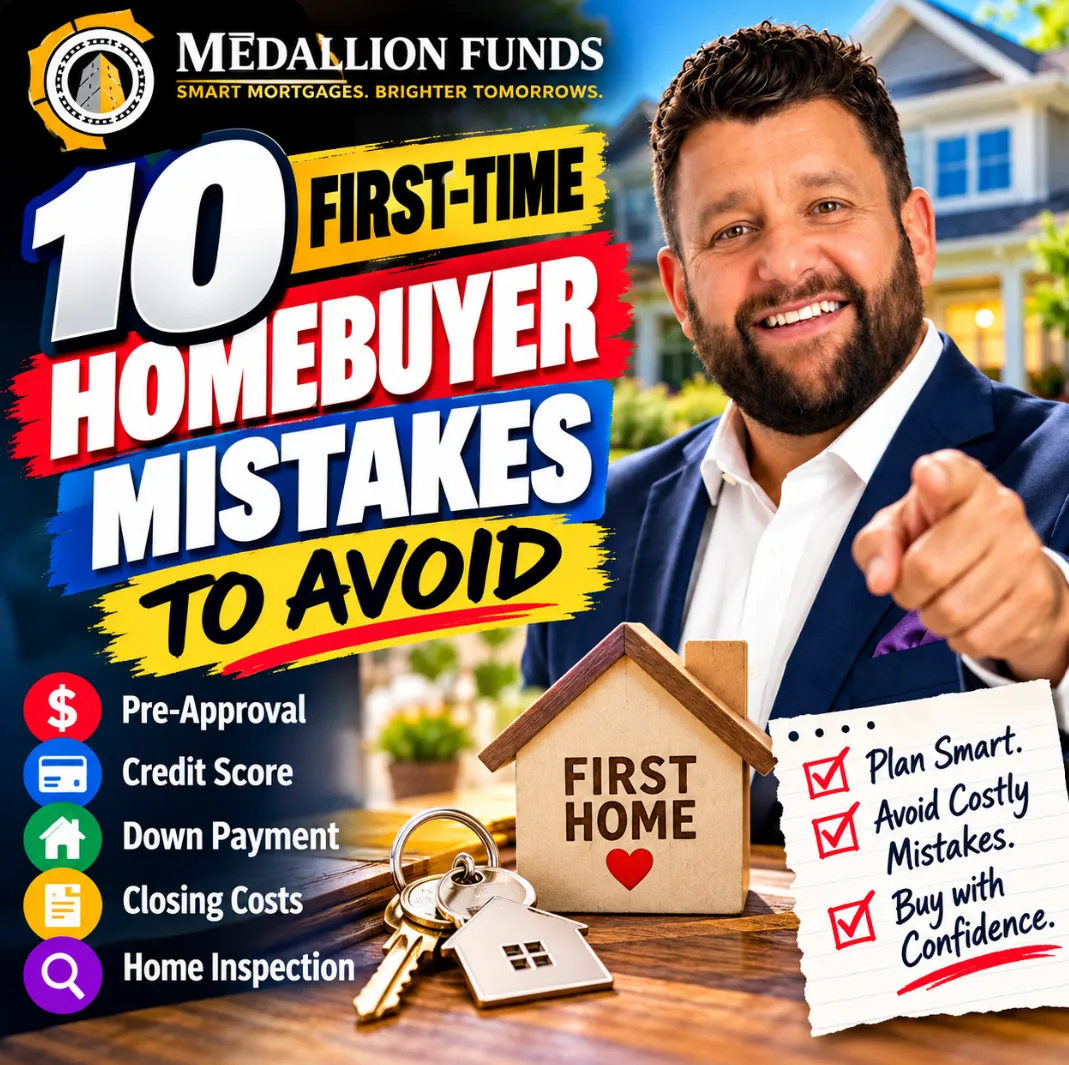
🏡 10 First-Time Homebuyer Mistakes to Avoid 🚨
🏡 10 First-Time Homebuyer Mistakes to Avoid 🚨
🚨 First-Time Homebuyer Mistakes That Cost You Money 💰
_______________________________________________________________________________
🏡 10 First-Time Homebuyer Mistakes to Avoid Before Buying a House
Buying your first home is exciting, but one financial mistake could cost you thousands of dollars, delay your closing, or prevent you from qualifying for the mortgage you need.
For many first-time homebuyers, the biggest challenge isn't finding the right property. It's understanding how mortgage financing, credit scores, down payments, closing costs, and lender requirements affect the purchase.
The good news? Most first-time homebuyer mistakes are avoidable with the right preparation.
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds, and I help homebuyers evaluate mortgage programs, understand financing requirements, and make informed decisions throughout the homebuying process.
Whether you're buying your first home in Houston, Katy, Fulshear, Richmond, or elsewhere in Texas, these 10 common mistakes can help you understand what to avoid before signing a purchase contract.
1. 🚨 Shopping for a House Before Getting Pre-Approved
One of the most common first-time homebuyer mistakes is touring properties before understanding your mortgage qualifications.
Without a mortgage pre-approval, you may fall in love with a home that exceeds your comfortable budget or discover financing issues after making an offer.
A mortgage pre-approval generally involves a lender reviewing your income, credit, assets, and existing debts to assess your potential borrowing capacity.
How to avoid this mistake:
·Speak with a mortgage professional before seriously shopping.
·Gather income statements, bank statements, and other requested documents.
·Understand the difference between pre-qualification and pre-approval.
·Ask what conditions remain before final loan approval.
Pro Tip: Pre-approval helps you shop more confidently, but it is not a guarantee of final mortgage approval.
2. 💳 Making Major Purchases Before Closing
That new furniture, vehicle, or expensive appliance may seem like the perfect addition to your future home.
However, financing major purchases before closing can change your debt-to-income ratio, reduce your available cash, or affect your credit profile.
Mortgage lenders may review your credit and financial situation again before funding.
How to avoid this mistake:
·Avoid opening unnecessary credit accounts.
·Do not finance a vehicle or furniture without discussing it with your lender.
·Maintain adequate funds for closing and reserves.
·Consult your mortgage professional before making significant financial changes.
Pro Tip: Wait until your mortgage has closed and funded before taking on major new debt whenever possible.
3. 💰 Underestimating Closing Costs
Many first-time buyers focus almost exclusively on saving for their down payment.
But the down payment is only one part of the total cash needed to purchase a home.
Depending on the transaction, closing expenses may include:
·Appraisal and lender fees
·Title and settlement charges
·Prepaid homeowners insurance
·Initial property tax and insurance escrow deposits
·Recording and other applicable fees
Closing costs can vary substantially by location, loan type, lender, and transaction.
How to avoid this mistake:
Ask for a detailed Loan Estimate and review your expected cash to close, not just your down payment.
Also ask whether seller contributions, lender credits, or eligible assistance programs could reduce your upfront expenses.
4. 📉 Ignoring Your Credit Score Before Applying
Your credit profile can influence mortgage eligibility, available loan programs, pricing, and interest rates.
Some buyers mistakenly assume they need perfect credit, while others apply without checking their credit reports for errors.
Different mortgage programs have different credit requirements, and individual lenders may apply additional standards.
How to avoid this mistake:
·Review your credit reports early.
·Correct legitimate reporting errors.
·Make payments on time.
·Avoid unnecessary new credit inquiries.
·Discuss potential credit improvements with your mortgage professional.
Pro Tip: Even a modest improvement in your credit profile may create additional financing options, depending on the loan program and lender.
5. 🏦 Assuming Your Bank Offers the Best Mortgage
Many buyers automatically contact the bank where they maintain their checking or savings accounts.
But one lender may not offer every mortgage program or the most competitive terms for your situation.
A mortgage broker can help compare options from multiple participating lenders, including programs for conventional borrowers, veterans, doctors, self-employed buyers, and eligible first-time homebuyers.
How to avoid this mistake:
Compare mortgage offers based on:
·Interest rate and annual percentage rate (APR)
·Discount points and lender fees
·Total estimated closing costs
·Mortgage insurance
·Loan structure and qualification requirements
·Estimated monthly payment
Pro Tip: Compare Loan Estimates for the same loan scenario and rate-lock assumptions whenever possible.
6. 🏠 Focusing Only on the Mortgage Payment
Your principal and interest payment are not necessarily your total monthly housing expense.
First-time homebuyers must also account for property taxes, homeowners insurance, mortgage insurance when applicable, homeowners association fees, and ongoing maintenance.
This is particularly important in Texas, where property taxes and insurance can represent substantial ownership expenses.
How to avoid this mistake:
Build your budget around the full estimated monthly housing cost, not just the advertised principal and interest payment.
Also maintain savings for repairs and unexpected expenses.
7. 🔑 Assuming You Need 20% Down
One of the most persistent mortgage myths is that every buyer needs a 20% down payment.
In reality, several programs may allow eligible borrowers to purchase a primary residence with substantially less.
Examples include:
·Conventional loans: Certain programs permit down payments as low as 3%.
·FHA loans: Eligible borrowers may qualify with a 3.5% down payment.
·VA loans: Eligible veterans, service members, and other qualified borrowers may obtain financing without a required down payment.
·USDA loans: Eligible borrowers purchasing qualifying properties may have access to zero-down financing.
·Texas down payment assistance: Certain programs, including those administered through TSAHC, may help eligible borrowers with upfront expenses.
Eligibility, income limits, property restrictions, credit standards, mortgage insurance, funding availability, and other conditions vary.
Pro Tip: Zero down payment does not necessarily mean zero cash required at closing.
8. 📋 Changing Jobs or Income During the Mortgage Process
Mortgage qualification depends partly on documenting stable, acceptable income.
Changing employers, switching from salary to commission, becoming self-employed, or taking an extended unpaid leave can complicate underwriting.
Not every job change creates a problem, but lenders must evaluate how the change affects qualifying income.
How to avoid this mistake:
Speak with your mortgage professional before making significant employment or compensation changes during the transaction.
9. 🔍 Skipping the Home Inspection or Ignoring Property Conditions
A mortgage appraisal and a home inspection serve different purposes.
An appraisal generally helps the lender evaluate the property's value and applicable property requirements.
A home inspection is intended to help the buyer understand the property's physical condition.
Skipping an inspection may expose you to expensive repairs involving roofing, foundations, plumbing, electrical systems, HVAC equipment, or water intrusion.
How to avoid this mistake:
Consider hiring a qualified home inspector and evaluating major findings before proceeding.
For Houston-area properties, buyers should also investigate flood risk, insurance availability, and relevant property history.
10. ⏰ Waiting Too Long to Speak With a Mortgage Professional
The biggest first-time homebuyer mistake may be assuming that mortgage planning begins after finding the perfect home.
Early conversations can help buyers identify credit issues, estimate cash requirements, understand loan programs, and establish realistic purchasing timelines.
A qualified mortgage professional can also help explain how interest rates, discount points, mortgage insurance, and closing costs affect the overall financing decision.
How to avoid this mistake:
Start preparing before you make an offer, even if you are several months away from purchasing.
🧮 Real-World Example: Why Planning Matters
Imagine a first-time homebuyer purchasing a $300,000 home in Texas.
Consider two possible financing scenarios:
Financing scenario | Down payment |
3% down conventional mortgage | $9,000 |
3.5% down FHA mortgage | $10,500 |
A buyer who assumes a 20% down payment is required might believe they need $60,000 before they can purchase.
In reality, a qualified borrower may have options with a significantly smaller down payment.
However, both scenarios may still involve closing costs, prepaid expenses, mortgage insurance, and other requirements.
The best mortgage choice depends on the borrower's full financial picture—not simply the smallest down payment.
These examples are illustrations, not loan offers or qualification guarantees.
🏡 Final Thoughts: Buy Your First Home With Confidence
Buying your first home should be an exciting financial milestone, not a series of expensive surprises.
By avoiding these 10 common first-time homebuyer mistakes, you can better prepare for mortgage qualification, evaluate financing options, and make informed decisions about homeownership.
Remember that the lowest advertised mortgage rate is not always the best overall financing solution. Loan structure, fees, monthly affordability, and long-term goals matter too.
📞 Ready to Buy Your First Home?
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're a first-time homebuyer, veteran, medical professional, or self-employed borrower, I can help you explore mortgage financing options suited to your situation.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok