Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
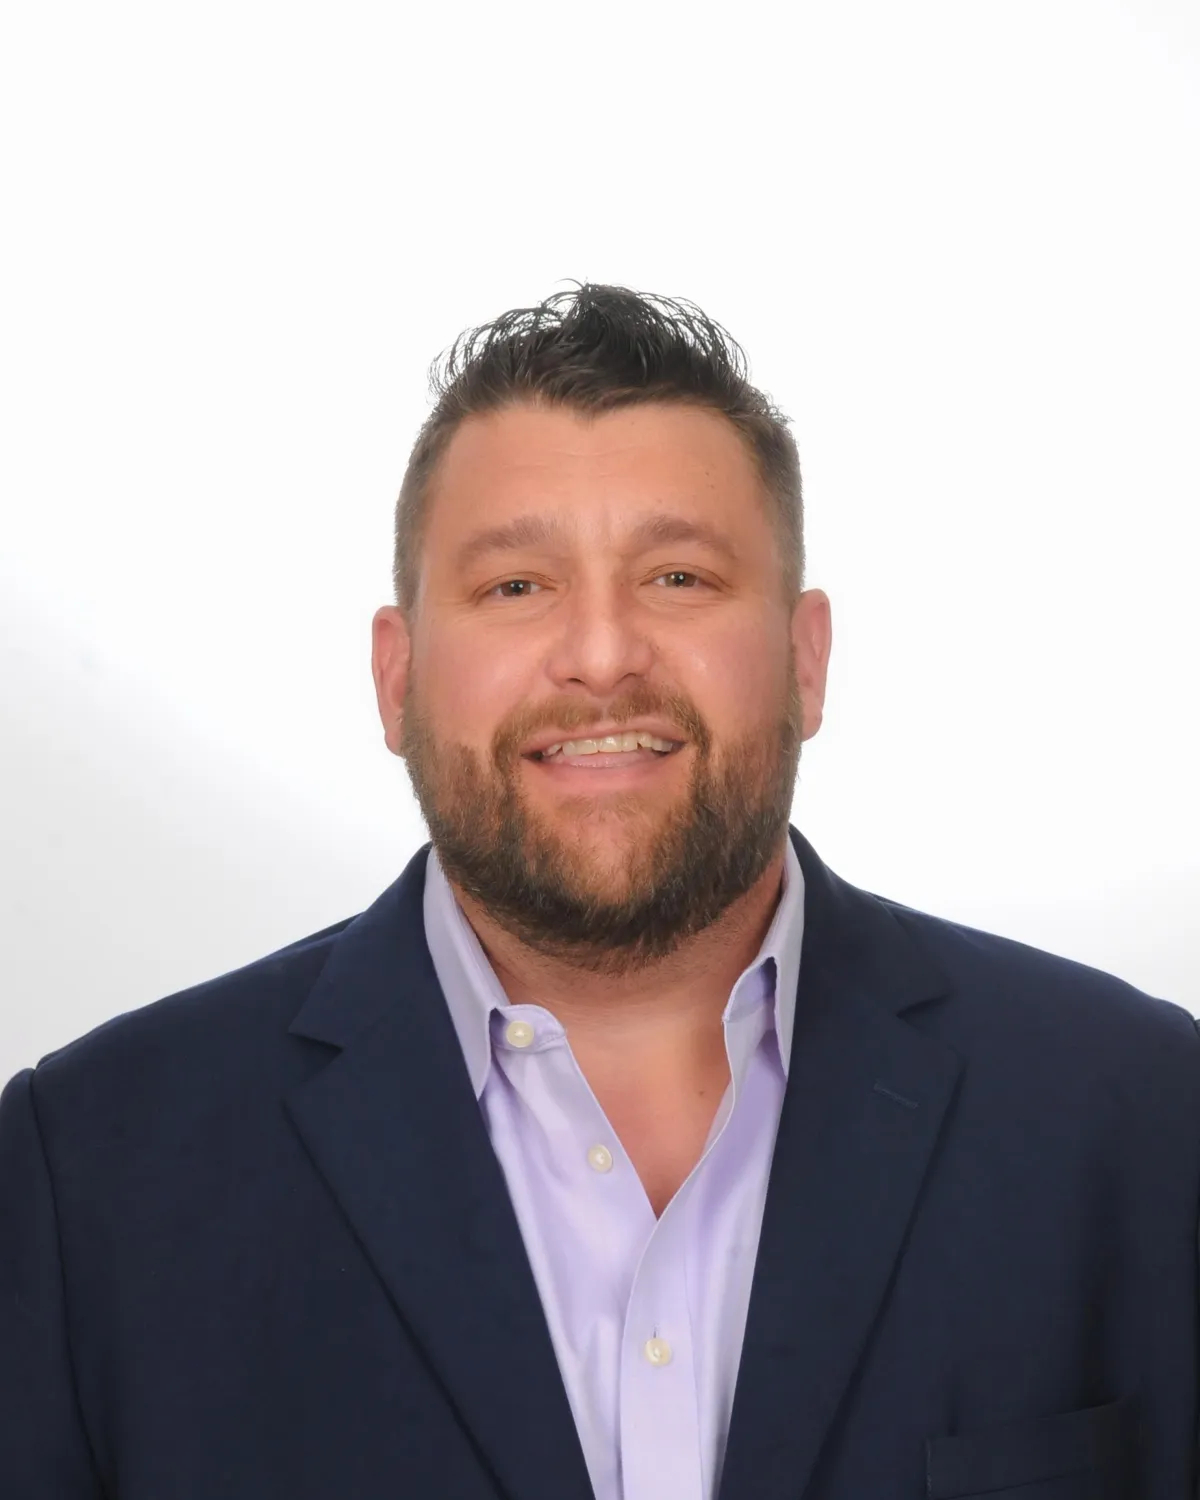
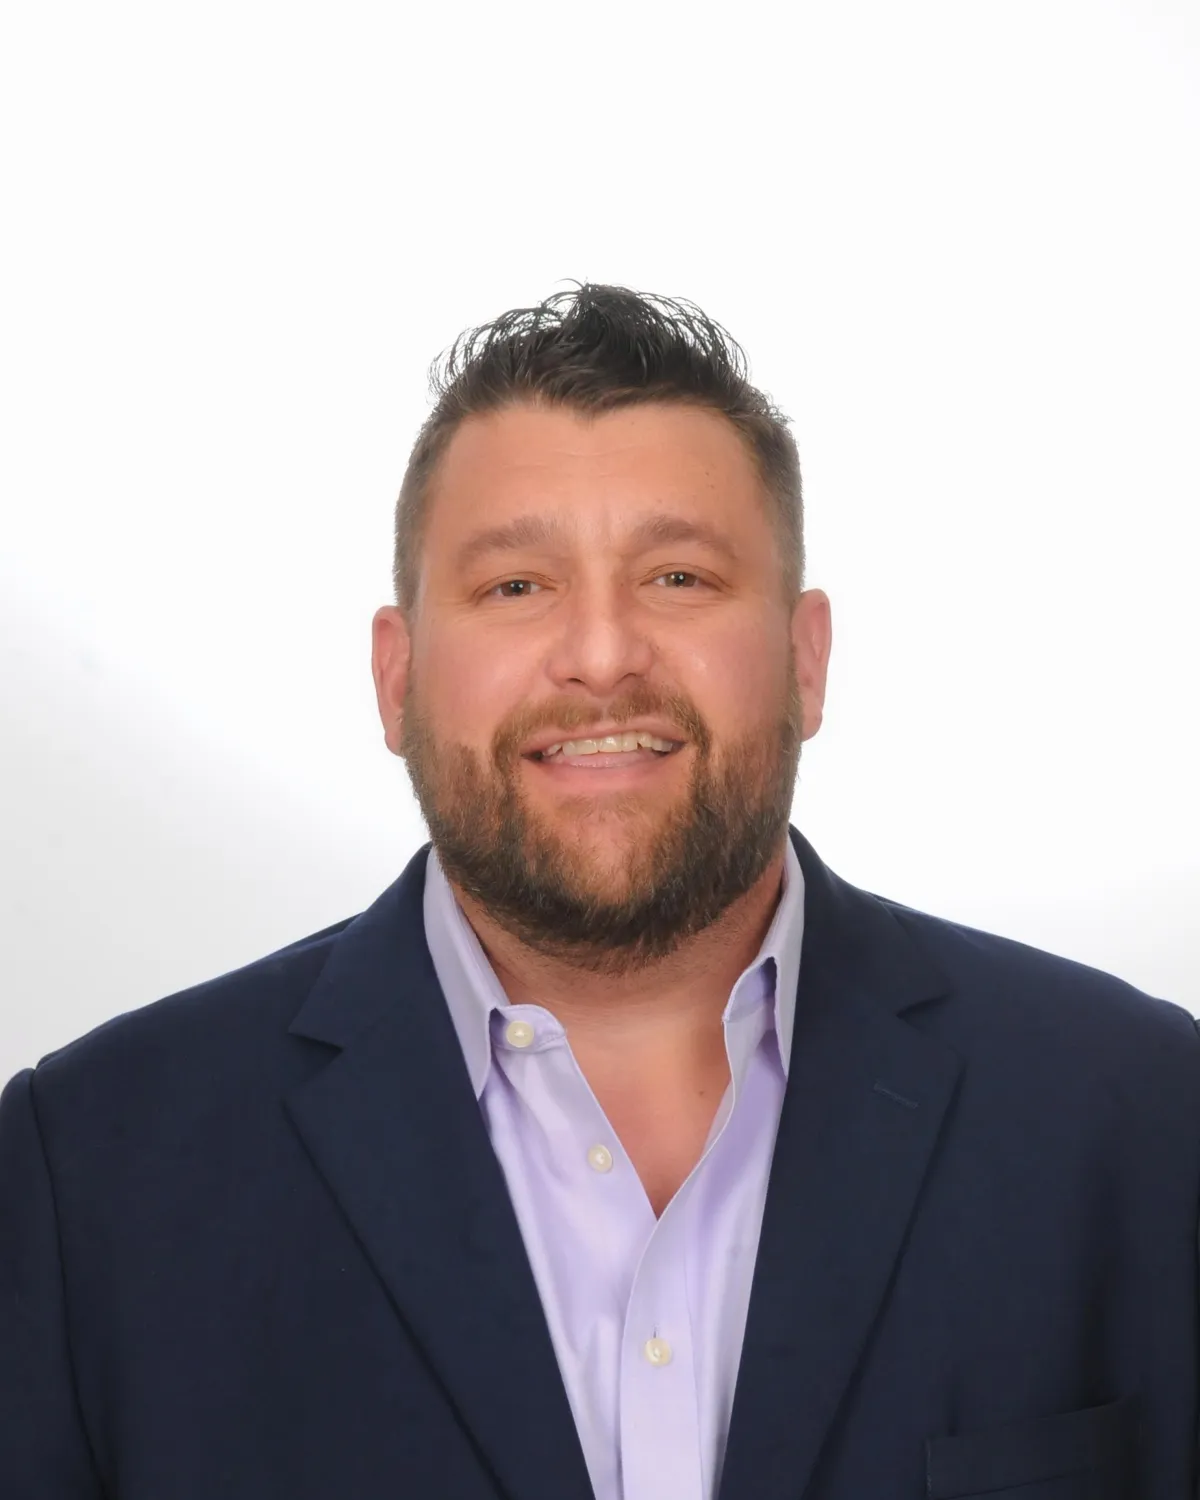
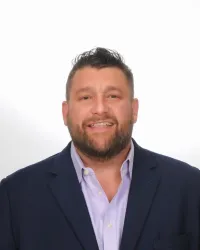
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏡 Builder Mortgage Incentives vs. Outside Lenders 💰
🏡 Builder Mortgage Incentives vs. Outside Lenders 💰
🚨 Builder Lender Incentives: Are You Really Saving? 🏠
________________________________________________________________________________
🏡 Builder Mortgage Incentives vs. Outside Lenders: How to Compare the Real Cost
A $20,000 builder incentive sounds like a great deal. But what if the mortgage attached to that incentive costs you thousands more over time?
If you're shopping for a new-construction home in Houston, Katy, Fulshear, or anywhere in Texas, you've probably seen builders advertising attractive mortgage financing promotions.
Some offer thousands of dollars toward closing costs. Others advertise below-market interest rates, temporary mortgage rate buydowns, or special financing packages through their preferred lenders.
These offers can provide substantial savings.
But here's what every homebuyer needs to understand:
The largest builder incentive doesn't always produce the lowest total mortgage cost.
Before committing to a builder's preferred lender, it's worth comparing that offer against financing from an independent mortgage broker.
I'm Bill Rapp with Medallion Funds, and I help homebuyers evaluate mortgage options, understand financing costs, and make informed decisions about one of their largest financial commitments.
Let's examine how builder mortgage incentives work and how to determine whether the builder's lender or an outside lender offers the better deal.
What Are Builder Mortgage Incentives?
Builder mortgage incentives are financial benefits offered by homebuilders to encourage buyers to purchase new-construction homes.
These incentives often require buyers to finance through the builder's preferred or affiliated mortgage company.
Common incentives include:
·Closing cost credits: Contributions toward eligible mortgage closing costs and prepaid expenses.
·Mortgage rate buydowns: Funds used to reduce the interest rate temporarily or permanently.
·Discount points: Upfront fees paid to obtain a lower mortgage interest rate.
·Title or settlement incentives: Credits associated with using a designated settlement provider, where permitted.
·Design center or upgrade allowances: Credits toward flooring, countertops, appliances, or other upgrades.
·Purchase price reductions: Direct reductions in the home's negotiated sales price.
The important distinction is that these benefits do not all have the same economic value.
A $15,000 closing cost credit, a $15,000 upgrade allowance, and a $15,000 price reduction can affect your finances differently.
Builder's Preferred Lender vs. Outside Mortgage Lender
When you purchase a newly constructed home, the builder may recommend its preferred mortgage company.
That lender may be familiar with the builder's construction timelines, contracts, appraisal procedures, and closing process.
These relationships can make transactions more convenient.
However, an outside mortgage lender or independent mortgage broker may provide additional financing alternatives.
Builder Preferred Lender: Potential Advantages
·Access to exclusive builder-funded financing promotions.
·Coordination with the builder's construction and closing teams.
·Familiarity with the builder's contracts and completion schedules.
·Potential closing cost credits and special rate promotions.
Outside Mortgage Broker: Potential Advantages
·Access to multiple participating wholesale lenders.
·Ability to compare different interest rates, lender fees, and mortgage structures.
·Additional loan program options, depending on eligibility.
·Independent evaluation of financing costs.
·Opportunities to negotiate with the builder using a competing mortgage quote.
The objective isn't to automatically avoid the builder's lender. It's to compare the complete financial package before choosing.
The Hidden Cost of Builder Mortgage Incentives
Consider two financing offers on the same $400,000 new-construction home.
Assume a 10% down payment and a $360,000 mortgage with a 30-year fixed rate.
Financing Detail | Builder's Lender | Outside Lender |
Home price | $400,000 | $400,000 |
Loan amount | $360,000 | $360,000 |
Interest rate | 6.50% | 6.00% |
Builder closing credit | $15,000 | $0 |
Lender fees and points | $12,000 | $3,000 |
Monthly principal and interest | $2,275 | $2,158 |
Illustrative figures, not current rate quotes or actual lender offers. Payments are rounded and exclude property taxes, homeowners insurance, mortgage insurance, and HOA dues.
At first glance, the builder's $15,000 credit looks attractive.
But the builder's lender also charges $9,000 more in lender fees and points.
Assuming the full credit can be applied to eligible costs, the builder's offer provides only a $6,000 net upfront advantage after accounting for that fee difference.
Meanwhile, the outside lender saves approximately $117 per month in principal and interest.
That's approximately $1,404 annually.
Over five years, the lower payment produces approximately $7,020 in cash-flow savings.
And over 30 years, the nominal payment difference adds up to approximately $42,120, assuming the original loans remain outstanding for the full term.
The lower-rate loan also pays down principal faster.
The lesson: Compare upfront cash requirements, ongoing payments, and the expected cost of financing over your anticipated ownership period.
This example does not account for differences in remaining loan balance, tax treatment, investment returns, or potential refinancing. Those factors can materially affect the final decision.
Temporary Mortgage Rate Buydowns: Understand the Catch
Builders frequently advertise temporary rate buydowns.
One popular structure is the 2-1 mortgage rate buydown.
Suppose the mortgage note rate is 6.50%.
A 2-1 buydown could create the following payment schedule:
Period | Effective Payment Rate |
Year 1 | 4.50% |
Year 2 | 5.50% |
Year 3 onward | 6.50% |
The lower initial payments are generally funded through a subsidy established at closing.
The actual note rate remains 6.50%, and the borrower's payment obligation increases according to the buydown schedule.
For many standard temporary buydown programs, borrowers must qualify using the full note-rate payment rather than the reduced introductory payment.
A temporary buydown may be beneficial when you expect your income to increase or need additional cash-flow flexibility during the first years of ownership.
However, you should never assume that refinancing into a lower interest rate will be possible before the temporary subsidy expires.
Always evaluate whether you can comfortably afford the full payment beginning in Year 3.
Permanent Rate Buydowns vs. Closing Cost Credits
Another common builder incentive involves paying discount points to permanently reduce your mortgage interest rate.
For example, a builder may offer a $10,000 financing incentive.
You might have the option to use eligible funds toward closing costs or toward a permanent interest rate reduction.
Which is better?
That depends on your cash position, the lender's pricing, and how long you expect to keep the mortgage.
A permanent rate buydown may be attractive when you expect to retain the loan for many years.
A closing cost credit may be more valuable when preserving cash is your immediate priority.
You should also evaluate the break-even period.
If you pay $6,000 in additional discount points to save $100 per month, your simple payment-savings break-even period is:
$6,000 ÷ $100 = 60 months, or five years.
If you sell or refinance before that point, the upfront expense may not have produced sufficient payment savings to justify its cost.
This simplified calculation does not incorporate amortization differences or the time value of money.
Can You Negotiate Builder Mortgage Incentives?
Often, yes.
Builders may have flexibility in their financing promotions, especially when they want to sell completed inventory or meet sales targets.
Potential negotiation opportunities include:
·Requesting a larger closing cost contribution.
·Asking whether incentives are available with an outside lender.
·Negotiating the purchase price instead of accepting upgrades.
·Requesting an extended rate lock for a delayed closing.
·Comparing financing packages on move-in-ready inventory homes.
However, builder incentives are not always transferable.
Some promotions require the use of a specific lender, and others are available only for designated homes or closing dates.
Get the terms in writing before making a decision.
What Should Texas New-Construction Buyers Watch For?
Texas homebuyers should evaluate more than the mortgage interest rate.
In communities throughout Katy, Fulshear, Richmond, Cypress, and Greater Houston, property taxes and insurance can substantially affect the total monthly housing payment.
Property Taxes and MUD Districts
Some new-construction communities have municipal utility district taxes or other special district assessments.
Additionally, initial property tax estimates may be based on land value or incomplete construction rather than the fully improved property.
Ask for a realistic estimate based on the completed home's anticipated taxable value, applicable tax rates, and exemptions.
Homeowners Insurance
Obtain a property-specific insurance quote before comparing monthly mortgage payments.
Depending on location, construction features, and coverage selections, insurance costs can vary significantly.
HOA and Community Assessments
Include homeowners association dues and any applicable community fees in your affordability analysis.
Flood Insurance
Standard homeowners insurance generally excludes flood damage.
Check the property's flood risk and determine whether flood insurance is required or advisable.
A builder's attractive principal-and-interest payment isn't the same as your complete monthly housing expense.
Seven Questions to Ask Before Choosing a Builder's Lender
1.What is the mortgage interest rate, APR, and total lender fee?
2.Is the advertised rate temporary or fixed for the entire loan term?
3.How much of the builder incentive is restricted to the preferred lender?
4.What discount points are required to obtain the advertised rate?
5.What will my total cash to close be?
6.What happens if construction delays require extending my rate lock?
7.How does the offer compare with an outside lender's written Loan Estimate?
For a reliable comparison, request quotes based on the same loan amount, down payment, loan type, lock period, and estimated closing date.
Review the Loan Estimate's origination charges, services, lender credits, cash to close, and five-year comparison information.
Why Compare Mortgage Options Through Medallion Funds?
At Medallion Funds, our goal is to help borrowers understand their financing choices before they commit to a mortgage.
As a mortgage brokerage, we can evaluate available financing options across participating lenders, subject to program eligibility and pricing.
We help borrowers explore conventional mortgages, FHA loans, VA loans, jumbo financing, and other eligible loan products.
Whether you're purchasing your first home, upgrading to a larger property, or relocating to Texas, we can help you assess the mortgage structure that fits your circumstances.
You don't have to assume the builder's financing is the best deal—or that an outside lender will automatically beat it.
Compare the numbers first.
Final Thoughts: The Best Builder Incentive Is the One That Actually Saves You Money
Builder mortgage incentives can be valuable.
But an advertised $10,000, $15,000, or $20,000 incentive doesn't tell you everything about the true cost of financing.
Look at the interest rate, APR, discount points, closing costs, monthly payment, and expected holding period.
A financing package that looks attractive today may not be the least expensive option over five or ten years.
Before signing your new-construction contract, get a second mortgage quote.
📞 Compare Your New-Construction Mortgage Options
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok