Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
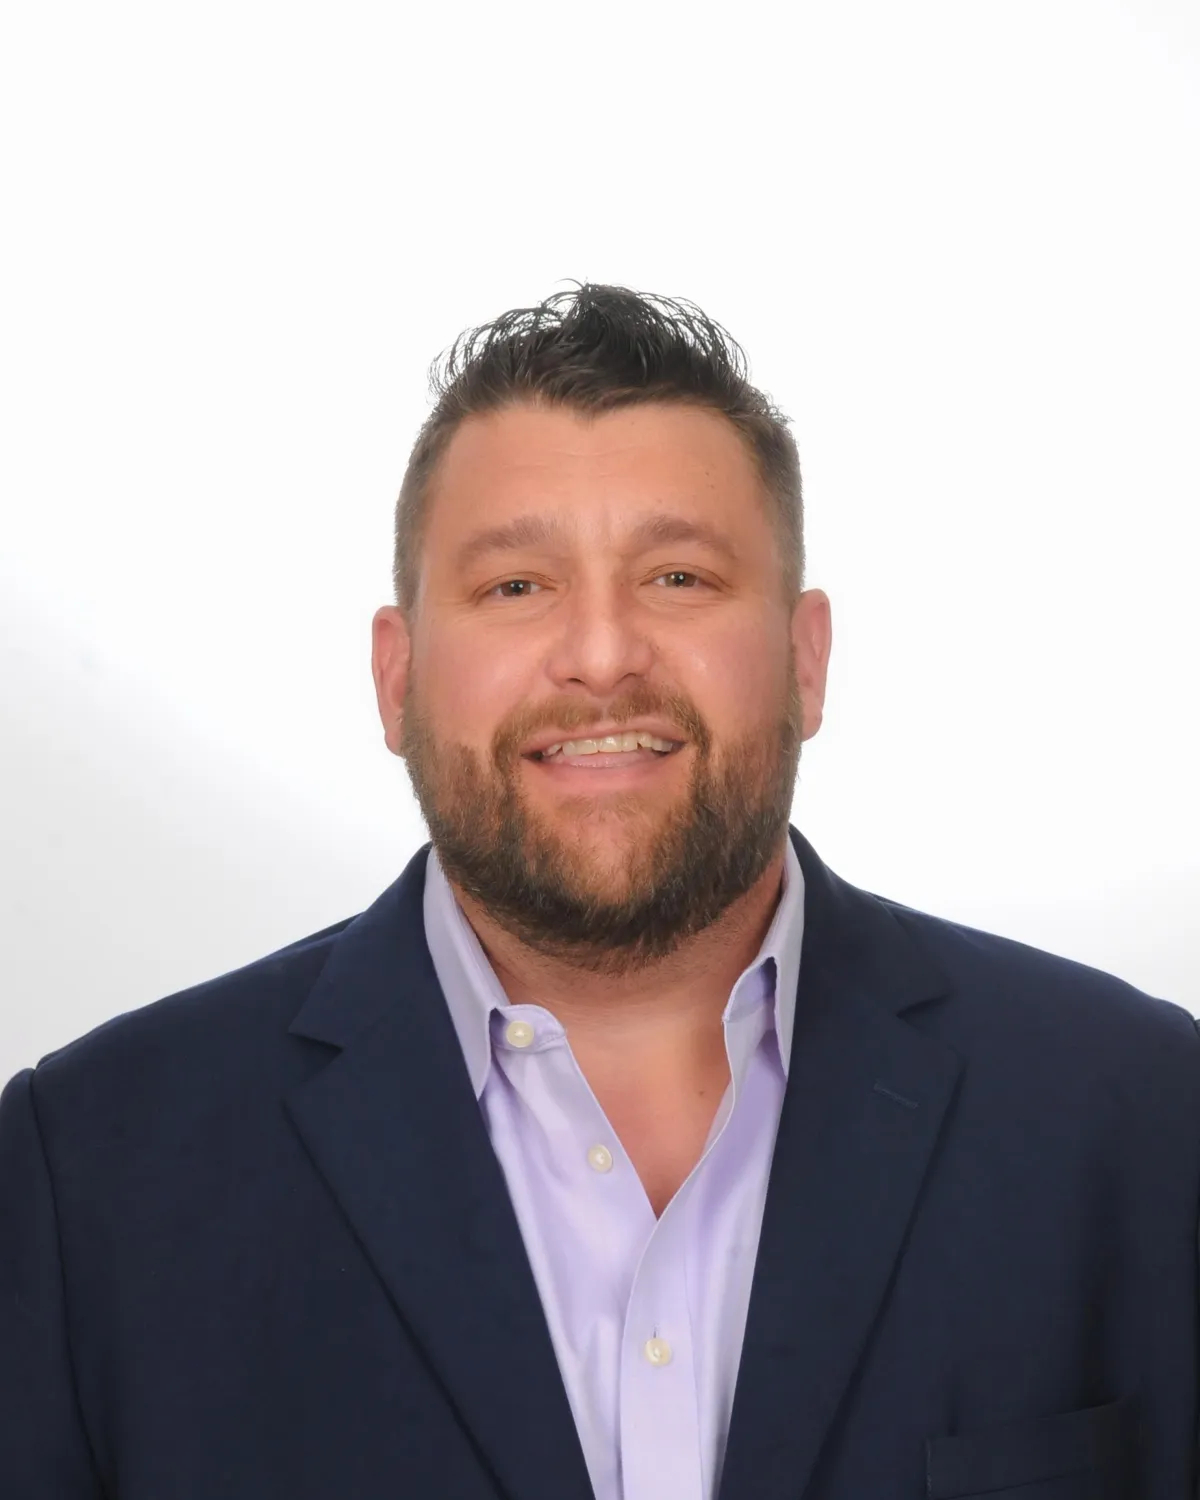
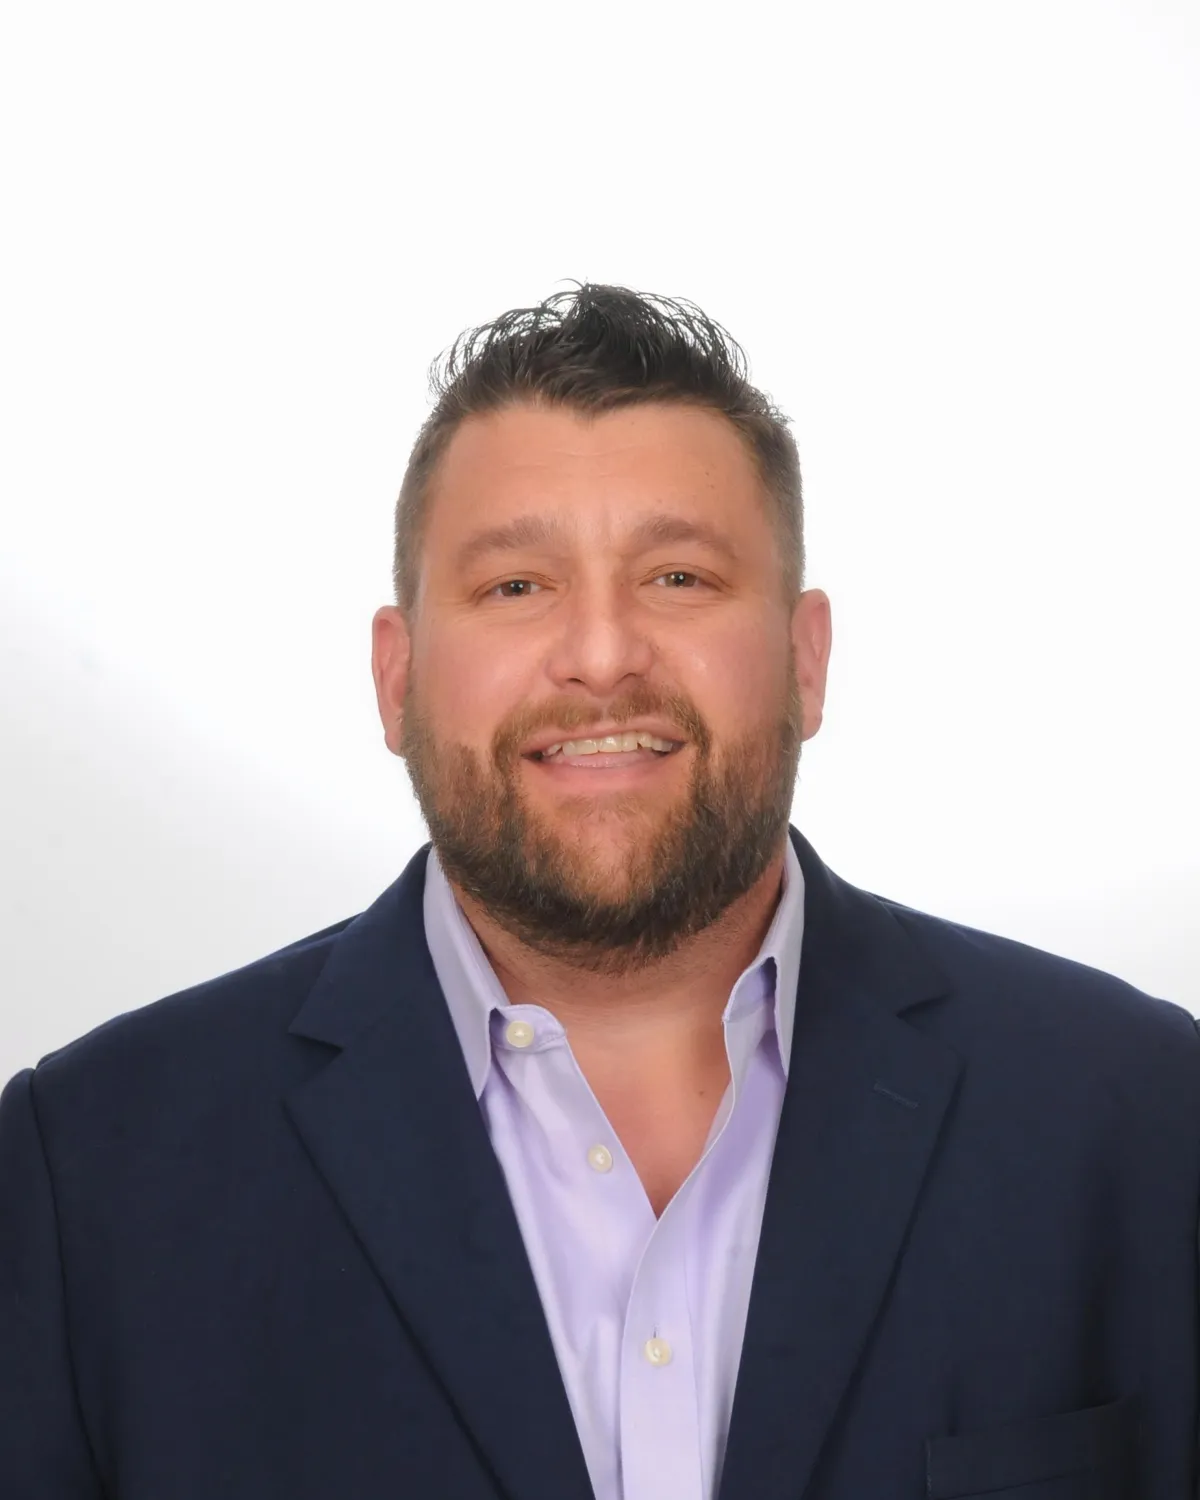
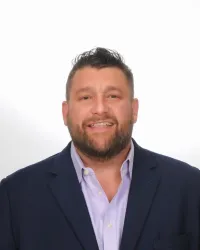
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
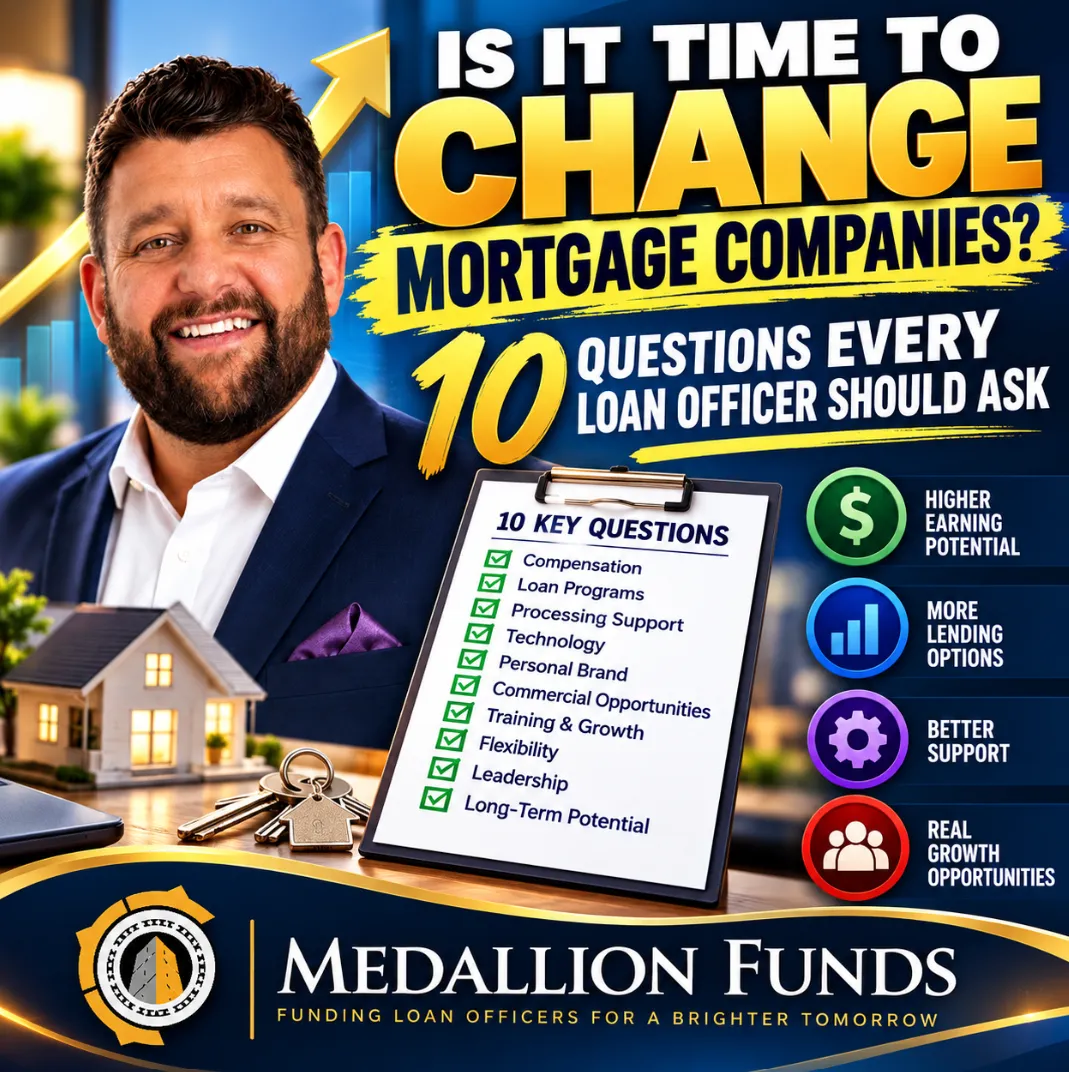
🚀 Is It Time to Change Mortgage Companies? 10 Questions Every Loan Officer Should Ask 🏡
🚀 Is It Time to Change Mortgage Companies? 10 Questions Every Loan Officer Should Ask 🏡
💰 Thinking About Switching Mortgage Companies? 10 Questions That Could Transform Your Loan Officer Career 🔥
________________________________________________________________________________
Is It Time to Change Mortgage Companies? 10 Questions Every Loan Officer Should Ask
By Bill Rapp Jr. | Director of Capital Advisory | Medallion Funds
Are you working harder than ever as a mortgage loan officer but wondering whether your current company is helping you reach your full potential?
Maybe your compensation isn't competitive. Perhaps your lender options are limited, your processing department is overwhelmed, or you're spending more time managing operational problems than generating new business.
Or maybe you've simply outgrown your current mortgage company.
Choosing the right mortgage company can be one of the most important business decisions a loan officer makes.
Whether you're working for a bank, retail mortgage lender, correspondent lender, or independent mortgage brokerage, the platform you choose directly influences your earning potential, client experience, product availability, and long-term growth.
At Medallion Funds, we believe successful loan officers need more than a place to originate loans. They need competitive compensation, meaningful operational support, strong lender relationships, and the freedom to build a sustainable business.
Before making your next career move, ask yourself these 10 questions.
1. Is My Mortgage Loan Officer Compensation Competitive?
Compensation is often the first reason loan officers consider changing mortgage companies.
But the highest advertised commission split doesn't necessarily translate into the highest take-home income.
Evaluate your total compensation structure, including commission splits, basis-point payouts, transaction fees, technology costs, marketing expenses, and other applicable deductions.
Consider this example:
Compensation factor | Company A | Company B |
Annual funded volume | $12 million | $12 million |
Illustrative gross production compensation | 100 bps | 100 bps |
Illustrative LO payout | 50% | 65% |
Annual LO compensation | $60,000 | $78,000 |
Hypothetical illustration only. Actual compensation depends on company policies, loan economics, applicable law, fees, and individual agreements. Not a Medallion Funds compensation quote.
That's an $18,000 difference before considering additional expenses.
Ask yourself: Am I evaluating the complete economics of my compensation, or only the advertised split?
2. Does My Company Offer Enough Mortgage Loan Programs?
One of the biggest frustrations for productive mortgage loan officers is having to turn away borrowers because their company lacks the appropriate lending program.
Today's borrowers have increasingly diverse financial profiles.
A competitive mortgage brokerage should provide access to a broad range of financing options, potentially including:
·Conventional, FHA, VA, and USDA loans
·Jumbo mortgage programs
·Doctor and dentist mortgage loans
·Non-QM and bank statement mortgages
·DSCR investor loans
·Asset-utilization mortgage programs
·HELOC and renovation financing
·Commercial real estate and SBA financing through appropriate lending channels
Product availability, eligibility, and licensing vary.
A broader lender network may allow you to serve more borrowers without sending viable opportunities to competitors.
Ask yourself: How many qualified borrowers have I lost because my current company didn't offer the right financing solution?
3. Am I Getting the Processing and Operational Support I Need?
Your income depends on closing loans, not chasing conditions all day.
A strong mortgage company should provide reliable processing, responsive communication, clearly defined responsibilities, and a consistent closing process.
When evaluating a potential new mortgage brokerage, ask about:
·In-house versus outsourced processing
·Processor workloads and escalation procedures
·Underwriting communication
·Average turn times by loan type
·Closing coordination and post-closing support
A better-supported loan officer can devote more time to prospecting, developing referral relationships, and serving clients.
Ask yourself: Is my company helping me originate more loans, or forcing me to manage every detail myself?
4. Is My Mortgage Technology Helping or Hurting My Productivity?
Technology should simplify mortgage origination, not complicate it.
Modern loan officers need efficient systems for borrower communication, document collection, pipeline tracking, and referral partner management.
Look for a platform that includes a customer relationship management system (CRM), loan origination tools, secure document management, automated follow-up, and marketing capabilities.
Medallion Funds emphasizes technology and CRM resources as part of its loan officer platform.
Ask yourself: Does my current technology make me more productive, or am I losing valuable time to disconnected systems?
5. Does My Company Help Me Build My Personal Brand?
Successful mortgage loan officers don't simply originate transactions. They build relationships and reputations that generate repeat business.
Your mortgage company should support your ability to establish a recognizable professional brand.
That can include social media marketing, educational video content, referral partner outreach, digital lead nurturing, and co-marketing opportunities that comply with applicable advertising and referral rules.
A loan officer who builds a strong personal brand becomes less dependent on company-generated leads.
Ask yourself: Am I building a business that I control, or relying entirely on my company's marketing?
6. Can I Offer Both Residential and Commercial Financing Solutions?
This is an often-overlooked opportunity for mortgage professionals.
Imagine helping a self-employed borrower purchase a home today, then discovering that the same client needs financing to acquire an office building, purchase a medical practice property, or refinance an investment asset.
At many mortgage companies, those commercial financing opportunities are referred elsewhere.
Medallion Funds combines residential mortgage capabilities with access to commercial real estate financing resources.
For appropriately qualified opportunities, this creates the potential to develop relationships with investors, business owners, doctors, dentists, and commercial property owners.
Commercial transactions require different underwriting, licensing considerations, and compensation arrangements.
Ask yourself: Am I maximizing the long-term value of my client relationships, or missing opportunities beyond residential mortgages?
7. Does My Company Provide Training and Professional Development?
Mortgage guidelines, investor overlays, loan products, and market conditions continually evolve.
Loan officers need ongoing education to remain competitive.
The right mortgage brokerage should help you understand complex lending programs, strengthen borrower qualification skills, develop referral networks, and improve your business development strategy.
Training is particularly valuable when transitioning from retail lending to the mortgage broker model.
Ask yourself: Is my company investing in my professional development, or am I expected to figure everything out on my own?
8. Do I Have the Flexibility to Run My Business Effectively?
Experienced mortgage loan officers often value independence.
They want the ability to build their own referral relationships, manage their pipeline, market their services, and pursue the borrower segments that fit their expertise.
However, flexibility must operate within company policies, licensing requirements, investor guidelines, and applicable regulations.
A strong brokerage balances entrepreneurial opportunity with effective compliance oversight.
Ask yourself: Does my current mortgage company support my business strategy, or unnecessarily restrict how I grow?
9. Is Leadership Accessible and Invested in My Success?
Company culture can have a significant impact on a loan officer's long-term satisfaction.
When a complicated transaction arises, can you reach someone who understands lending and can help solve the problem?
When you identify a new market opportunity, does leadership listen?
When business slows, does the organization offer practical support?
At Medallion Funds, our philosophy is centered on helping mortgage professionals build sustainable businesses through lending resources, operational support, and relationships.
Ask yourself: Am I treated like a valued business partner or simply another production number?
10. Where Will I Be in Three to Five Years If I Stay?
This may be the most important question of all.
Imagine staying with your current mortgage company for another three years.
Will you have increased your annual funded volume? Developed stronger referral relationships? Expanded your product knowledge? Built a recognizable brand? Improved your earnings and operational efficiency?
If you cannot identify a realistic path toward those outcomes, it may be time to evaluate other mortgage companies.
Changing mortgage companies should not be an emotional reaction to a difficult month.
It should be a deliberate business decision based on your professional goals and the resources available to help you achieve them.
Ask yourself: Is my current company the right platform for the business I want to build?
When Should a Loan Officer Consider Changing Mortgage Companies?
Not every frustration means you should immediately leave.
However, several persistent warning signs deserve attention: limited loan products, uncompetitive net compensation, recurring processing problems, inadequate technology, weak leadership communication, and a lack of professional growth opportunities.
Before changing companies, compare written compensation agreements, licensing requirements, transition procedures, pipeline treatment, client communication responsibilities, and any contractual restrictions.
The goal isn't simply to find a new company.
The goal is to find a better platform for your long-term success.
Why Consider Medallion Funds?
Medallion Funds offers mortgage professionals an opportunity to explore a brokerage environment focused on lending flexibility, business development, and operational support.
Our platform includes access to multiple mortgage product categories, CRM resources, in-house processing capabilities, and commercial financing opportunities.
For experienced, self-generating loan officers, the ability to combine residential and commercial lending relationships can provide a meaningful point of differentiation.
Individual compensation terms, support arrangements, product access, and eligibility should always be confirmed during the recruiting process.
Frequently Asked Questions
Is it worth switching mortgage companies for a higher commission split?
Possibly, but compare net earnings after all fees and expenses. Also evaluate operational support, lender access, pricing, and closing performance.
Is a mortgage broker better than a retail mortgage lender?
Neither model is automatically better. A mortgage brokerage may offer broader lender access and more flexibility, while retail lenders may offer different operational resources or lead-generation structures.
Can a loan officer move from a bank to a mortgage brokerage?
Yes, subject to applicable licensing, registration, employment, and transition requirements. State-licensed mortgage loan originators generally have different requirements from certain federally registered bank loan originators.
What happens to my pipeline when I change mortgage companies?
Pipeline treatment depends on employment agreements, company policies, borrower authorization, lender requirements, and applicable law. Review these details before resigning.
What should I ask a mortgage company before joining?
Request clear information about compensation, lender access, processing, technology, marketing, compliance, leadership, and long-term growth opportunities.
Final Thoughts: Your Mortgage Career Deserves the Right Platform
You work hard to build relationships, earn referrals, qualify borrowers, and close loans.
Your mortgage company should provide the resources and support necessary to help that effort translate into sustainable success.
If you've been questioning whether your current mortgage company is still the right fit, consider having a confidential conversation about your options.
Ready to Explore Your Next Opportunity?
I'm Bill Rapp Jr., Director of Capital Advisory with Medallion Funds.
If you're an experienced mortgage loan officer considering a change, I'd welcome a conversation about your goals, the brokerage model, and whether our platform could be a good fit.
Connect with Bill Rapp
·Website: MedallionFunds.com
·Email: [email protected]
·Schedule: Book a conversation
·YouTube: Medallion Funds Mortgage Channel
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok