Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
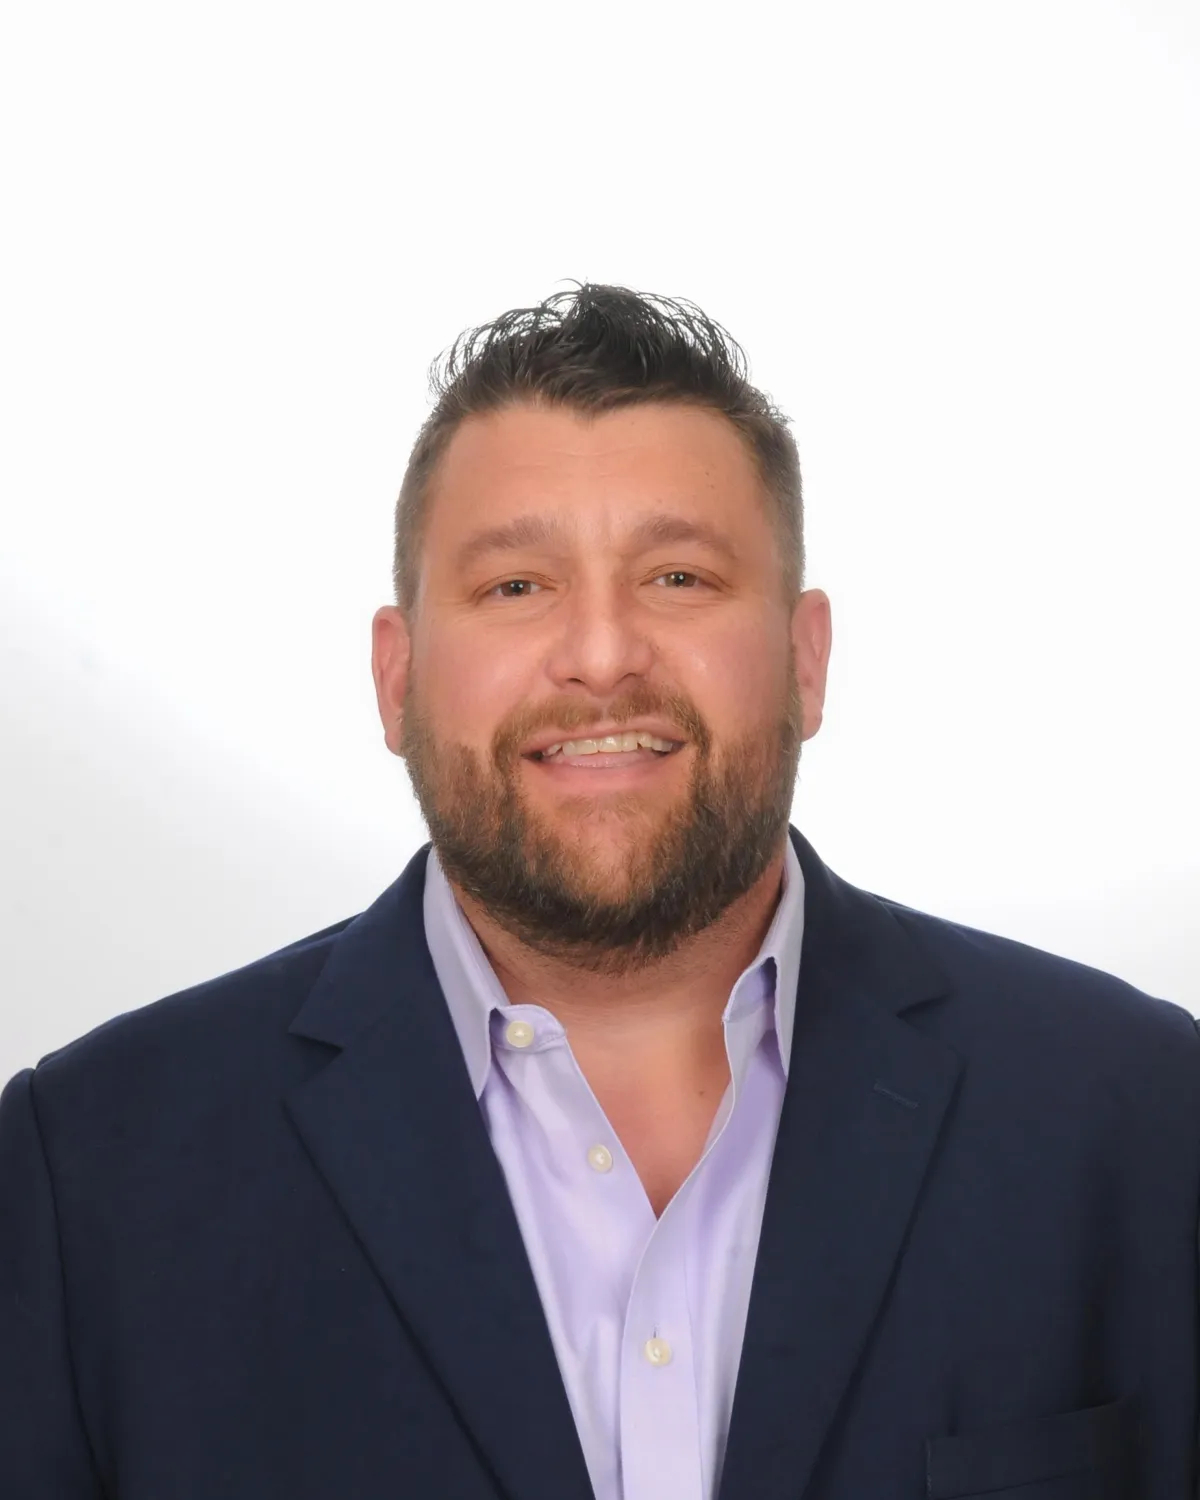
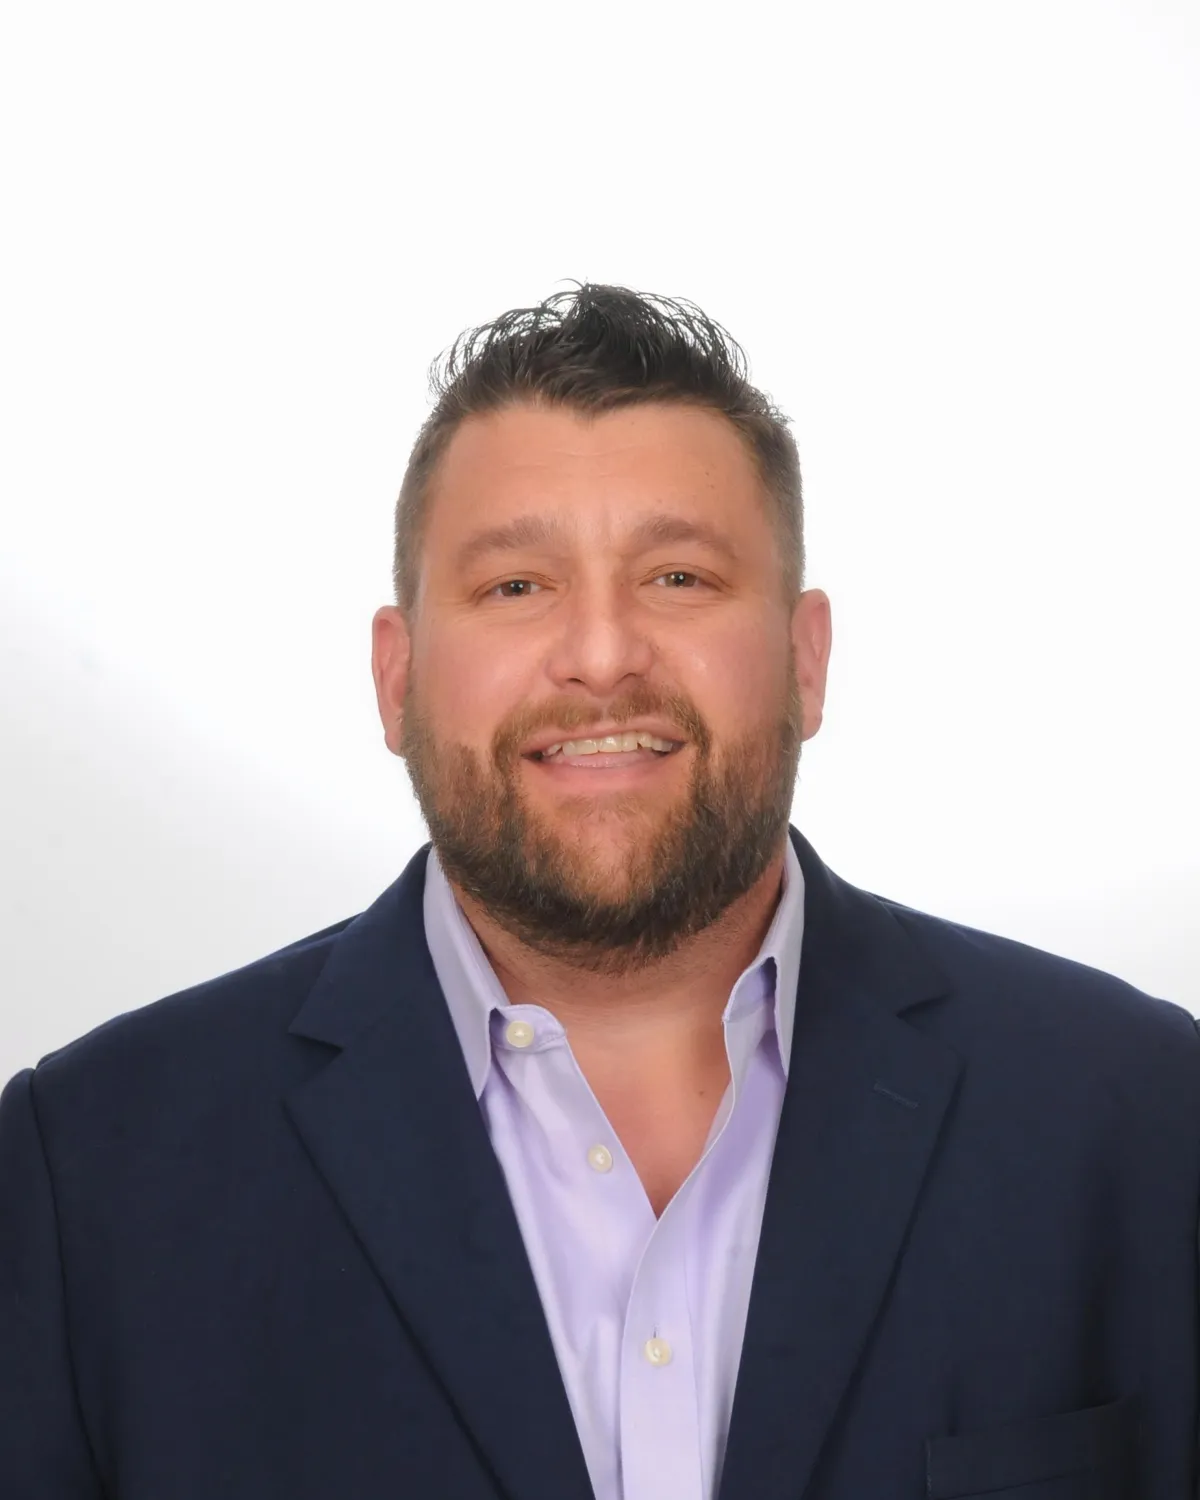
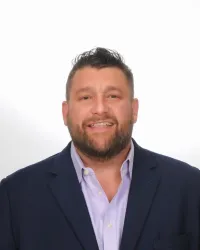
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
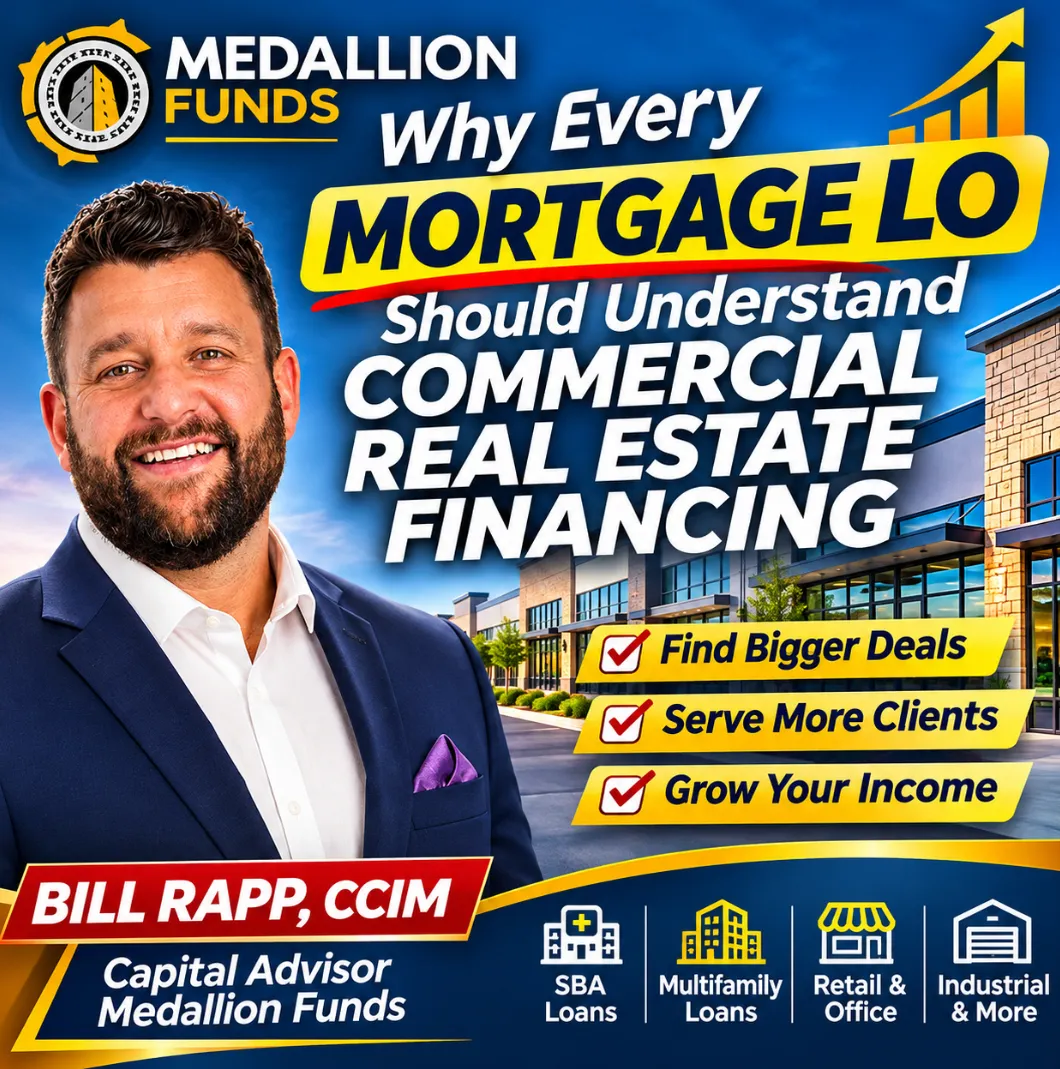
🚀 Why Mortgage Loan Officers Should Learn Commercial Lending 💰
🚀 Why Mortgage Loan Officers Should Learn Commercial Lending 💰
🏢 Commercial Lending: The Opportunity Mortgage LOs Overlook 🚀
__________________________________________________________________________
Why Every Mortgage LO Should Understand Commercial Real Estate Financing
Commercial real estate financing for mortgage loan officers is more than an additional lending specialty. It is an opportunity to expand client relationships, understand more financing solutions, and potentially develop new revenue streams.
Most residential mortgage loan officers spend their careers helping clients purchase homes, refinance mortgages, or access home equity. Those services are essential, but they represent only part of the lending market.
What happens when your client wants to purchase a medical office building, finance a warehouse, refinance an apartment complex, or acquire a retail center?
If you only understand residential mortgages, you may not recognize the financing opportunity.
That is why every mortgage loan officer should develop a working knowledge of commercial real estate lending.
At Medallion Funds, we believe mortgage professionals can create stronger businesses by understanding both residential and commercial financing.
1. Commercial Lending Expands Your Mortgage Business
Traditional residential mortgage lending focuses primarily on individual borrowers and residential properties.
Commercial real estate financing introduces an entirely different set of opportunities.
Commercial financing may include:
·Office buildings and medical facilities
·Retail shopping centers and restaurants
·Industrial warehouses and flex properties
·Apartment buildings and multifamily investments
·Owner-occupied business properties
·Mixed-use developments
·Commercial construction and renovation projects
·Investment property acquisitions and refinancing
For mortgage loan officers, understanding these transactions creates opportunities to serve clients beyond their primary residences.
The same person purchasing a home today could become a commercial property investor or business owner tomorrow.
Developing commercial mortgage knowledge helps you recognize those opportunities before the client looks elsewhere.
2. Your Existing Clients May Already Need Commercial Loans
One of the biggest misconceptions about commercial mortgage lending is that you need an entirely new client base.
In reality, commercial financing opportunities may already exist within your residential mortgage relationships.
Consider these examples.
Doctors and Dentists
A physician purchasing a primary residence may eventually want to acquire a medical office building.
A dentist might decide to purchase the building currently occupied by their practice rather than continue leasing.
Depending on eligibility, SBA financing or conventional owner-occupied commercial financing may provide solutions.
Small Business Owners
Your self-employed mortgage clients may also own restaurants, service companies, retail businesses, or industrial operations.
These clients may need financing to purchase business real estate, expand operations, or refinance existing commercial debt.
Real Estate Investors
A client who begins with one rental property may eventually acquire a portfolio of single-family rentals or a five-unit apartment building.
As their investments expand, their financing requirements may shift from conventional residential loans to DSCR, portfolio, or commercial mortgage programs.
High-Net-Worth Borrowers
Affluent residential mortgage clients may also own investment properties, development projects, or commercial buildings.
Understanding commercial financing allows loan officers to identify these potential needs and coordinate with qualified lending specialists.
The opportunity is not necessarily finding more clients. It may be identifying additional financing needs among the clients you already know.
3. Understand the Five Major Commercial Financing Options
Mortgage loan officers do not need to become commercial underwriting experts overnight.
However, they should understand the primary commercial lending categories.
SBA 7(a) and SBA 504 Loans
SBA financing can help eligible small businesses purchase or improve owner-occupied commercial real estate.
SBA 7(a) loans may support real estate, equipment, working capital, and qualifying business acquisitions, subject to program rules.
SBA 504 financing is commonly used for qualifying fixed assets, including owner-occupied buildings and major equipment.
These programs can be particularly relevant to doctors, dentists, manufacturers, and business owners.
Conventional Commercial Mortgages
Banks, credit unions, and other lenders provide commercial mortgages for qualifying income-producing and owner-occupied properties.
Underwriting typically considers property cash flow, borrower financial strength, collateral value, liquidity, and repayment capacity.
DSCR and Investment Property Loans
Debt Service Coverage Ratio, or DSCR, measures how effectively qualifying property income covers required debt payments.
For commercial real estate, lenders often calculate DSCR using net operating income divided by annual debt service.
Some residential investment property DSCR programs use different qualifying calculations.
Understanding the distinction helps mortgage loan officers recognize investor financing opportunities.
Commercial Bridge Loans
Bridge loans provide shorter-term financing for certain acquisitions, renovations, lease-up strategies, or transitional properties.
They may offer flexibility when conventional financing is unavailable, but borrowers must understand the higher costs, maturity dates, and refinancing risks that can accompany these loans.
Commercial Construction Loans
Commercial construction financing can support eligible ground-up development and major renovation projects.
These loans commonly involve construction budgets, project feasibility, draw schedules, borrower equity, and completion requirements.
Knowing which financing category may fit a client's transaction is often the first step toward creating value.
4. Commercial Loan Underwriting Is Different From Residential Lending
Residential mortgage underwriting typically focuses heavily on the borrower's income, credit, assets, debt-to-income ratio, and property value.
Commercial underwriting often adds another dimension: the property's ability to generate sufficient cash flow.
Important commercial lending concepts include:
Loan-to-Value (LTV): The loan amount compared with the property's appraised or accepted value.
Debt Service Coverage Ratio (DSCR): The relationship between qualifying property income and required debt payments.
Net Operating Income (NOI): Property operating income after ordinary operating expenses, but before debt service and certain other items.
Debt Yield: NOI divided by the loan amount, expressed as a percentage.
Loan Term vs. Amortization: A commercial loan may amortize over 25 years but mature in five years, leaving a substantial balloon payment.
Commercial lenders may also evaluate tenant quality, lease expiration schedules, property condition, environmental risks, sponsor experience, and liquidity.
Understanding these fundamentals helps mortgage loan officers ask better questions and refer commercial opportunities appropriately.
5. Commercial Financing Can Strengthen Referral Relationships
Real estate agents, CPAs, financial advisors, attorneys, and business owners frequently encounter commercial financing questions.
A mortgage loan officer who understands both residential and commercial lending can become a more useful referral resource.
For example:
·A residential real estate agent may have a client buying a small apartment building.
·A CPA may work with a business owner considering a commercial property acquisition.
·A financial advisor may have an investor seeking to refinance commercial assets.
·A builder may need a construction financing resource.
·A dentist may need financing for a new practice location.
When you understand the financing possibilities, you can help connect these professionals with the right resources.
This can support deeper, more durable professional relationships.
6. Commercial Loans May Create Additional Income Opportunities
Commercial mortgages frequently involve larger loan balances than individual residential mortgages.
For example, consider a residential mortgage loan of $400,000 compared with a commercial acquisition loan of $2,000,000.
The commercial loan is five times larger.
However, a larger loan does not automatically mean five times the compensation.
Commercial financing compensation varies based on the lender, transaction structure, brokerage agreement, licensing requirements, and applicable law.
Some mortgage professionals may originate eligible commercial loans directly. Others may participate through an authorized referral or collaboration arrangement.
The appropriate structure depends on the professional's experience, licensing, company policies, and the transaction.
The real opportunity is developing another potential business channel while maintaining appropriate compliance and client service.
7. Real-World Example: A Dentist Who Wants to Own the Building
Imagine you are a residential mortgage loan officer who recently helped a dentist purchase a $750,000 home.
Six months later, the dentist mentions paying $12,000 per month to lease office space.
The dentist is considering purchasing a $2 million medical office property.
A residential-only loan officer might simply recommend contacting a local bank.
But an LO familiar with commercial financing knows to ask several important questions:
·Will the dental practice occupy the required percentage of the property?
·What is the business's operating history and cash flow?
·How much equity is available?
·Would SBA 7(a), SBA 504, or conventional financing be appropriate?
·Does the dentist plan to occupy the property long term?
The answers help determine which financing programs may be worth evaluating.
Instead of losing the opportunity, the loan officer can introduce an appropriate commercial financing specialist or participate where authorized.
The client receives more comprehensive guidance, and the loan officer strengthens an existing relationship.
8. How Residential Mortgage LOs Can Start Learning Commercial Lending
You do not need to abandon residential mortgages to explore commercial financing.
Start with a practical approach.
Step 1: Learn the terminology. Understand NOI, DSCR, LTV, debt yield, balloon payments, and amortization.
Step 2: Identify your existing client opportunities. Look for business owners, doctors, dentists, and real estate investors.
Step 3: Understand the major programs. Become familiar with SBA, conventional commercial, DSCR, bridge, and construction financing.
Step 4: Build commercial lending relationships. Work with experienced capital advisors and commercial lending specialists.
Step 5: Understand compliance and compensation. Confirm that your licensing, company policies, and applicable laws permit your intended role.
Step 6: Expand gradually. Begin by identifying potential transactions and helping clients reach qualified professionals.
The objective is not to become an expert in every commercial property type.
It is to become knowledgeable enough to recognize opportunities and guide clients toward appropriate financing solutions.
9. Why Medallion Funds Is Relevant to Mortgage Loan Officers
At Medallion Funds, we work across residential and commercial financing solutions.
Our approach emphasizes lender relationships, financing alternatives, underwriting knowledge, and collaboration.
Mortgage professionals exploring commercial lending may benefit from learning how to evaluate transactions involving:
·Residential investment properties
·Small multifamily buildings
·Owner-occupied commercial real estate
·Medical and dental offices
·Retail and industrial properties
·Commercial acquisitions and refinances
·Business-purpose and construction financing
Commercial lending is not a substitute for a successful residential mortgage business.
It is a complementary area of expertise that may help mortgage professionals serve a broader range of clients.
Final Thoughts: Become More Than a Residential Mortgage Resource
Mortgage loan officers operate in a competitive environment.
Interest rates change. Housing markets fluctuate. Borrower demand shifts.
Developing commercial real estate financing knowledge can help mortgage professionals diversify their expertise, deepen referral relationships, and identify additional business opportunities.
You do not need to originate every commercial loan yourself.
You need to understand enough to recognize the opportunity and know whom to involve.
The mortgage professionals who understand both residential and commercial financing may be better positioned to serve clients throughout their real estate investment journey.
Connect With Bill Rapp, CCIM
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds.
If you're a mortgage loan officer interested in learning more about commercial lending opportunities, lender resources, or expanding your mortgage business, let's connect.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok