Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
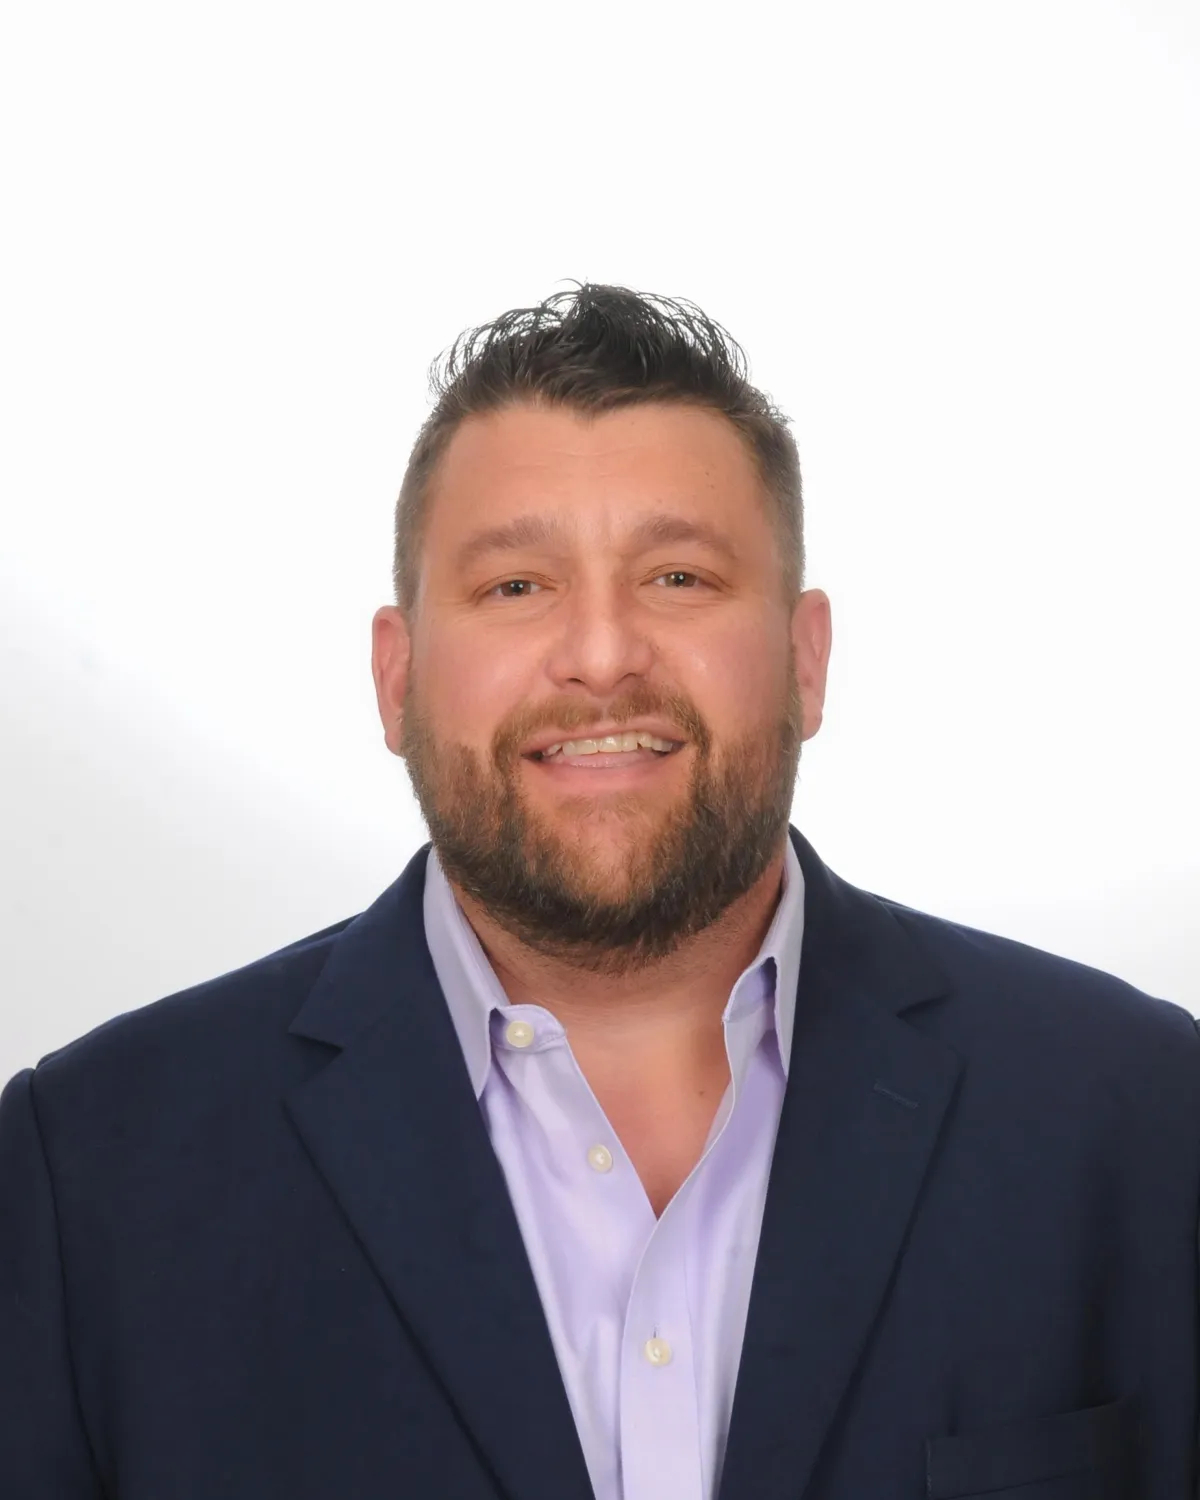
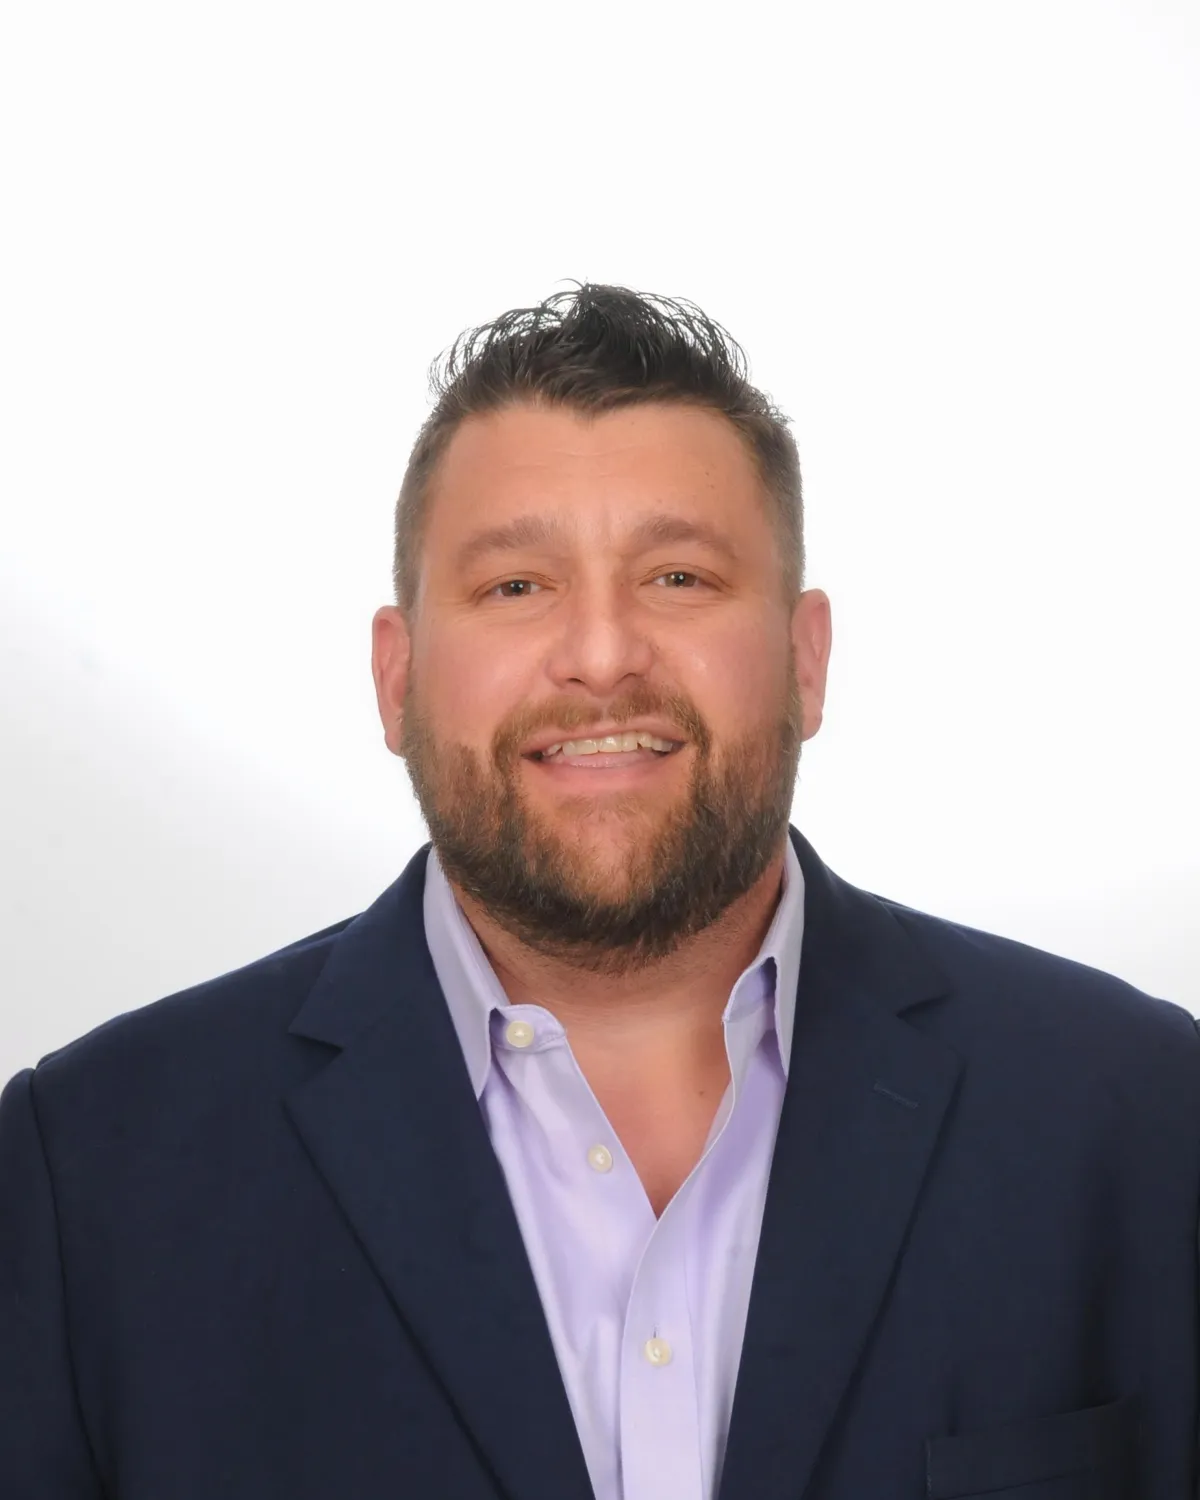
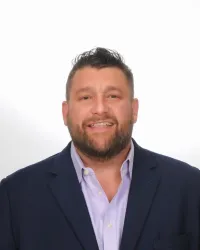
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
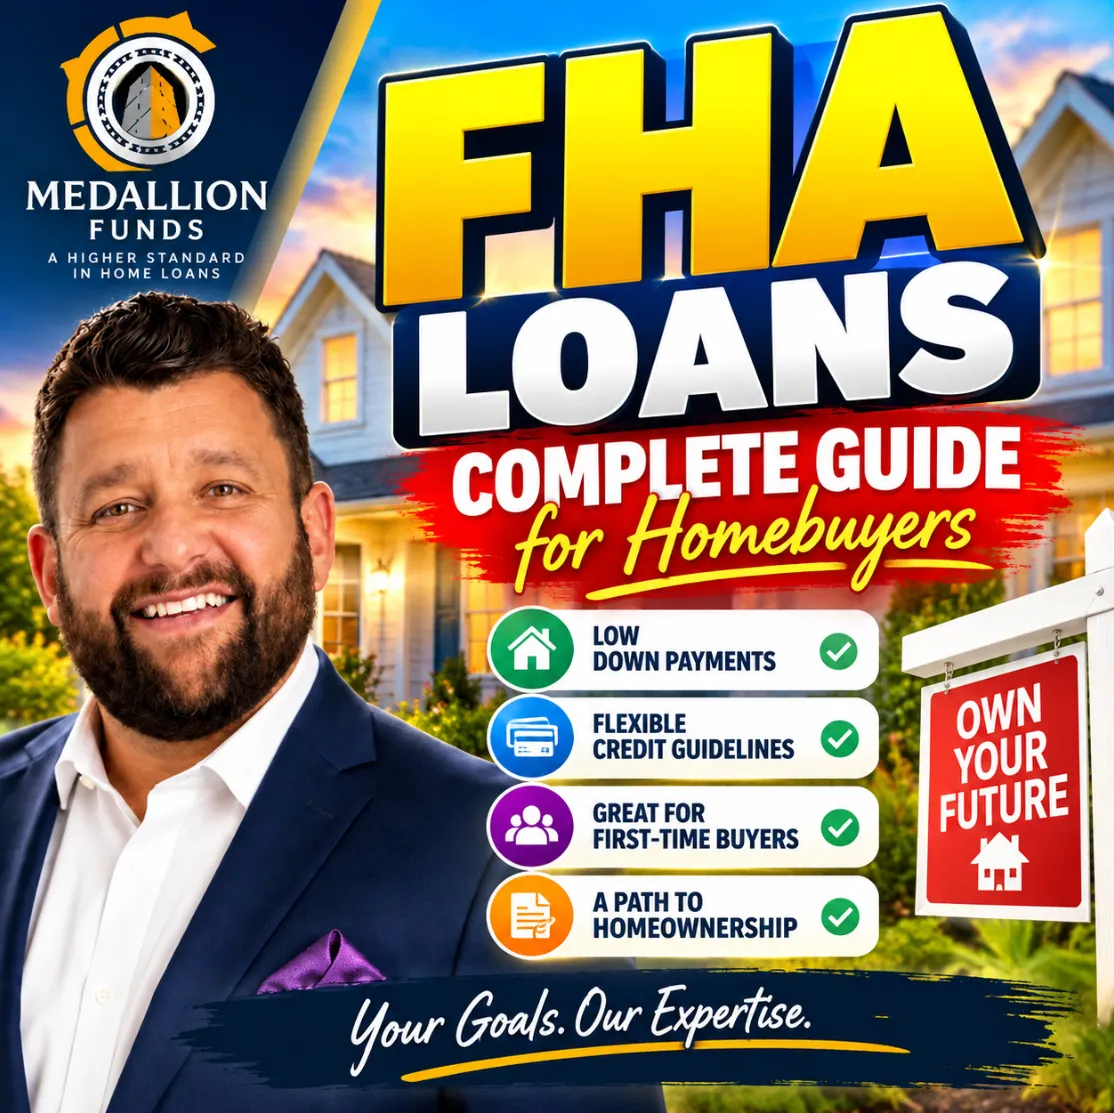
🏡 FHA Loans: The Complete Homebuyer’s Guide to Lower Down Payments & Flexible Qualification 🔑
🏡 FHA Loans: The Complete Homebuyer’s Guide to Lower Down Payments & Flexible Qualification 🔑
💰 FHA Loan Guide 2026: How to Buy a Home With as Little as 3.5% Down 🏠
FHA Loans: Complete Guide for Homebuyers
Buying a home can feel financially out of reach when you are worried about the down payment, credit requirements, closing costs, and monthly payment. An FHA loan can provide another path to homeownership for qualified buyers—particularly buyers who have limited savings or credit profiles that may not fit conventional mortgage guidelines.
FHA loans are mortgages made by approved lenders and insured by the Federal Housing Administration, which is part of HUD. Because FHA provides mortgage insurance protecting the lender against certain losses, lenders can offer financing under FHA guidelines that may be more flexible than some conventional programs.
For buyers considering an FHA mortgage in 2026, the important question isn't simply, "Can I qualify?" It is:
"Does an FHA loan make sense compared with the other mortgage options available to me?"
That's where working with a mortgage broker can be valuable.
What Is an FHA Loan?
An FHA loan is a government-insured mortgage designed to expand access to homeownership. FHA does not generally lend the money directly to the homebuyer. Instead, borrowers obtain financing through an FHA-approved mortgage lender, and FHA insures the loan.
One of the program's best-known features is the ability for qualifying borrowers to purchase a home with a relatively small down payment.
A borrower meeting applicable FHA requirements may be eligible for 3.5% down financing with a credit score of at least 580. FHA guidelines also provide a framework for borrowers with scores between 500 and 579 at a lower maximum loan-to-value, effectively requiring at least 10% down. Actual lender requirements can be more restrictive. HUD Archives
For example, on a $350,000 purchase, a 3.5% down payment would equal:
$350,000 × 3.5% = $12,250
That does not mean $12,250 is your entire cash requirement. Buyers also need to account for closing costs, prepaid expenses, reserves when applicable, and other transaction expenses.
Why FHA Loans Appeal to First-Time Homebuyers
FHA financing is often associated with first-time homebuyers, but you do not have to be a first-time buyer to use an FHA loan.
The program can be particularly attractive to borrowers who:
·Have limited funds available for a down payment
·Have less-than-perfect credit
·Want more flexible underwriting than a particular conventional program provides
·Receive eligible gift funds or down-payment assistance
·Want to purchase an eligible owner-occupied property
The right mortgage, however, depends on the entire financial picture rather than one feature such as the minimum down payment.
FHA Credit Score Requirements
Credit is one of the biggest areas of confusion surrounding FHA loans.
FHA program guidelines and a lender's underwriting requirements aren't necessarily identical. A lender may impose requirements beyond FHA's minimum standards.
Credit qualification also involves considerably more than your numerical credit score. Mortgage underwriting can consider your payment history, outstanding debts, collections, bankruptcies or foreclosures when applicable, income, assets, and overall risk profile.
That's why someone shouldn't automatically assume that a previous credit problem eliminates the possibility of homeownership.
FHA Down Payment Requirements
The 3.5% minimum down payment is one of FHA financing's most recognizable benefits.
Your down payment doesn't necessarily have to come exclusively from money you've personally accumulated. Depending on the circumstances and applicable FHA requirements, eligible sources can include personal savings, qualifying gifts and certain down-payment-assistance programs.
This can make FHA financing particularly useful when a buyer has sufficient income to support a mortgage but hasn't accumulated a large down payment.
FHA Mortgage Insurance
The tradeoff for FHA's high-leverage financing is mortgage insurance premium (MIP).
Most FHA single-family mortgages require an upfront mortgage insurance premium, and FHA's published premium schedule identifies UFMIP at 1.75% of the base loan amount for standard mortgages. HUD
Depending on the loan, borrowers can also have an annual MIP that is generally collected as part of the monthly mortgage payment.
This is an important reason to compare FHA and conventional financing rather than choosing a mortgage solely because FHA offers a smaller minimum down payment.
A conventional mortgage may potentially become more attractive for borrowers with strong credit, adequate cash and other qualifying characteristics.
What Properties Can You Buy With an FHA Loan?
FHA loans are designed primarily around owner-occupied housing rather than traditional investment-property financing.
Eligible properties can include certain:
Single-family homes, condominiums, manufactured homes and two-to-four-unit properties, subject to FHA and lender requirements.
The ability to finance a small multifamily property can be particularly interesting.
For example, a qualifying buyer could potentially purchase a duplex, triplex or fourplex, occupy one unit as a primary residence, and rent the remaining units, subject to applicable underwriting and FHA requirements.
That creates a potential bridge between homeownership and real estate investing.
FHA Appraisals Are Different
An FHA appraisal isn't simply about determining market value.
The property must also satisfy applicable FHA requirements. That means significant health, safety or property-condition issues can affect the transaction.
Buyers purchasing older or distressed homes should therefore understand the property's condition before assuming FHA financing will work.
There are also specialized FHA rehabilitation programs for certain situations, but those have their own requirements.
How Much Can You Borrow With an FHA Loan in 2026?
FHA loan limits vary by geographic area and property type.
For 2026, the national one-unit FHA loan-limit floor is $541,287, while the one-unit ceiling in high-cost areas is $1,249,125. Limits for two-, three- and four-unit properties are higher. HUD
Individual limits are established by county or metropolitan area, so borrowers should check the limit applying to the specific property rather than relying on a national number. HUD provides an official lookup tool for this purpose. ENTP HUD
FHA Loan vs. Conventional Loan
One of the most important steps for a homebuyer is comparing FHA financing against conventional financing.
Don't compare only the interest rate.
Instead, compare:
Down payment + interest rate + APR + mortgage insurance + closing costs + cash to close + monthly payment + long-term cost.
A borrower with limited savings or credit challenges might find FHA particularly useful. Another borrower with stronger credit and additional cash might find conventional financing more attractive.
There is no universal answer.
The appropriate structure depends on the borrower.
How Much Home Can You Actually Afford?
A mortgage pre-approval shouldn't simply answer:
"What is the maximum house price I qualify for?"
A better conversation is:
"What monthly housing payment fits comfortably into my financial plan?"
Your housing expense can include principal, interest, property taxes, homeowners insurance, mortgage insurance and, where applicable, HOA dues.
Two homes with identical $400,000 purchase prices can therefore have very different monthly ownership costs.
Property taxes, insurance premiums and HOA assessments can materially change affordability.
FHA Closing Costs
The down payment is only part of the cash needed to purchase a home.
Potential expenses can include lender charges, title and settlement expenses, appraisal fees, prepaid homeowners insurance, property-tax escrows and other transaction costs.
FHA rules also permit certain seller or interested-party contributions subject to program restrictions. Buyers should structure concessions carefully with their lender and real estate agent rather than assuming every cost can be shifted to the seller.
Get Pre-Approved Before Shopping
One of the best steps prospective FHA buyers can take is obtaining mortgage pre-approval before making offers.
A thorough pre-approval can help establish your approximate price range, estimated payment, required cash to close and potential financing structure.
It can also identify credit, income or documentation issues early enough to address them rather than discovering them after you are under contract.
Why Work With a Mortgage Broker?
A mortgage is more than an interest rate.
As a mortgage broker, Medallion Funds can help evaluate the borrower's broader financing situation and compare available mortgage strategies.
That means examining variables such as credit, income, down payment, property type, monthly-payment goals, mortgage insurance and closing costs before determining which available program appears to fit.
For some buyers, FHA financing may be an excellent solution.
For others, conventional, VA, USDA, jumbo or another mortgage structure may deserve consideration.
The objective should be to find financing that fits your circumstances—not force your circumstances into a particular loan product.
Ready to Explore Your FHA Loan Options?
If you're planning to buy a home, don't wait until you've found the property to start thinking about financing.
Start by understanding what you qualify for, what your estimated payment could be, how much cash you'll need, and which mortgage options are available to you.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok