Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
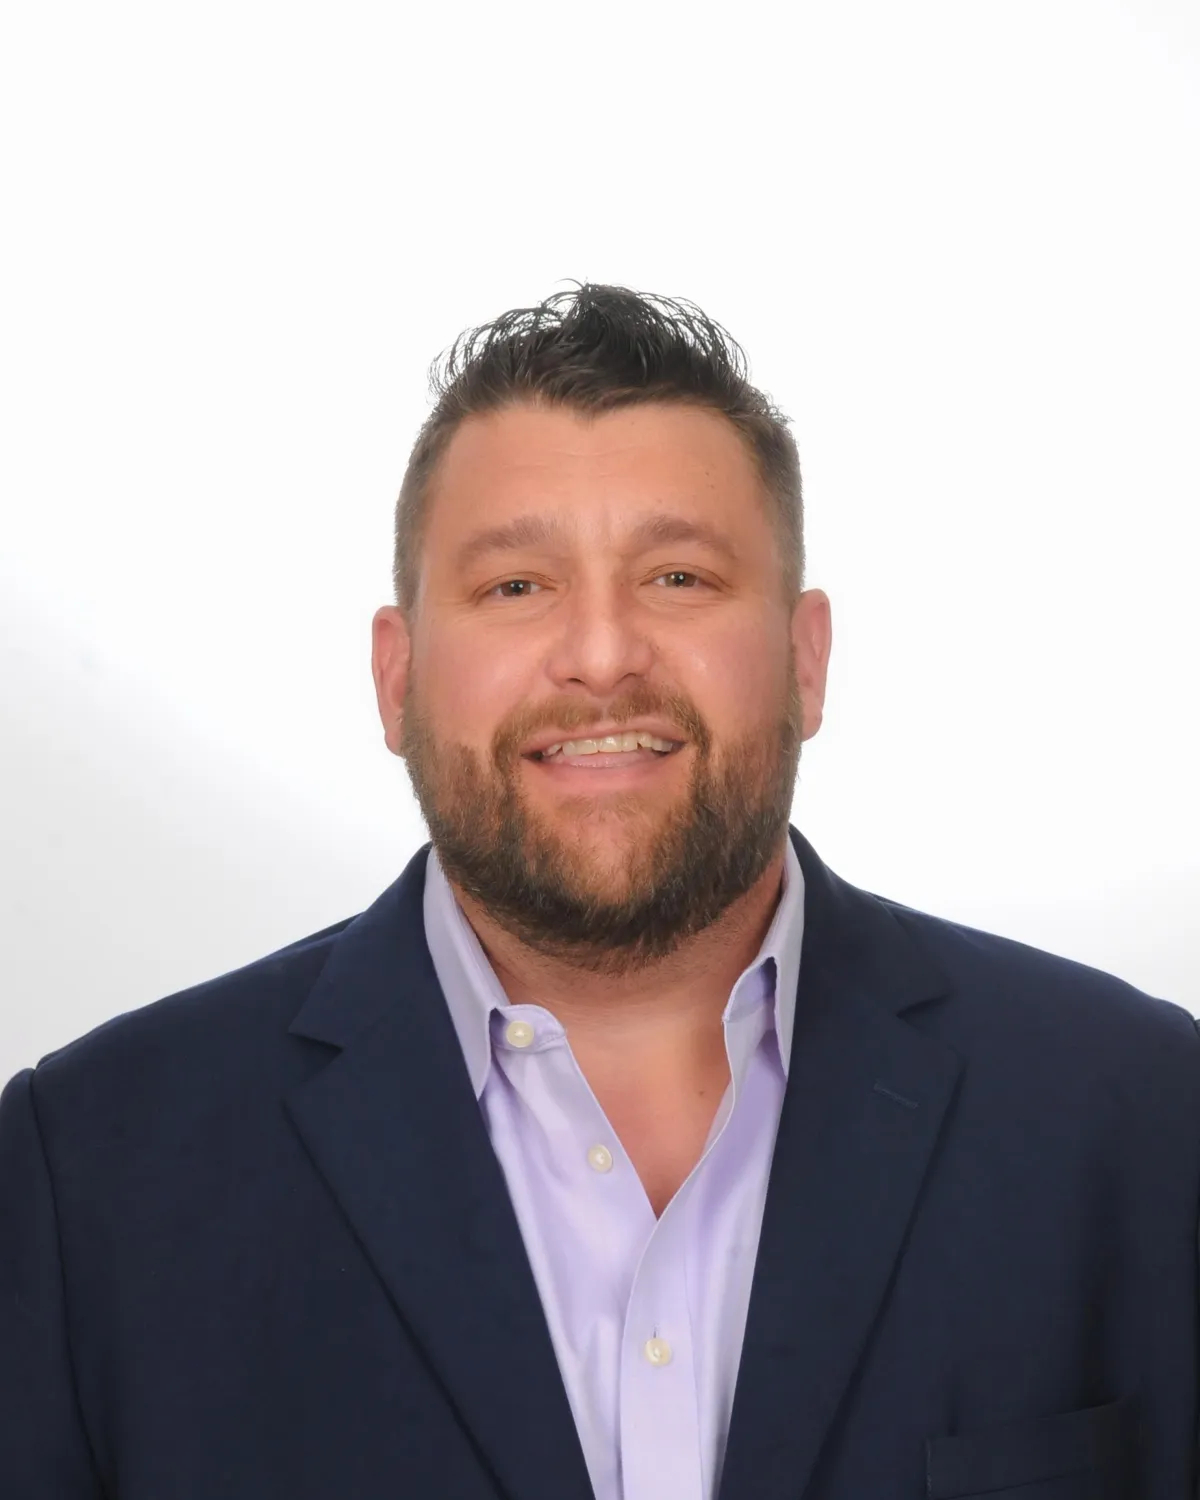
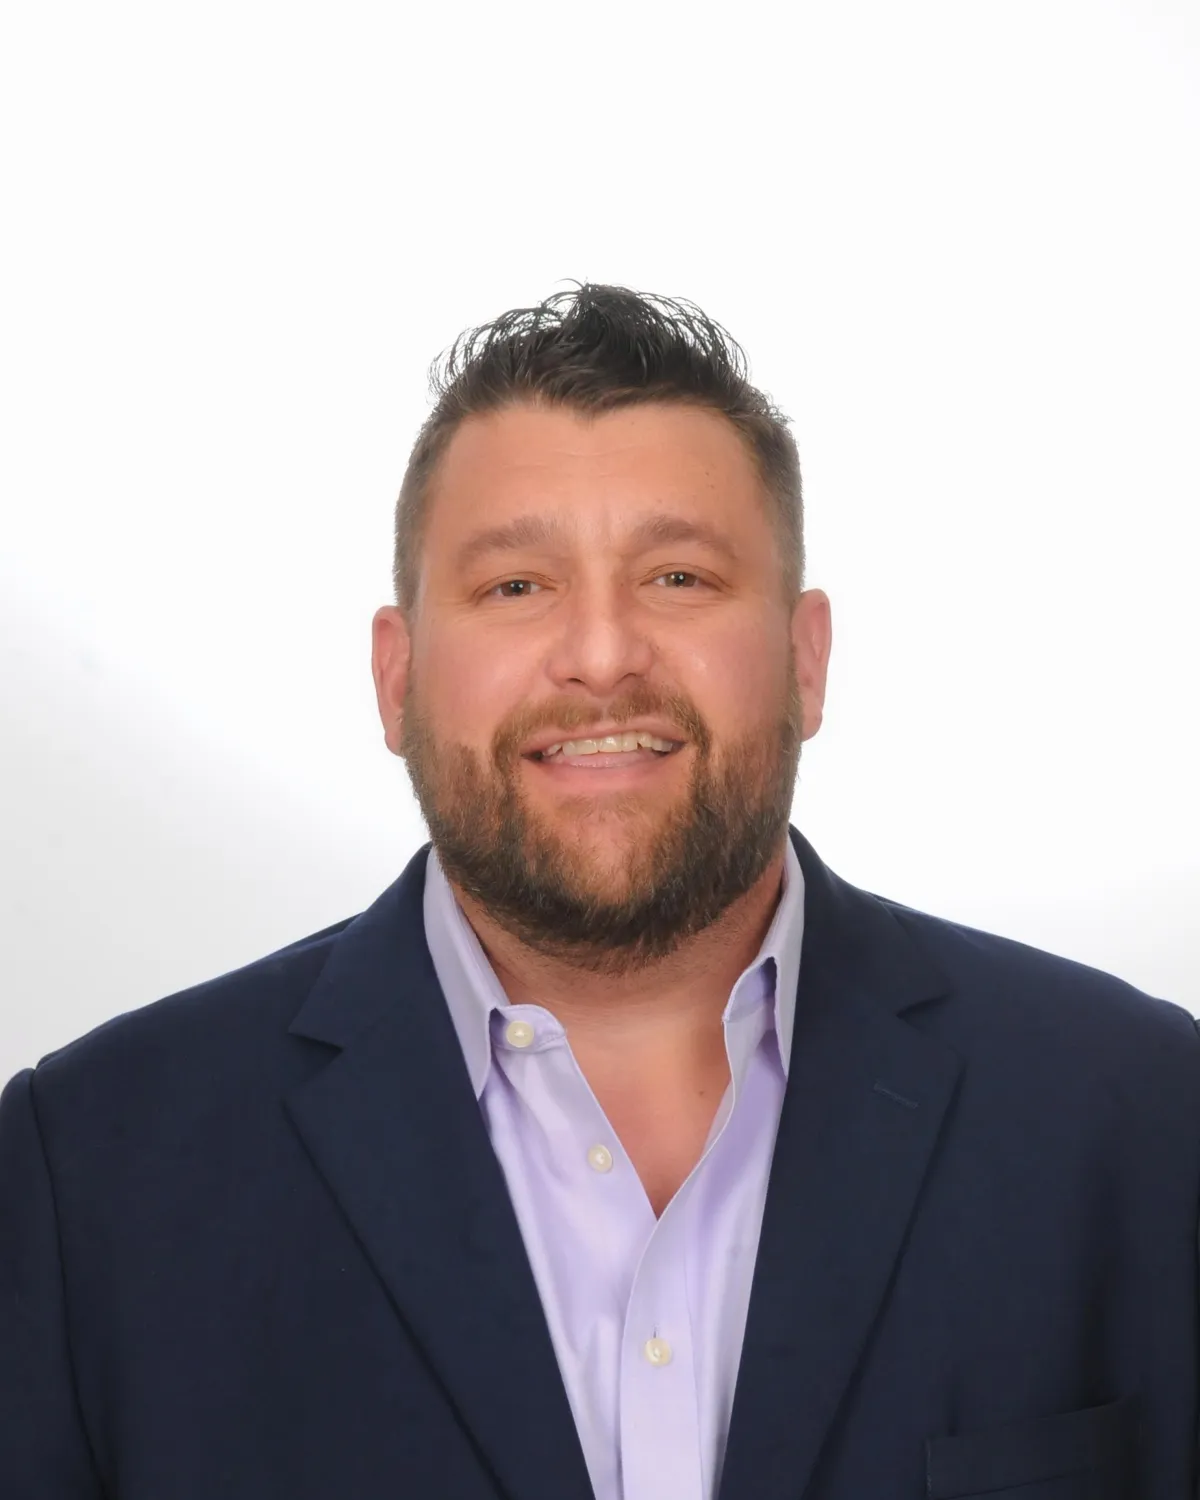
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
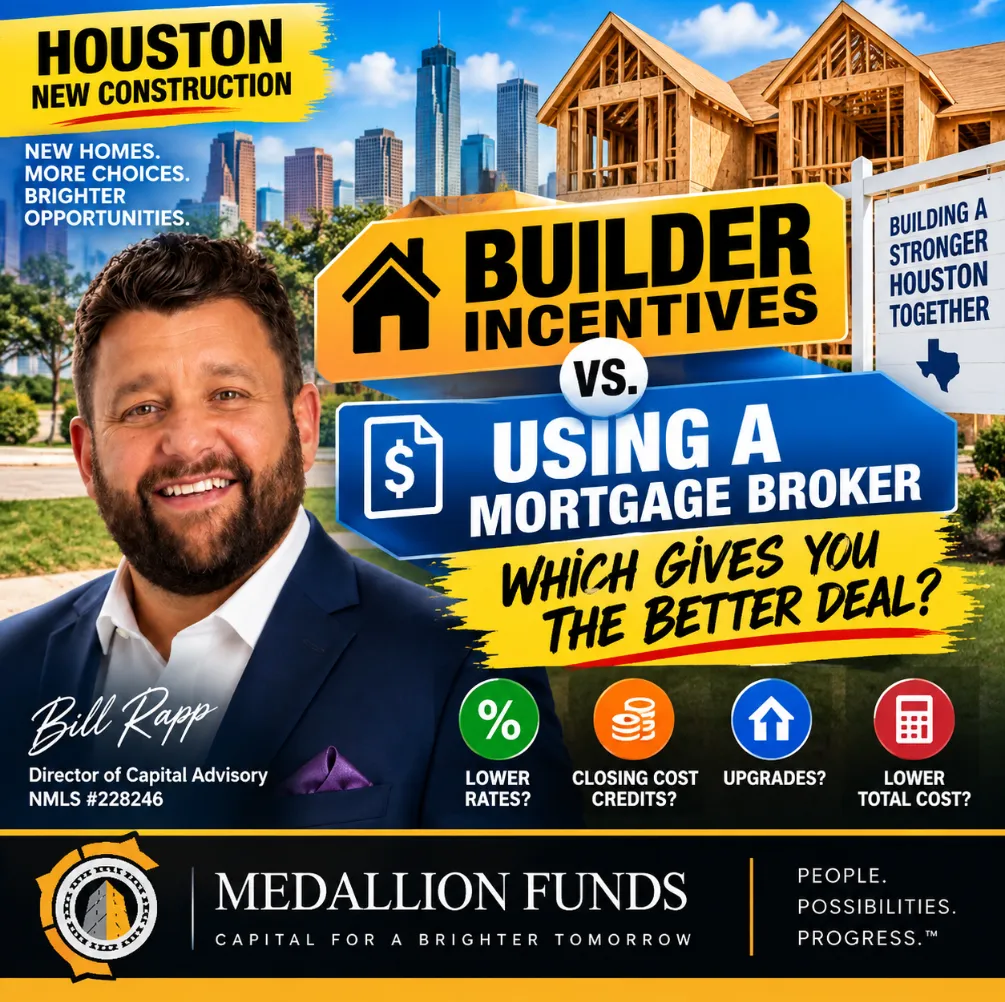
🏗️ Houston New Construction: Builder Financing Incentives vs. Using a Mortgage Broker 🏡
🏗️ Houston New Construction: Builder Financing Incentives vs. Using a Mortgage Broker 🏡
💰 Builder Mortgage Incentives Look Great—But Are They Really the Best Deal for Houston Homebuyers? 🔑
Houston New Construction: Builder Financing Incentives vs. Using a Mortgage Broker
Drive through Houston, Katy, Fulshear, Cypress, Richmond, or many of the other fast-growing communities across Greater Houston, and you will see something homebuyers haven't always had in abundance: new-construction choices and builder incentives.
Builders may advertise mortgage rate buydowns, closing-cost credits, upgrade allowances, discounted interest rates, or other incentives when buyers use the builder's preferred or affiliated lender.
Those offers can be valuable. But there is an important distinction:
A great builder incentive does not automatically mean you are getting the best overall mortgage.
Before choosing the builder's lender, it can make sense to compare the entire financing package with alternatives available through a mortgage broker.
Why Do Houston Builders Offer Mortgage Incentives?
Homebuilders have a different economic model from individual home sellers. They may have multiple completed homes, homes under construction, future phases to release, construction financing costs, and sales targets.
Rather than simply reducing a home's advertised price, a builder may use financing incentives to make the monthly payment or upfront cash requirement more attractive.
Depending on the builder, community, property and financing program, incentives could include:
·Closing-cost assistance
·Permanent mortgage rate buydowns
·Temporary rate buydowns
·Lender credits
·Design-center or upgrade allowances
·Promotional financing on qualifying homes
These incentives can be meaningful, but buyers should understand exactly what they must do to receive them.
An incentive tied to the builder's preferred lender is effectively part of that lender's financing proposal. The correct comparison is therefore not simply rate versus rate.
It is total financing package versus total financing package.
The Preferred-Lender Rate Isn't the Only Number That Matters
Suppose a builder offers a significant closing-cost credit if you finance through its preferred lender.
That sounds attractive—and it may be.
But before accepting the offer, compare several variables:
Interest rate: What rate are you actually receiving, and is it temporary or permanent?
Discount points: Are you paying points to obtain that rate?
Lender fees: What origination, underwriting, processing or other lender charges apply?
Builder credits: How much money are you actually receiving?
Mortgage insurance: If applicable, how does the mortgage insurance compare?
Loan structure: Is this the right mortgage program for your financial situation?
Cash to close: How much money will you need at closing under each scenario?
Monthly payment: What is the actual principal-and-interest payment?
Long-term cost: What happens if you keep the mortgage for five, seven or ten years?
A large credit can still be valuable even when another lender offers a lower rate. Conversely, a promotional rate may be less compelling if the broader financing package is more expensive.
You need the math.
Where a Mortgage Broker Can Add Value
A mortgage broker approaches the transaction differently.
Instead of starting with one preferred lending channel, a broker can evaluate available mortgage programs and lenders to determine which structures may fit the borrower's circumstances.
That can be especially valuable when the borrower isn't a standard W-2 buyer with straightforward income and credit.
At Medallion Funds, we work with borrowers across a range of financing needs, including conventional financing, jumbo mortgages, VA loans, FHA financing, investor loans, doctor and dentist programs, self-employed borrowers, and other specialized scenarios.
The objective isn't to automatically beat the builder's lender.
It is to give the buyer a meaningful comparison before making the decision.
When the Builder's Financing Incentive May Make Sense
Sometimes the builder's financing package really is attractive.
Builders may be willing to subsidize financing aggressively because selling inventory helps accomplish broader business objectives.
If the builder is contributing substantial money toward closing costs or a permanent rate buydown, the economics can be difficult for an outside lender to duplicate.
That's fine.
The goal shouldn't be to avoid the builder's lender. The goal should be to determine whether the incentive produces the most appropriate overall financing structure for you.
When a Mortgage Broker May Have the Advantage
A mortgage broker may become particularly useful when you need something beyond the builder's standard financing box.
For example, you may be:
Self-employed and using tax returns that don't tell the full story of your cash flow.
A physician or dentist exploring specialized professional mortgage programs.
A veteran comparing VA financing options.
Purchasing a higher-priced home requiring jumbo financing.
An investor evaluating financing based on a broader real-estate strategy.
Or you may simply want to compare multiple mortgage structures before committing to a lender.
In these situations, choice can become as important as the advertised incentive.
Compare the Loan Estimate, Not the Advertisement
A builder advertisement is designed to get your attention.
Your financing decision should be based on actual numbers.
Once you have formal Loan Estimates for comparable transactions, evaluate the rate, APR, points, lender fees, credits, cash required to close and projected payments.
Also make sure you're comparing equivalent assumptions.
A 30-year fixed mortgage shouldn't casually be compared with a temporary buydown without understanding what happens after the introductory period.
Likewise, a headline interest rate doesn't tell you how much was paid to obtain it.
Ask About Temporary vs. Permanent Rate Buydowns
This distinction is particularly important with new construction.
A temporary buydown reduces the effective payment for an introductory period before the payment rises according to the underlying note rate.
A permanent buydown uses funds to reduce the mortgage's interest rate for the life of the loan.
Those are fundamentally different structures.
If you're presented with a low introductory payment, ask:
What is my actual note rate?
Then ask what your payment becomes after any temporary subsidy expires.
Don't Ignore Your Future Plans
The right financing structure also depends on how long you expect to own the home and keep the mortgage.
Imagine paying thousands of dollars in additional upfront costs to permanently lower your rate.
If you sell or refinance relatively quickly, you may not keep the loan long enough to recover those costs.
Alternatively, if you expect to keep the property and mortgage for many years, paying for a lower permanent rate could potentially become more valuable.
This is where break-even analysis matters.
Instead of asking only, "Which mortgage has the lowest rate?" ask:
"How long will it take me to recover the additional upfront cost?"
Houston New-Construction Buyers Have Leverage—Use It Carefully
New-construction buyers should look beyond mortgage incentives when negotiating.
Depending on the home, community, builder and market conditions, potential concessions can include financing incentives, closing-cost contributions, upgrades, appliance packages, lot premiums or other items.
Not every builder will negotiate every item, and incentives change frequently.
That makes preparation important.
Get financing organized early, understand your maximum comfortable monthly payment, and compare the builder's complete proposal with outside financing before making your final decision.
Builder Lender vs. Mortgage Broker: It Doesn't Have to Be an Either/Or Decision
One of the biggest mistakes a new-construction buyer can make is assuming the financing decision has already been made simply because the builder presented an incentive.
You can evaluate the builder's proposal and compare it with alternatives.
If the builder's lender produces the strongest overall structure for your situation, you have data supporting that decision.
If another mortgage option produces better economics or fits your financial strategy more effectively, you've identified that before closing.
Either way, the comparison has value.
The Bottom Line
When buying a new-construction home in Houston, don't judge your mortgage solely by the incentive or advertised interest rate.
Compare the complete transaction:
Rate + points + fees + credits + cash to close + monthly payment + loan structure + expected holding period.
The biggest builder incentive isn't necessarily the best mortgage—and the lowest advertised rate isn't necessarily the lowest-cost financing.
At Medallion Funds, our role is to help buyers evaluate the numbers and structure financing around their broader goals.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok