Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
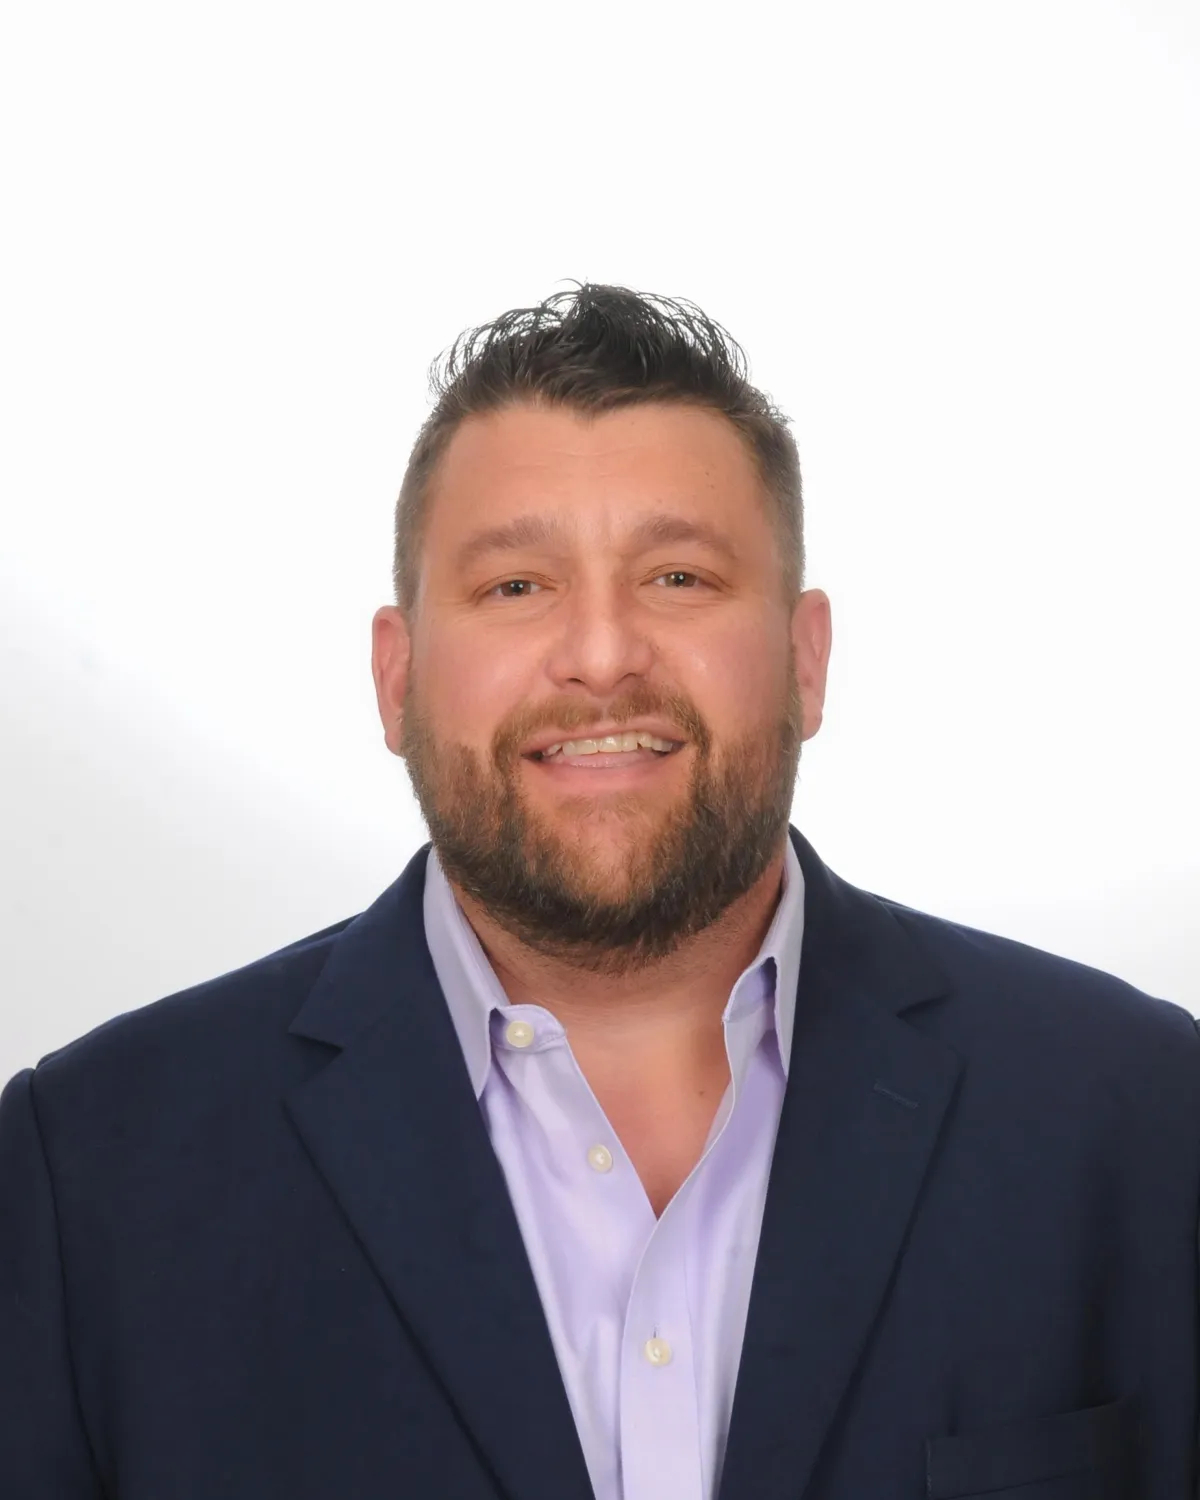
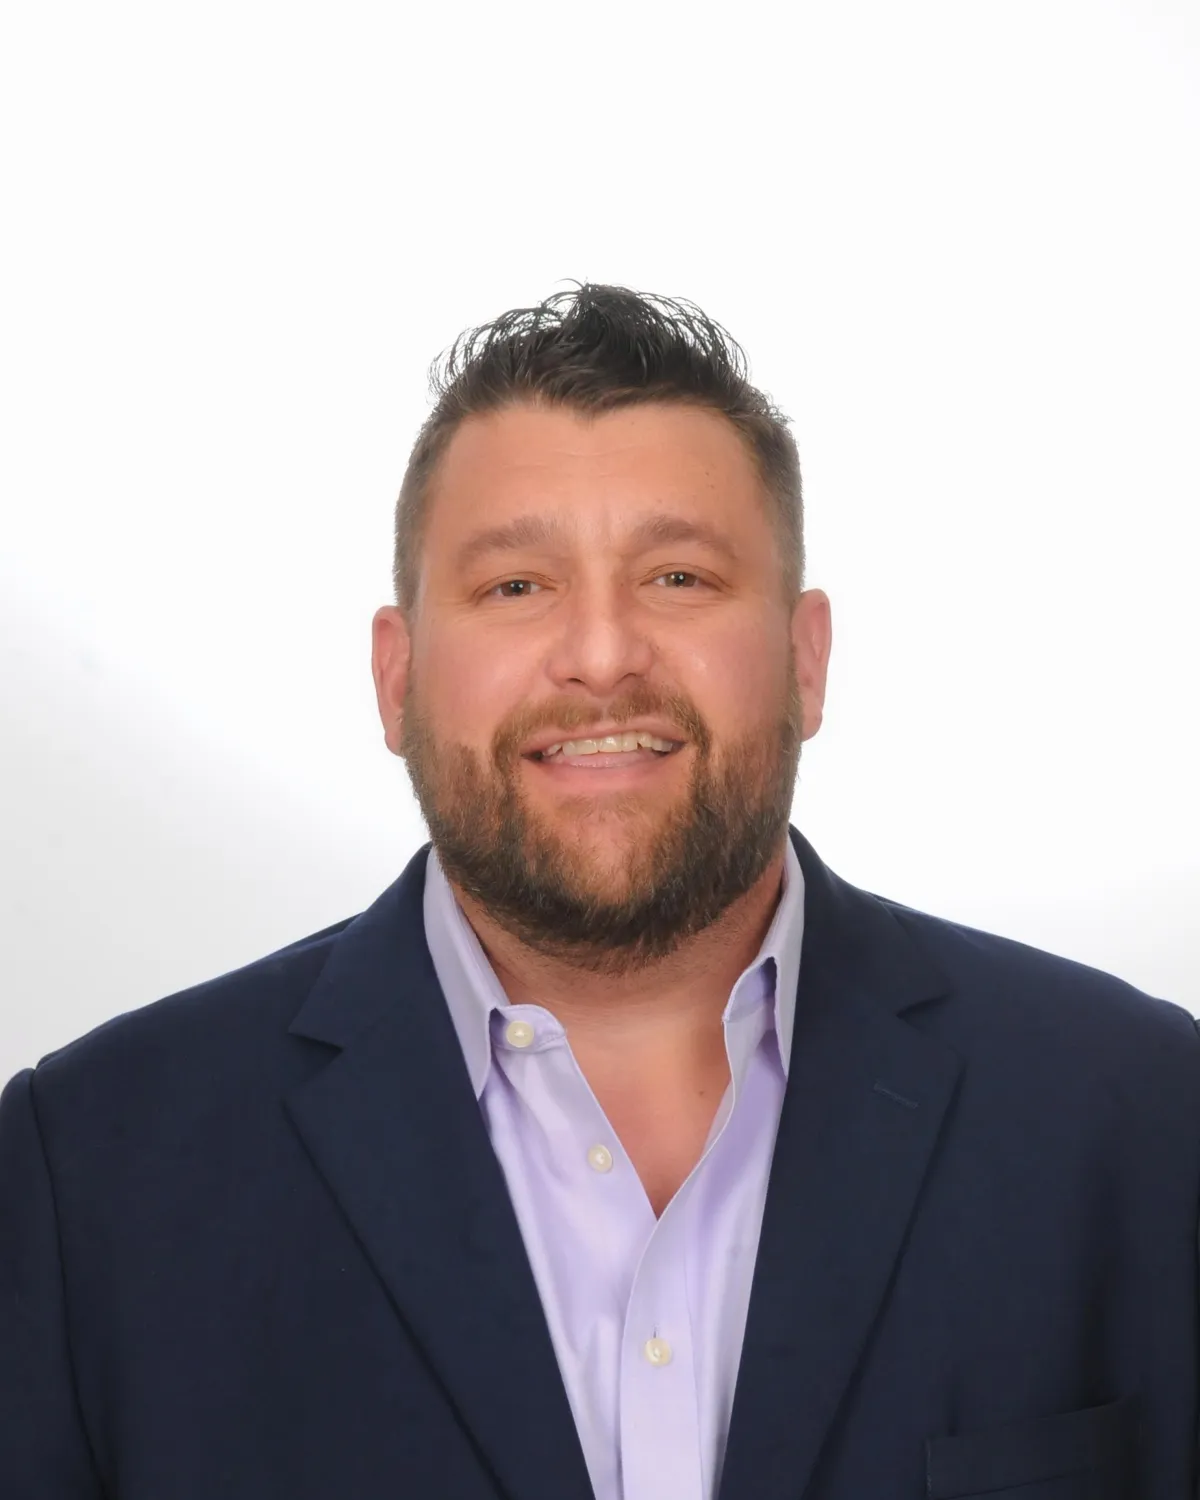
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
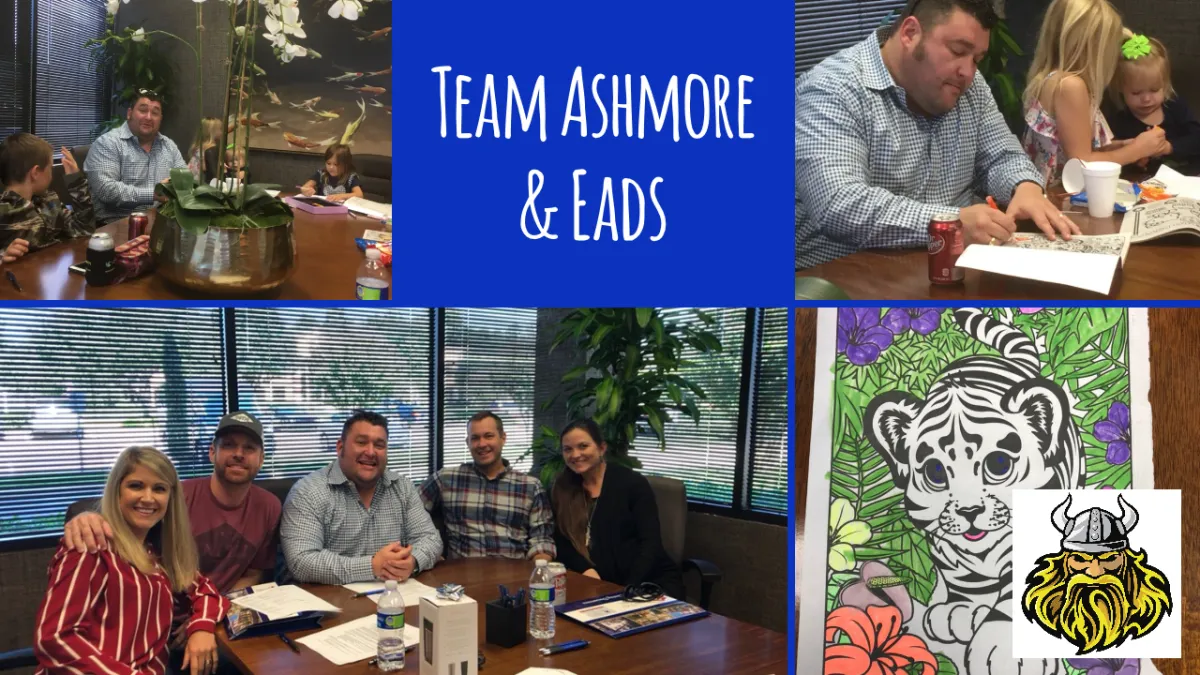
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
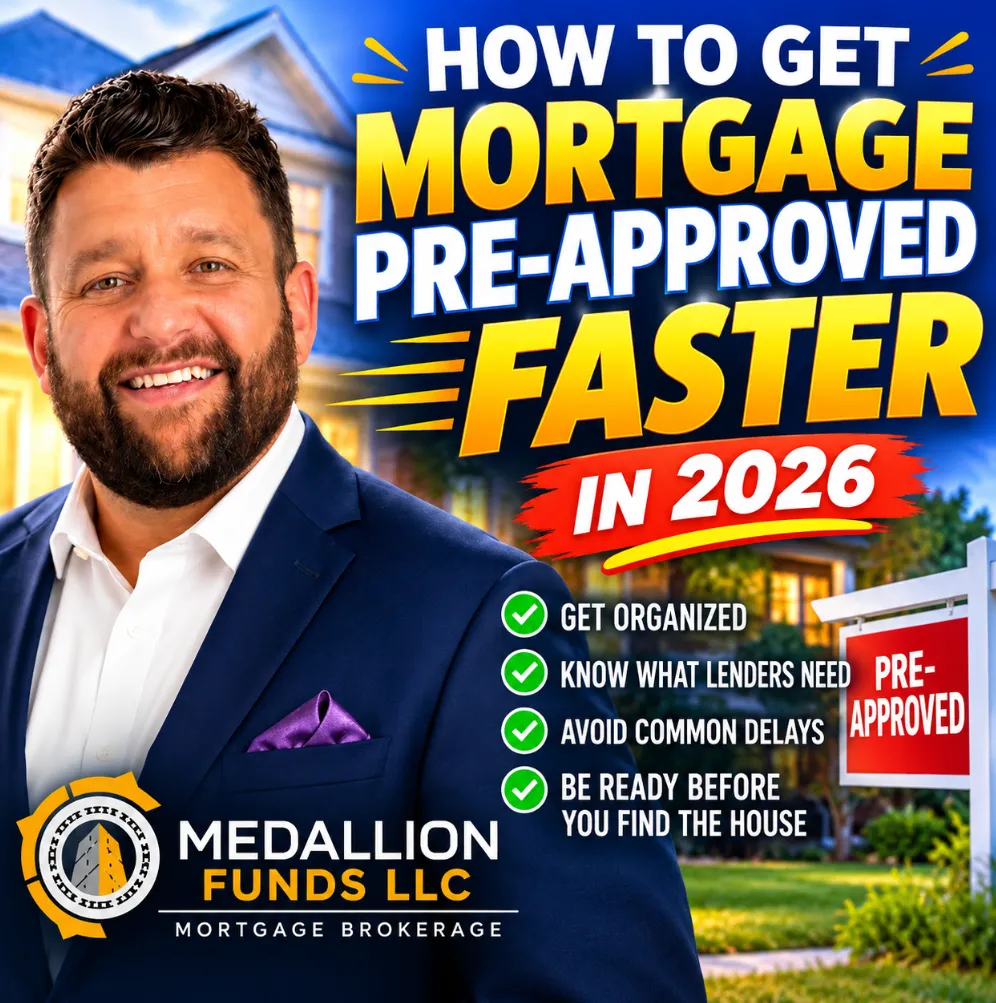
🏡 How to Get Mortgage Pre-Approved Faster in 2026: 7 Steps Before You Start House Hunting 🔑
🏡 How to Get Mortgage Pre-Approved Faster in 2026: 7 Steps Before You Start House Hunting 🔑
⚡ Mortgage Pre-Approval in 2026: How to Get Approved Faster and Avoid Last-Minute Surprises 🏠
How to Get Mortgage Pre-Approved Faster in 2026
When you find the right house, the last thing you want is your mortgage pre-approval slowing you down.
A strong mortgage pre-approval can help you understand your buying power, identify financing issues early, and show a seller that you have already started addressing the financial side of the transaction. The Consumer Financial Protection Bureau notes that lenders generally evaluate your income, assets, debts, and credit record when issuing a pre-approval.
But there is an important distinction:
Getting pre-approved quickly isn't about rushing through the mortgage process. It's about being prepared before the process starts.
Here are seven ways homebuyers can potentially make the mortgage pre-approval process faster and smoother in 2026.
1. Gather Your Mortgage Documents Before Applying
One of the easiest ways to create delays is to start an application and then spend days searching for documents.
For a typical salaried borrower, it can help to have your recent paystubs, W-2s, bank and investment statements, identification, and information about your current debts readily available.
Fannie Mae's current 2026 guidance requires lenders to verify employment income used to qualify. Depending on the loan and underwriting findings, that verification may involve borrower documentation, employer information, or third-party verification services.
If you're self-employed, own multiple businesses, receive rental income, earn commissions or bonuses, or have other less-traditional income, your documentation requirements may be more extensive.
The more complicated your financial picture, the more valuable it can be to start early.
2. Complete the Application Accurately the First Time
Speed isn't just about uploading documents quickly.
It's also about providing accurate information.
Your mortgage application may include information about your:
·Employment and income
·Assets and available funds
·Existing debts
·Real estate owned
·Housing history
·Loan purpose and occupancy
·Other financial obligations
Fannie Mae requires lenders to confirm that information used in underwriting is accurate and complete and to maintain documentation supporting items such as income, employment, assets and credit history.
Missing or inconsistent information can create additional questions later.
3. Don't Hide the Complicated Parts
Changed jobs recently?
Own another property?
Self-employed?
Receiving bonus, commission or overtime income?
Using gift funds?
Have a large recent bank deposit?
Tell your mortgage professional before the file reaches a critical point.
Mortgage underwriting is fundamentally about documenting the borrower's ability to meet the loan requirements. Fannie Mae, for example, describes stable and predictable income as a foundational component of underwriting and requires qualifying income to be appropriately documented.
A potentially complicated issue identified on Day 1 can often be addressed much more efficiently than the same issue discovered days before closing.
4. Know the Difference Between Pre-Qualification and Pre-Approval
These terms are sometimes used interchangeably in the marketplace, but consumers should understand what has actually been reviewed.
A pre-approval generally involves a lender reviewing your financial information and credit to estimate how much you may be able to borrow. It is still not a final loan approval.
The CFPB specifically notes that a pre-approval letter is conditional on further confirmation of the borrower's information.
That's why I encourage buyers to focus on the quality of the review, not simply how quickly someone can generate a letter.
A five-minute letter isn't necessarily better than a thorough pre-approval that identifies potential problems before you sign a purchase contract.
5. Don't Make Major Financial Changes After Pre-Approval
Getting your pre-approval isn't the end of the financing process.
Once you're preparing to purchase a home, avoid making unnecessary financial moves without first discussing them with your mortgage professional.
That can include opening new credit accounts, financing furniture or vehicles, changing employment, moving large amounts of money between accounts, or taking on additional debt.
Remember: your final loan approval depends on the information ultimately verified by the lender.
Your goal should be to keep your financial profile as stable and documentable as possible between pre-approval and closing.
6. Get Pre-Approved Before You Find the House
Waiting until you've found the perfect property puts unnecessary pressure on the process.
The CFPB recommends exploring mortgage choices before finding a home because an accepted offer can leave a buyer with only a short period to arrange financing.
Starting early gives you time to address issues involving credit, debt-to-income ratios, cash reserves, documentation, or loan-program eligibility.
It can also help answer a much more important question than:
"What's the maximum house I qualify for?"
Instead, ask:
"What purchase price and monthly payment make sense for my financial goals?"
Those aren't necessarily the same number.
7. Work With a Mortgage Broker Who Can Evaluate Multiple Loan Options
Not every borrower fits neatly into the same mortgage program.
One borrower may be best suited for conventional financing. Another may need FHA or VA financing. A physician may benefit from evaluating doctor-loan options, while a self-employed borrower may need an alternative documentation program.
That's where working with a mortgage broker can add value.
At Medallion Funds, our objective isn't simply to generate a pre-approval letter. It's to understand the borrower's complete financial picture, evaluate appropriate financing strategies, and identify potential obstacles as early as possible.
That may include Conventional, FHA, VA, USDA, Jumbo, Doctor/Dentist, Bank Statement, Non-QM, DSCR and other financing solutions, subject to program availability and borrower eligibility.
What Should You Have Ready for Mortgage Pre-Approval?
Before contacting your mortgage professional, start assembling your income documentation, asset statements, identification, employment history, housing information and details regarding other properties or businesses you own.
If you're self-employed, additional tax-return and business documentation may be necessary. Fannie Mae's 2026 guidelines, for example, specify tax-return requirements for certain types of qualifying income and require applicable schedules when federal tax returns are used.
Don't worry about deciding exactly which documents apply to you before you call. The objective is simply to get organized.
Pre-Approval vs. Loan Estimate: One Important Difference
A pre-approval letter should not be confused with a Loan Estimate.
The CFPB explains that consumers generally need to provide six pieces of information to trigger a Loan Estimate: name, income, Social Security number, property address, estimated property value and desired loan amount. The lender generally must then provide the Loan Estimate within three business days.
A Loan Estimate allows you to evaluate estimated rates, payments, closing costs and other loan terms.
The CFPB recommends comparing mortgage offers rather than assuming the first option is automatically the best fit.
The Bottom Line
If you want to get mortgage pre-approved faster in 2026, preparation is usually more valuable than speed alone.
Gather your documents. Complete your application accurately. Disclose complications early. Avoid unnecessary financial changes. And start the financing conversation before you find the house.
A strong pre-approval isn't simply a piece of paper.
It's the beginning of your financing strategy.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok