Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
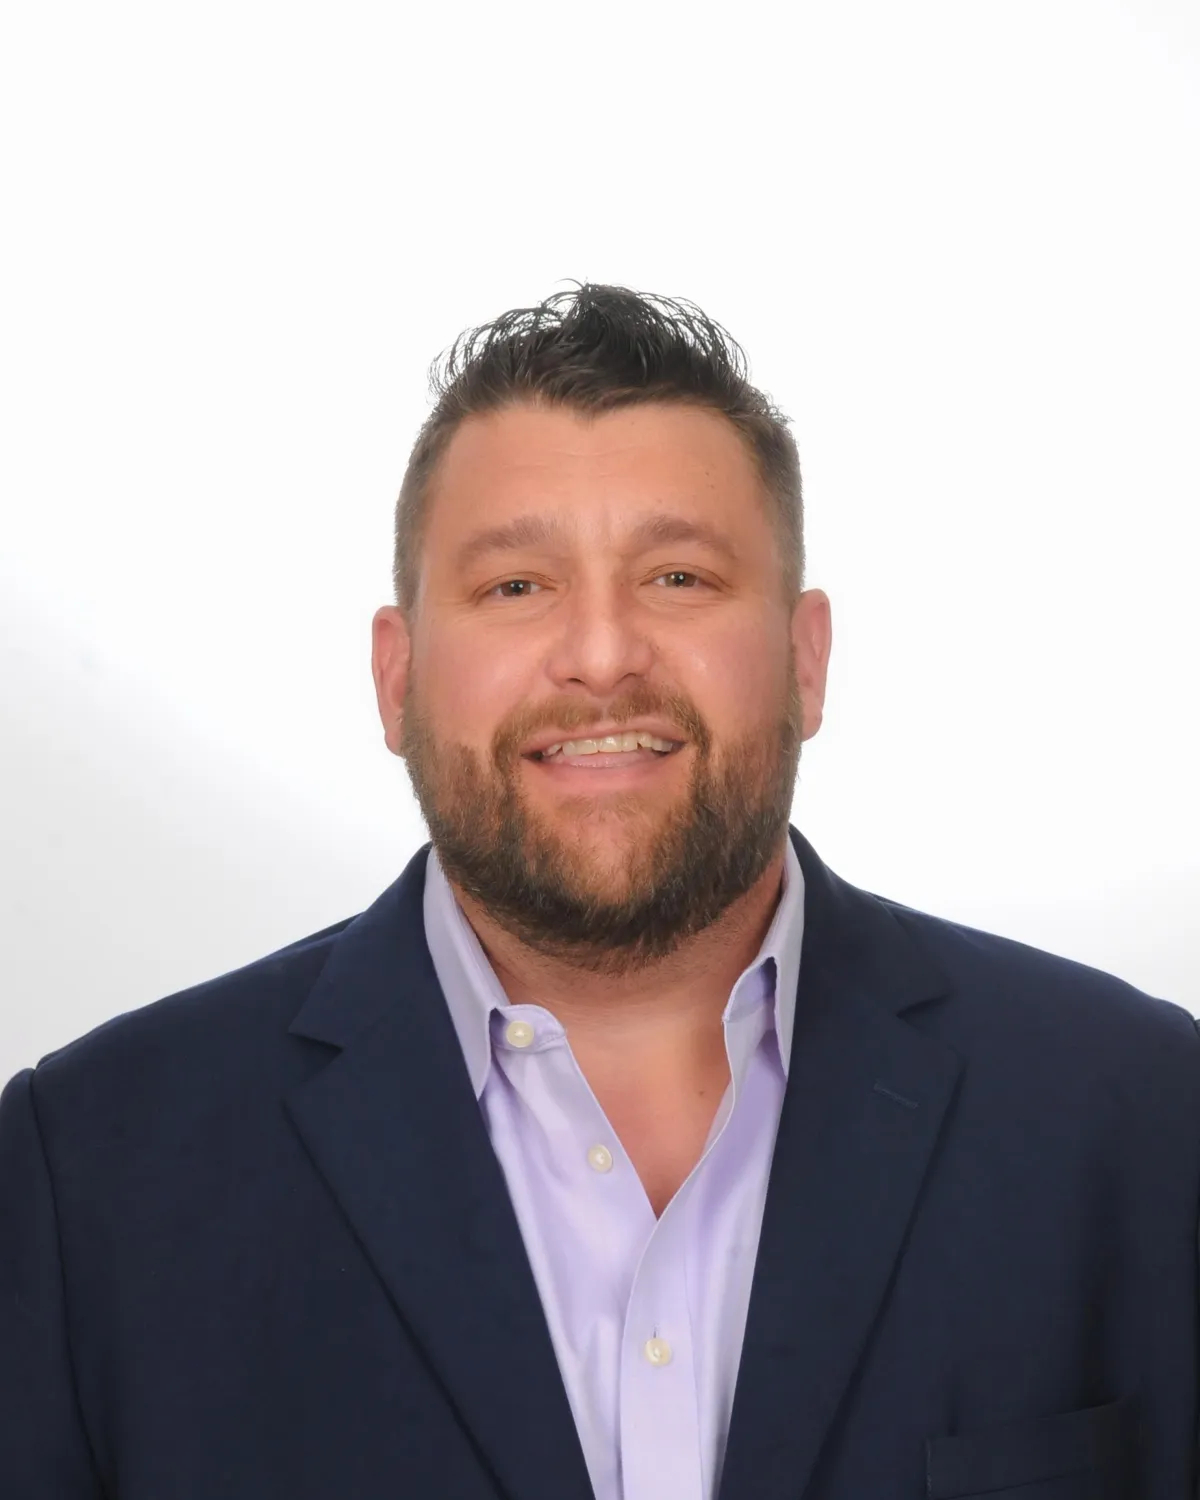
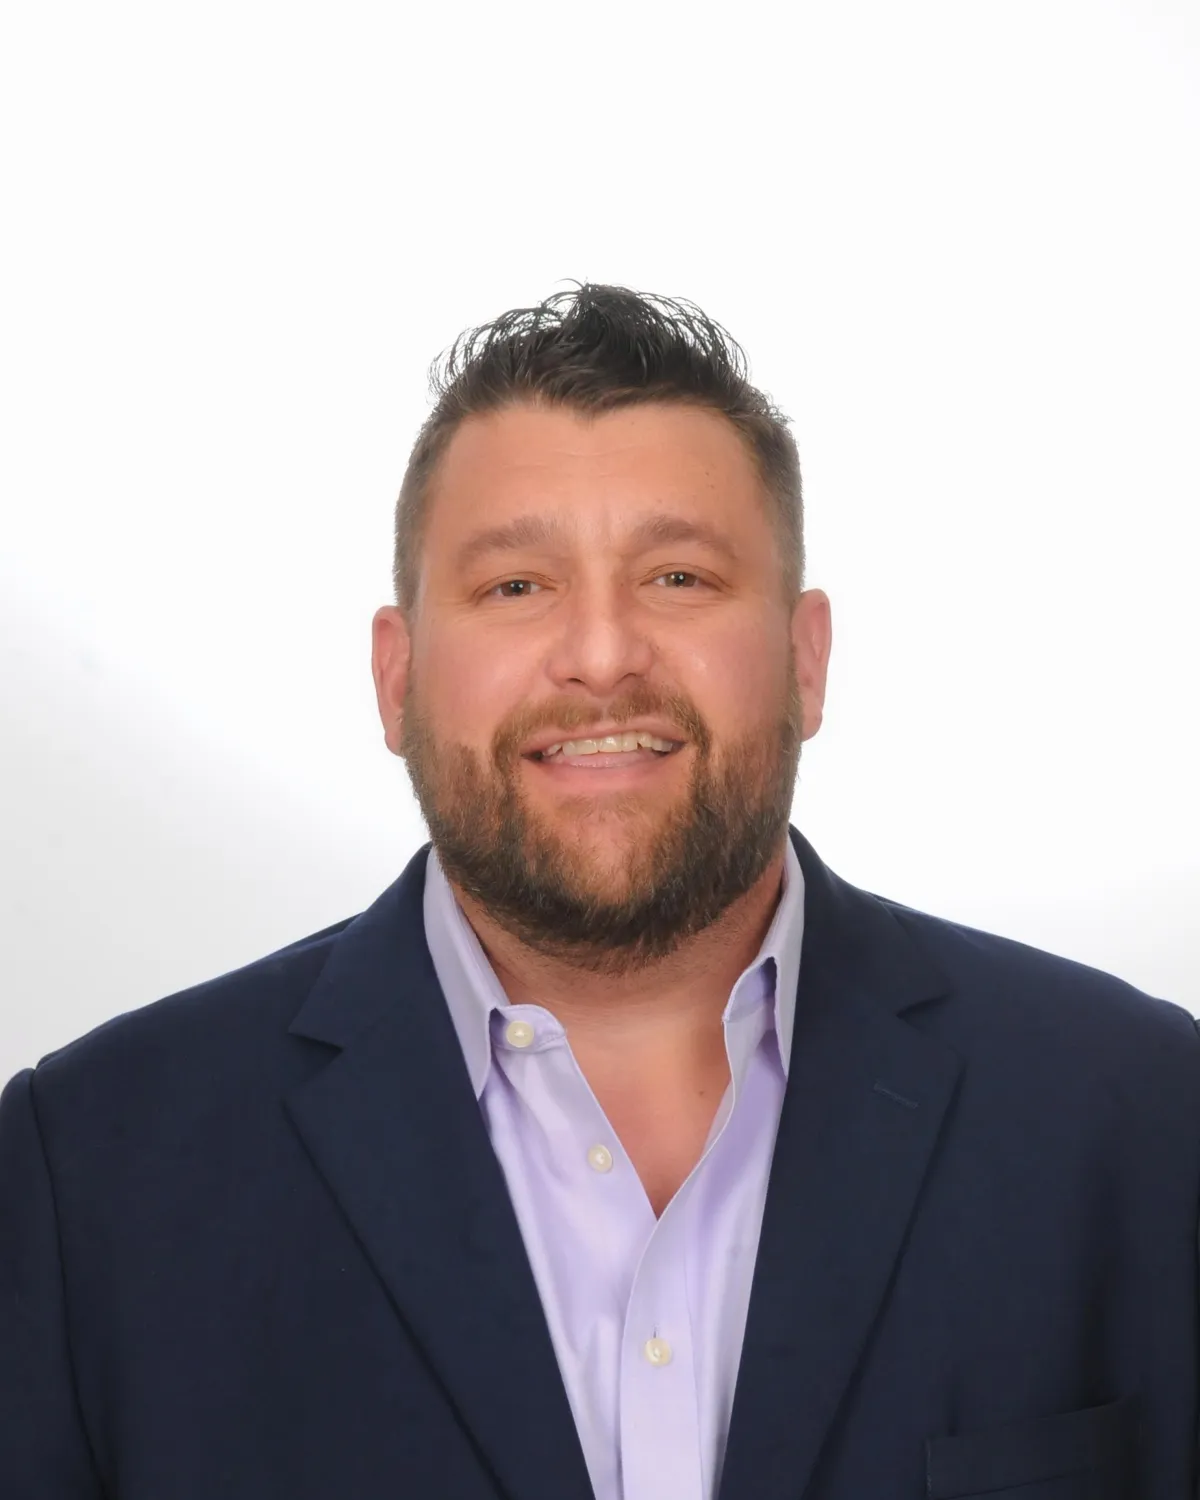
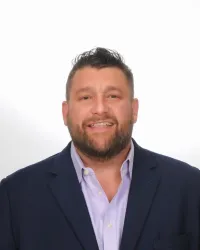
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
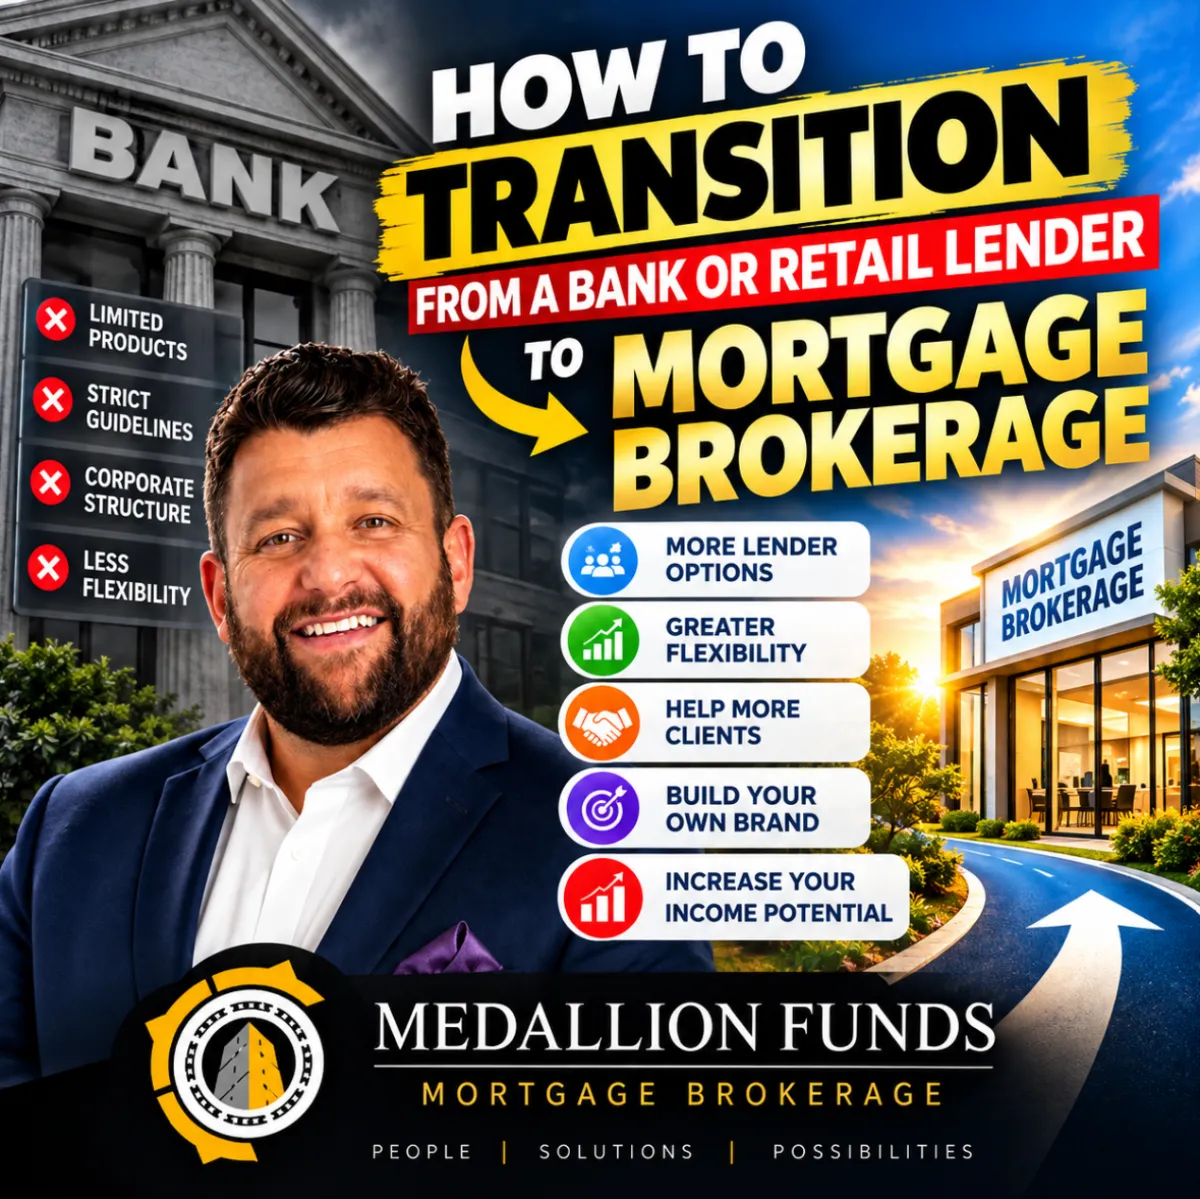
🏦➡️🏠 How to Transition From a Bank or Retail Lender to Mortgage Brokerage: A Loan Officer’s Career Guide 🚀
🏦➡️🏠 How to Transition From a Bank or Retail Lender to Mortgage Brokerage: A Loan Officer’s Career Guide 🚀
💼 Ready for More Lending Options? How Bank Loan Officers Can Transition to Mortgage Brokerage 🔑
________________________________________________________________________________
How to Transition From a Bank or Retail Lender to Mortgage Brokerage
If you have spent your mortgage career working for a bank, credit union, direct lender, or large retail mortgage company, you probably understand both the advantages and limitations of working inside a single lending platform.
You may have strong training, established processes, recognizable branding, operational support, and a steady flow of potential customers. But you may also encounter a recurring problem:
What happens when you have a good borrower who simply does not fit your institution's lending guidelines?
That is one of the fundamental differences between working for a retail lender and working in mortgage brokerage.
A mortgage broker can potentially access multiple lenders, loan programs, pricing structures, and underwriting approaches instead of relying primarily on the products offered by one institution.
For experienced mortgage professionals, transitioning from a bank or retail lender to mortgage brokerage can create significant opportunities—but it also requires a different mindset.
Bank Loan Officer vs. Mortgage Broker: What's the Difference?
A bank or retail mortgage loan officer generally originates loans through the institution employing them. The institution determines which mortgage products are available, establishes its credit and underwriting parameters, and controls much of the origination infrastructure.
Mortgage brokerage operates differently.
Instead of representing one lending institution's product menu, a mortgage brokerage may work with multiple wholesale lenders. Depending on the brokerage and the loan officer's licensing and product access, this can create opportunities to serve borrowers with a broader range of financing needs.
That could include:
·Conventional mortgages
·FHA loans
·VA loans
·USDA loans
·Jumbo mortgages
·Doctor and dentist loans
·Bank statement mortgages
·DSCR investor loans
·Non-QM mortgages
·Renovation financing
·Portfolio lending
·Other specialty mortgage programs
The objective is not simply to have more products. It is to have more potential solutions when a borrower's financial situation does not fit a traditional lending box.
Why Loan Officers Consider Leaving Retail Lending
There usually is not one reason someone considers making the move.
For some loan officers, the primary attraction is product flexibility.
For others, it is compensation, independence, entrepreneurial opportunity, or the ability to build a personal brand.
Experienced originators may also become frustrated when they spend weeks developing a borrower relationship only to discover that their institution cannot approve the transaction.
In a brokerage environment, the question can shift from:
"Does this borrower fit our bank?"
to:
"Which lending solution may fit this borrower?"
That change in perspective can fundamentally alter how an originator approaches mortgage lending.
1. Understand That You Are Becoming More Entrepreneurial
One of the biggest adjustments when transitioning from a bank to mortgage brokerage is psychological.
You should begin thinking more like a business owner.
A strong brokerage platform can provide technology, processing, lender relationships, compliance support, training, marketing resources, and operational infrastructure.
But the loan officer still needs to develop business.
That means building relationships with referral partners, generating leads, maintaining a database, following up consistently, developing expertise, and creating a recognizable presence in the marketplace.
Someone accustomed to receiving leads from bank branches or centralized marketing should understand this difference before making the transition.
2. Learn the Wholesale Mortgage Marketplace
Retail loan officers often become extremely knowledgeable about their employer's products.
Mortgage brokers need a broader knowledge base.
You do not need to memorize every guideline from every lender. You do, however, need to become proficient at identifying the characteristics of a loan and determining which lenders or programs deserve further investigation.
Consider two borrowers earning exactly the same amount of money.
One may be a salaried employee with excellent credit.
The other may own a business, aggressively minimize taxable income, own several rental properties, and have substantial liquid assets.
Their financial capacity may be similar, but their optimal mortgage solutions could be completely different.
This is where product knowledge becomes a competitive advantage.
3. Build Your Referral Network Before You Move
Do not wait until your transition is complete before thinking about business development.
Start developing your professional network.
Potential referral relationships can include:
·Residential real estate agents
·Homebuilders
·CPAs
·Financial advisors
·Estate-planning attorneys
·Divorce attorneys
·Insurance professionals
·Business owners
·Commercial real estate professionals
·Past clients and personal contacts
The objective is not to constantly ask people for referrals.
Become a financing resource they trust.
When referral partners encounter an unusual borrower or complicated financing scenario, you want your name to come to mind.
4. Choose a Niche
Trying to market yourself to everyone can make it difficult to differentiate yourself.
Instead, consider developing expertise around specific borrower segments.
For example, a mortgage professional could specialize in doctors and dentists who have significant income but substantial student debt.
Another could focus on self-employed borrowers who have difficulty documenting income through traditional tax-return underwriting.
Another could become highly knowledgeable about real estate investors, DSCR loans, rental properties, and portfolio financing.
Other potential niches include veterans, first-time homebuyers, jumbo borrowers, renovation borrowers, or clients purchasing newly constructed homes.
A niche does not prevent you from helping other borrowers.
It gives the market a reason to remember you.
5. Build Your Personal Brand
Bank loan officers often benefit from their employer's brand recognition.
Independent mortgage professionals need to intentionally develop their own reputation.
That can include:
·Educational YouTube videos
·Short-form video
·Blog content
·LinkedIn posts
·Email newsletters
·Homebuyer seminars
·Realtor education
·Community networking
·Local business organizations
Your content should answer the questions borrowers and referral partners are already asking.
For example:
"Can I qualify for a mortgage if I am self-employed?"
"How much money do I need after closing on a jumbo mortgage?"
"How does a DSCR loan work?"
"Can doctors qualify with large student loan balances?"
"What is the difference between FHA and conventional financing?"
Every useful answer becomes another opportunity for someone to discover your expertise.
6. Understand Your New Compensation Structure
Before joining any mortgage brokerage, understand exactly how compensation works.
Do not evaluate an opportunity solely by the advertised commission split.
Ask about processing fees, technology costs, CRM expenses, marketing expenses, licensing costs, lead costs, lender-paid versus borrower-paid compensation structures where applicable, and any other charges affecting your economics.
More importantly, evaluate what you receive in exchange.
A strong mortgage brokerage platform should help you originate and close loans—not merely provide a place to hang your license.
7. Evaluate Operational Support
Producing loans is only part of the business.
You also need to close them.
Before transitioning to a mortgage brokerage, investigate the operational infrastructure supporting the originator.
Ask questions about processing, disclosures, compliance, underwriting escalation, lender selection, scenario support, closing coordination, technology, CRM capabilities, marketing resources, and training.
A large lender menu has limited value if the originator does not have the infrastructure necessary to navigate it effectively.
8. Develop a 90-Day Transition Plan
Treat the move like a business launch.
Days 1–30: Build the Foundation
Learn the brokerage's systems, lender network, products, CRM, pricing tools, compliance requirements, and loan process.
Create a list of referral partners and professional contacts.
Clarify your niche and positioning.
Days 31–60: Increase Market Activity
Schedule meetings with real estate agents, builders, CPAs, financial advisors, and other potential referral partners.
Begin consistently publishing educational content.
Reconnect with your professional network in compliance with applicable employment, privacy, licensing, and solicitation requirements.
Days 61–90: Build a Repeatable System
Track where your opportunities originate.
Measure conversations, referral meetings, applications, preapprovals, closings, and conversion rates.
Identify the activities producing results and repeat them.
The objective is to develop a predictable mortgage origination system rather than relying on sporadic referrals.
Mortgage Brokerage Is About Optionality
The biggest advantage of the mortgage broker model is not necessarily having the lowest rate on every transaction.
It is optionality.
Different borrowers have different credit profiles, income structures, assets, properties, and financial objectives.
A traditional lending institution may be an excellent fit for one borrower and completely wrong for another.
A mortgage broker can potentially evaluate a broader range of solutions.
That can be especially valuable when working with borrowers whose financial lives do not fit neatly into a standardized lending box.
Is Mortgage Brokerage Right for You?
Mortgage brokerage can be particularly attractive to professionals who enjoy prospecting, relationship building, problem solving, entrepreneurship, and developing their own personal brand.
It may be less attractive to someone who strongly prefers a salaried environment, internally generated leads, a narrow product menu, or a highly structured corporate sales process.
Neither model is automatically better.
The important question is which model aligns with the type of mortgage career you want to build.
Considering a Career in Mortgage Brokerage?
At Medallion Funds, we believe mortgage professionals should be equipped to help borrowers evaluate financing solutions rather than simply take applications.
The brokerage model can give experienced originators the opportunity to expand their product knowledge, build referral relationships, develop a personal brand, and serve a wider range of borrowers.
If you currently work for a bank, retail mortgage company, or another lending institution and are exploring what mortgage brokerage could look like for your career, start by understanding the platform, compensation, operational support, lender access, compliance requirements, and business-development expectations.
The goal isn't simply to leave retail lending.
It's to build a mortgage business designed for where you want your career to go next.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok