Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
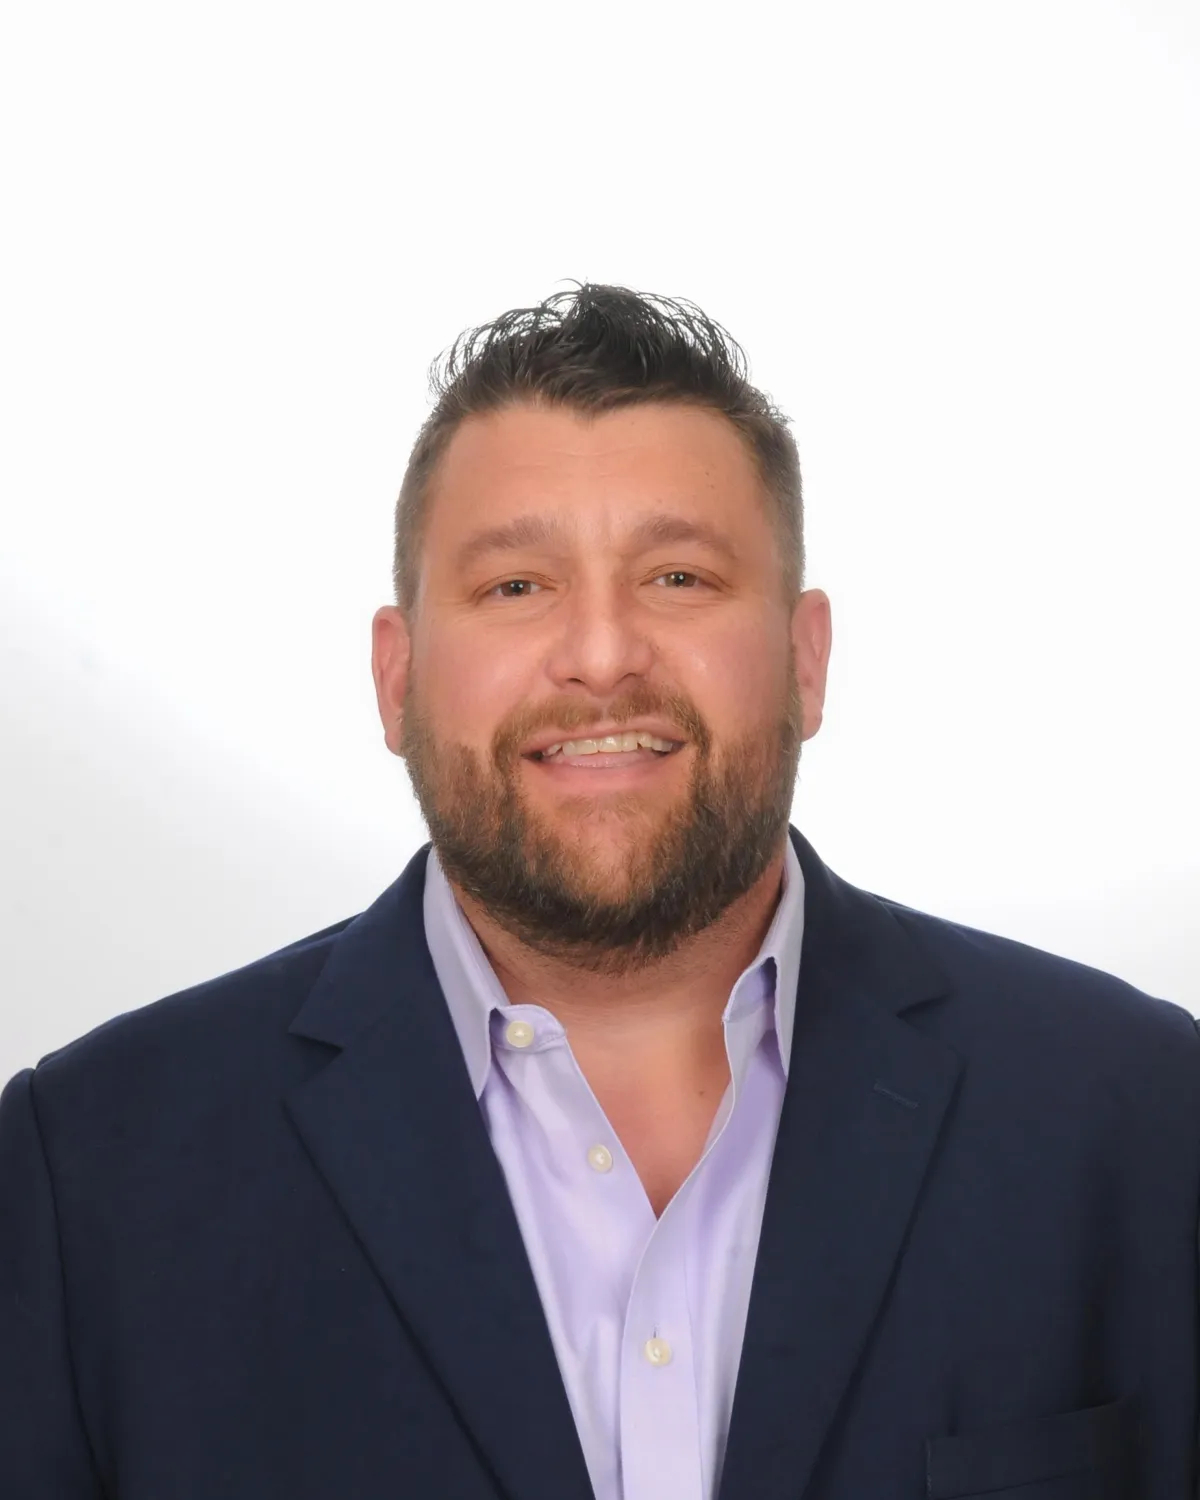
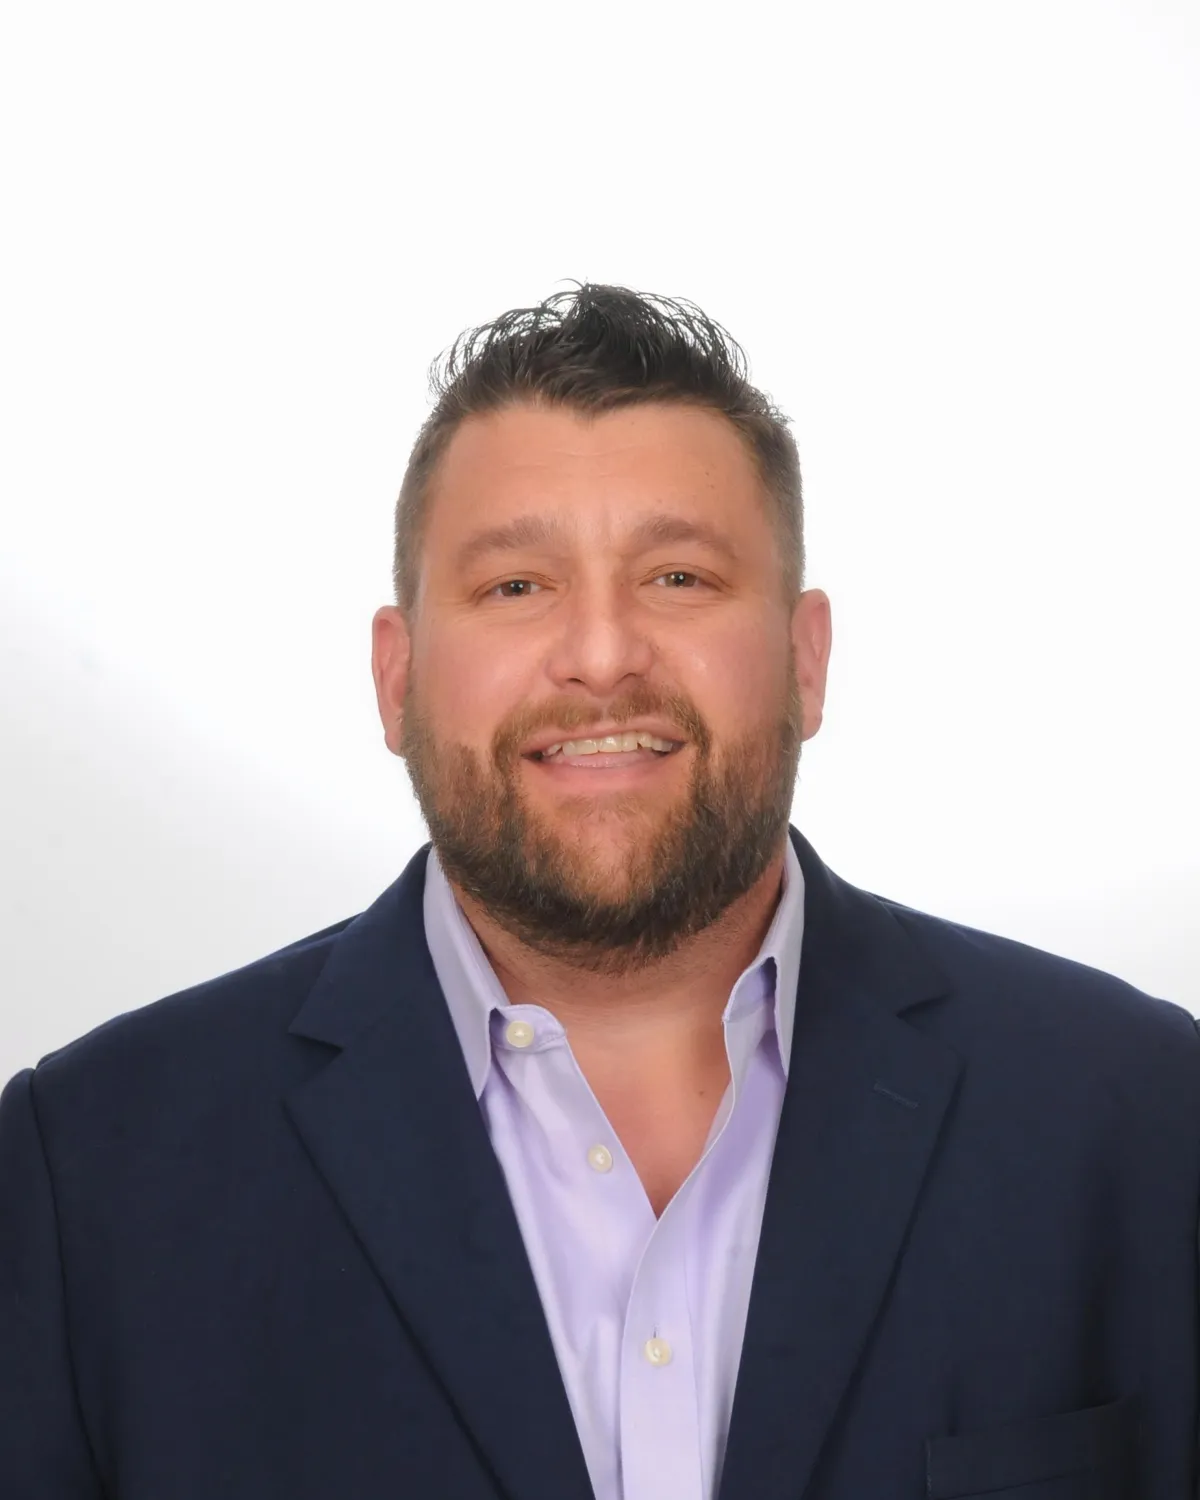
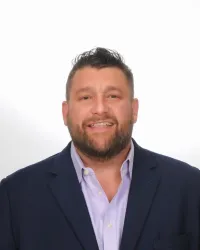
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
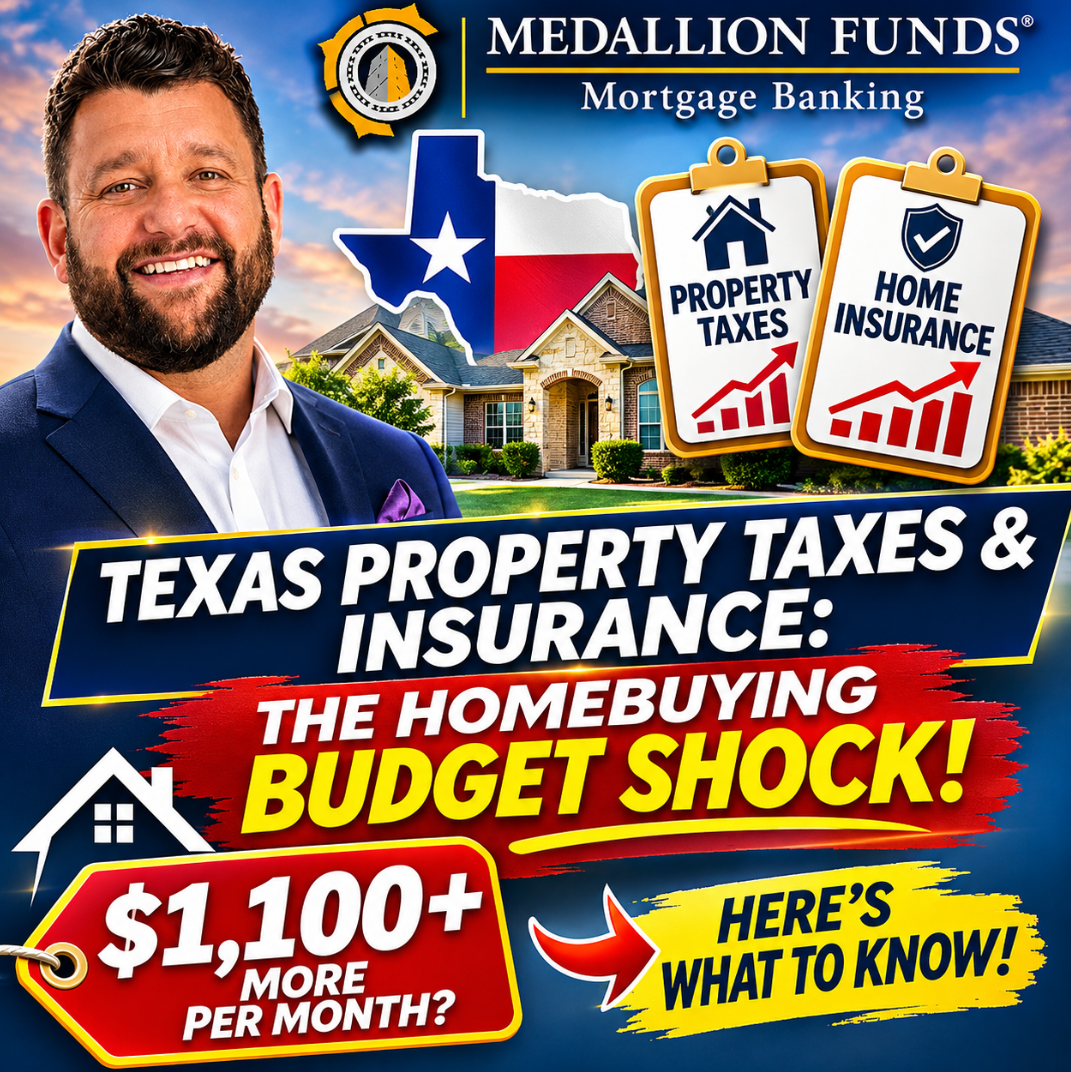
🏡 Texas Property Taxes & Insurance: The Hidden Cost of Buying a Home 💸
🏡 Texas Property Taxes & Insurance: The Hidden Cost of Buying a Home 💸
🚨 Texas Homebuyers: Property Taxes & Insurance Could Break Your Budget! 🏠
_______________________________________________________________________________
🏡 Texas Property Taxes and Insurance: The Hidden Homebuying Budget Shock
Buying a home in Texas can come with an unpleasant financial surprise.
You find the perfect house. The purchase price fits your budget. Your mortgage rate looks competitive. Your lender gives you an estimated principal and interest payment that seems manageable.
Then you see the actual monthly housing payment.
Suddenly, your affordable home costs hundreds—or even thousands—of dollars more per month than you expected.
What's causing the difference?
Texas property taxes and homeowners insurance.
For homebuyers in Houston, Katy, Fulshear, Dallas, Austin, San Antonio, and communities throughout Texas, these expenses can dramatically change housing affordability.
I'm Bill Rapp with Medallion Funds, and I help homebuyers evaluate mortgage financing options based on the complete cost of homeownership—not just the interest rate.
Here's what every Texas homebuyer should understand before making an offer.
1. Your Mortgage Payment Is More Than Principal and Interest
One of the biggest mistakes homebuyers make is calculating affordability using only their mortgage principal and interest.
Your actual monthly housing expense may include four primary components, commonly called PITI.
Component | What it covers |
Principal | Repayment of your mortgage balance |
Interest | Cost of borrowing money |
Property taxes | Local property taxes, including school and other taxing districts |
Insurance | Homeowners insurance protecting against covered losses |
Depending on your financing, you may also pay mortgage insurance, HOA dues, flood insurance, or other assessments.
These additional expenses can significantly affect both your monthly budget and your mortgage qualification.
The important distinction: Your lender may approve a particular loan amount, but that doesn't automatically mean the resulting housing payment is comfortable for your household.
2. Why Texas Property Taxes Can Surprise Homebuyers
Texas does not impose a state individual income tax, but local governments rely heavily on property taxes.
Your total property tax bill may include taxes assessed by school districts, counties, cities, municipal utility districts (MUDs), and other special districts.
The total rate varies by property location.
Two homes with identical purchase prices—even within the same general area—can have very different annual property tax obligations.
Consider a $400,000 home.
Illustrative property tax comparison
2.0% effective tax rate
$667/mo
$8,000 annually
3.0% effective tax rate
$1,000/mo
$12,000 annually
Illustrative effective tax burdens applied to a $400,000 value, before exemptions. Actual bills depend on taxable value, exemptions, and applicable taxing jurisdictions.
That's a $333 monthly difference—or approximately $4,000 annually—for homes with the same price.
Over five years, the difference could total $20,000, assuming the same tax amounts.
Homebuyer tip: Before submitting an offer, review the property's applicable taxing districts, estimated post-purchase taxable value, and potential homestead exemption.
3. Texas Homestead Exemptions: What Buyers Need to Know
A Texas residence homestead exemption may reduce the taxable value of an eligible primary residence.
Texas currently provides a $140,000 mandatory school district residence homestead exemption, following voter approval of the increase in November 2025.
For example, an eligible home with a $400,000 school-district taxable value before that exemption could have a school-district taxable value of $260,000 afterward, assuming no other adjustments.
However, homestead exemptions do not eliminate all property taxes, and exemptions vary by taxing jurisdiction and eligibility.
Another important consideration is the homestead appraisal limitation, often described as the 10% cap. For qualifying existing homesteads, this generally limits annual increases in appraised value for tax purposes, subject to exceptions and statutory rules. It does not cap the annual tax bill or apply immediately to every new purchase.
A seller's current tax bill may not accurately reflect what you will pay after purchasing the property.
Ask your mortgage professional to calculate a realistic post-purchase estimate rather than relying exclusively on the seller's historical tax statement.
4. Why Texas Homeowners Insurance Can Be Expensive
Texas homeowners face several property insurance risks, including severe thunderstorms, hail, windstorms, hurricanes, and other weather-related damage.
Houston-area buyers may also need to consider coastal storm exposure, flood risk, and individual property characteristics.
Homeowners insurance premiums depend on multiple factors:
·Property location, age, roof condition, and construction
·Replacement cost and coverage limits
·Deductibles and claim history
·Insurer underwriting and available discounts
·Windstorm or other coverage restrictions
A $400,000 house does not automatically require $400,000 in dwelling coverage. Insurers generally evaluate the cost to rebuild the structure, which can differ from its market value.
And here's an important detail: Standard homeowners insurance typically excludes flood damage.
If a property is in a qualifying high-risk flood zone and the mortgage is federally regulated or backed, separate flood insurance may be required. Other homeowners may still benefit from evaluating flood coverage.
5. Real-World Example: A $400,000 Texas Home
Let's examine how taxes and insurance can change a mortgage payment.
Illustrative Texas mortgage scenario
Not a rate quote
Home price$400,000
Down payment5%
Interest rate6.50%
Effective property tax rate2.50%
Annual homeowners insurance
$3,600
Estimated monthly PITI
$3,535
Principal, interest, property taxes and homeowners insurance
Principal & interest
$2,402/mo
Property taxes
$833/mo
Homeowners insurance
$300/mo
30-year fixed-rate illustration, with a 5% default down payment. Excludes PMI, HOA dues, flood insurance, maintenance, and closing costs. Not an actual loan offer or qualification calculation.
Using the default assumptions, a buyer purchasing a $400,000 home with 5% down and a hypothetical 6.5% fixed rate would have approximately $2,402 in monthly principal and interest.
Add $833 in monthly property taxes and $300 for homeowners insurance, and the total reaches approximately $3,535 per month before mortgage insurance and other expenses.
That is more than $1,100 above the principal and interest payment alone.
This is why I encourage buyers to compare homes using the complete monthly housing payment.
6. How Escrow Shortages Can Increase Your Mortgage Payment
Your mortgage payment can change even if you have a fixed interest rate.
Why?
Because your property taxes and insurance premiums may change.
When your mortgage servicer collects money through an escrow account, it estimates the funds needed for future tax and insurance bills.
If those bills rise, your servicer may increase the monthly escrow collection.
If the escrow account has a shortage, you may also have to repay that shortage through additional monthly payments or another permitted repayment method.
For example, a $1,200 escrow shortage spread over 12 months could add $100 per month temporarily, on top of any increase needed for future expenses.
A fixed-rate mortgage protects the principal-and-interest rate calculation—not the total monthly payment from changes in taxes and insurance.
7. How Texas Homebuyers Can Avoid Budget Shock
Before purchasing a home, take these steps:
1.Request a property-specific tax estimate. Evaluate the anticipated taxes after purchase, not just the seller's existing bill.
2.Get insurance quotes early. Compare coverage, deductibles, exclusions, and replacement-cost assumptions.
3.Review flood exposure. Determine whether flood insurance is required and whether optional coverage is appropriate.
4.Compare the complete monthly payment. Include PITI, mortgage insurance, HOA dues, and any additional recurring housing expenses.
5.Maintain a financial cushion. Plan for possible increases in insurance, taxes, repairs, and maintenance.
For buyers comparing new construction in Katy or Fulshear, I also recommend reviewing whether the property falls within a MUD or other special taxing district.
A lower purchase price or attractive builder incentive does not always produce the lowest long-term housing cost.
8. How Medallion Funds Helps Texas Homebuyers
At Medallion Funds, my goal is to help borrowers understand their financing options and make informed homeownership decisions.
Depending on borrower qualifications and lender availability, we can explore conventional mortgages, FHA loans, VA loans, jumbo financing, doctor and dentist mortgage programs, and alternative documentation options.
Different loan programs may offer different down payment requirements, mortgage insurance structures, and underwriting considerations.
But regardless of the loan program, the complete housing payment matters.
I work with buyers to evaluate financing scenarios, review estimated payments, and understand the tradeoffs before they commit.
Final Thoughts: Buy the Payment, Not Just the House
Texas can offer tremendous homeownership opportunities, but buyers need to understand the true cost of owning a property.
Your purchase price matters.
Your mortgage interest rate matters.
But your property taxes, homeowners insurance, and other recurring expenses matter just as much.
The best homebuying decision isn't necessarily the most expensive house a lender will approve. It's the home that fits your financial goals and monthly budget.
Ready to evaluate your homebuying options?
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok