Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
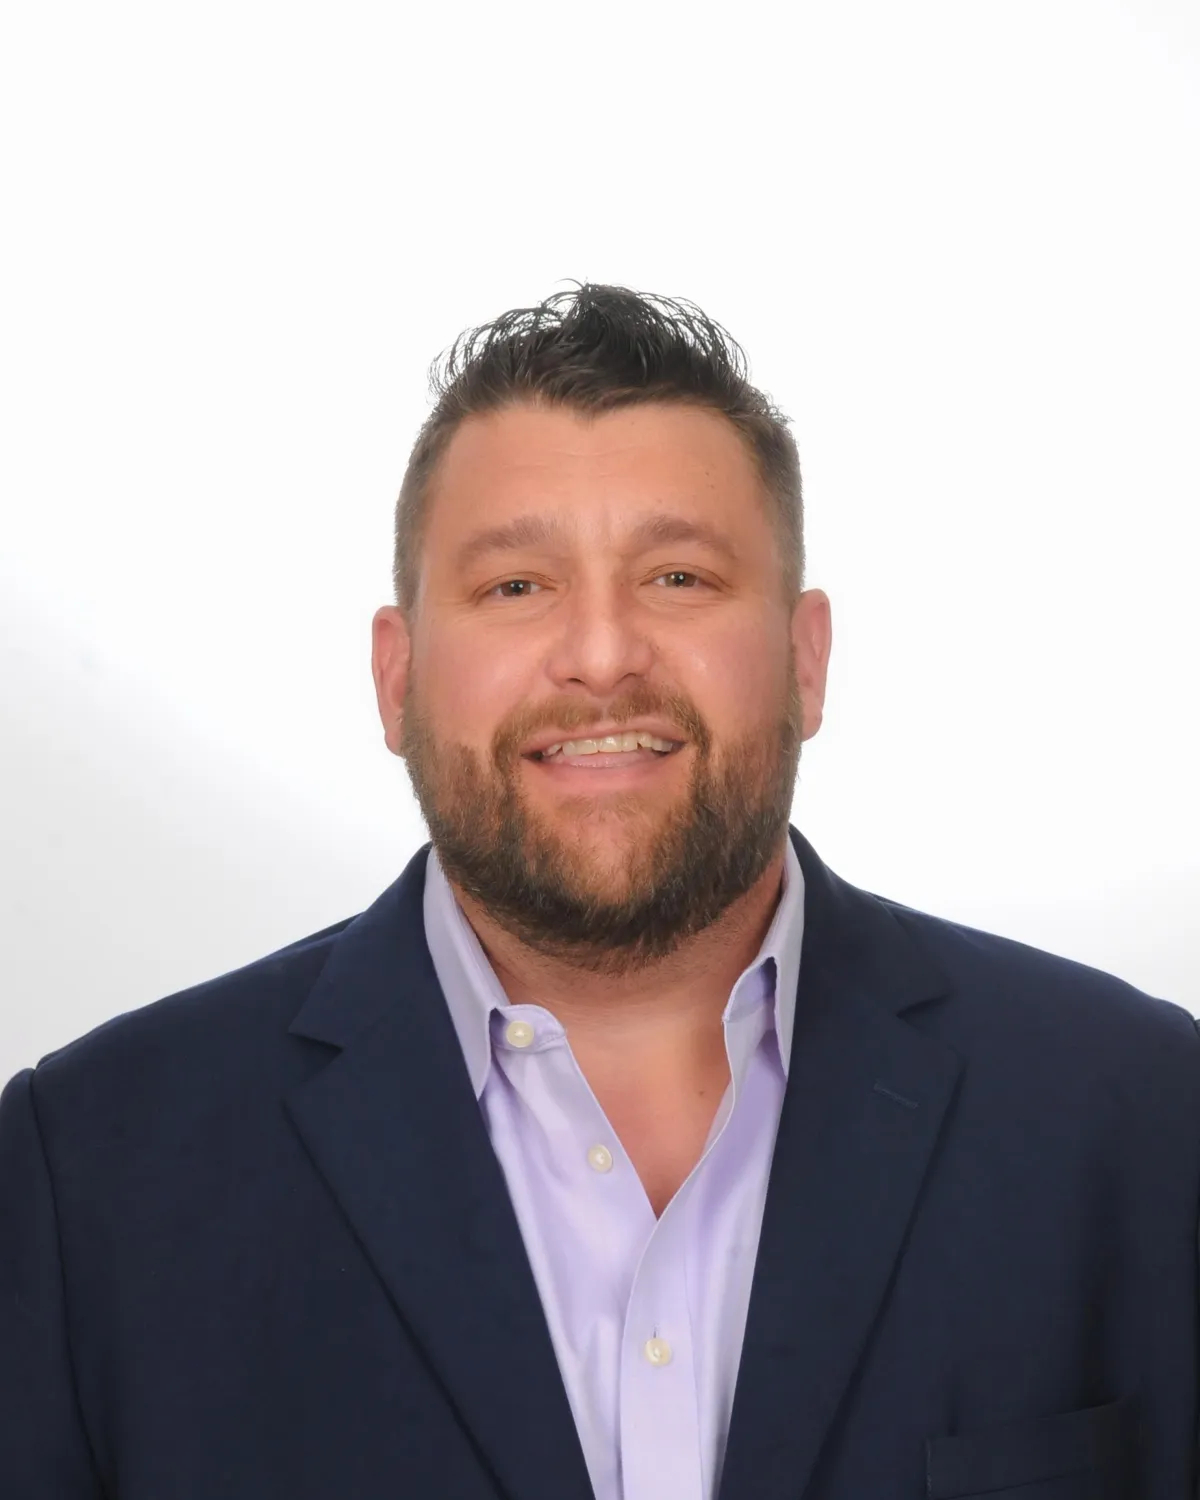
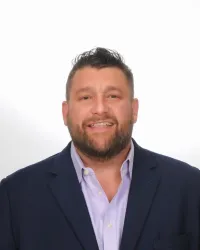
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
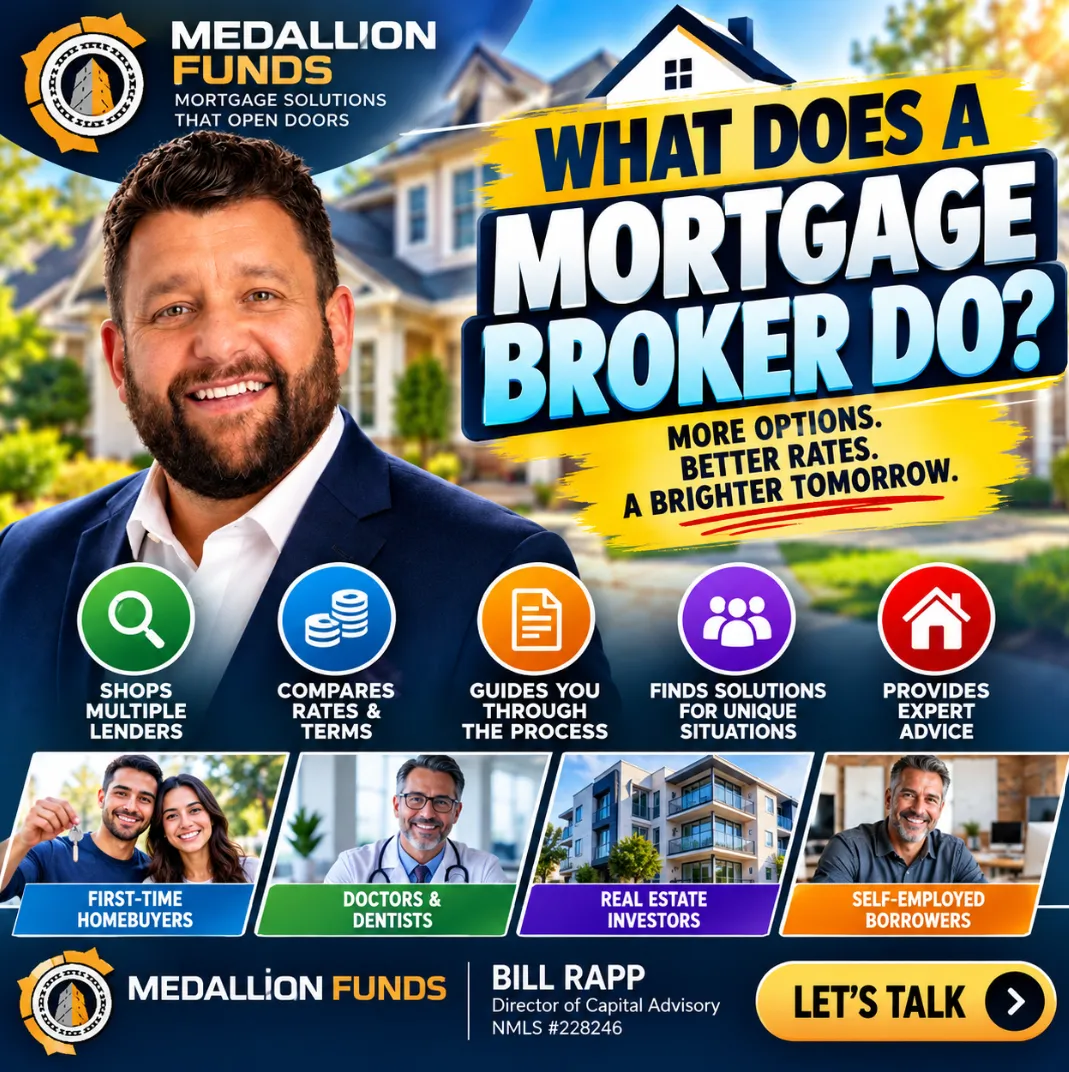
🏡 What Does a Mortgage Broker Do? How a Broker Helps You Find the Right Home Loan 🔑
🏡 What Does a Mortgage Broker Do? How a Broker Helps You Find the Right Home Loan 🔑
💰 Mortgage Broker vs. Bank: Why More Loan Options Could Mean a Better Mortgage 🏠
________________________________________________________________________________
What Does a Mortgage Broker Do?
Buying a home or refinancing a mortgage can feel complicated. There are interest rates to compare, loan programs to understand, qualification requirements to meet, documents to collect, and dozens of decisions between your first conversation and closing day.
That is where a mortgage broker can help.
Instead of working for one bank and offering only that institution's mortgage products, a mortgage broker works with borrowers to evaluate financing needs and identify loan options from available wholesale lenders and lending programs.
At Medallion Funds, our goal is straightforward: help borrowers understand their options, compare financing structures, and navigate the mortgage process from initial consultation through closing.
What Is a Mortgage Broker?
A mortgage broker serves as an intermediary between a borrower and potential mortgage lenders.
When you apply directly with a bank, you generally have access to the mortgage products and underwriting guidelines offered by that institution.
A mortgage broker takes a different approach.
Rather than starting with one lender's product menu, the broker begins with the borrower's financial situation and objectives. The broker can then evaluate available lenders and loan programs to determine which options may fit those needs.
That distinction can be particularly valuable when a borrower does not fit neatly into a traditional lending box.
What Does a Mortgage Broker Actually Do?
A good mortgage broker does much more than quote an interest rate.
The process typically begins with understanding the borrower.
That includes factors such as income, employment, credit, assets, existing debts, down payment, property type, intended occupancy and long-term financial objectives.
From there, the broker can help identify appropriate mortgage programs and compare available financing structures.
Depending on the transaction, that might include:
·Conventional mortgages
·FHA loans
·VA loans
·USDA loans
·Jumbo mortgages
·Doctor and dentist mortgage programs
·Bank statement loans
·DSCR investor loans
·Non-QM mortgages
·Asset-based or asset-utilization programs
·Investment property financing
·Other specialized mortgage programs
The objective is not simply to find a mortgage. It is to help determine which available financing structure makes sense for the borrower and transaction.
Mortgage Broker vs. Bank: What's the Difference?
One of the easiest ways to understand a mortgage broker is to compare the brokerage model with going directly to a bank.
A bank primarily offers its own mortgage products.
If you meet the bank's underwriting guidelines, that may work perfectly well. But if your situation falls outside those guidelines, your options at that institution may become limited.
A mortgage broker can potentially access programs from multiple lending sources.
That means the conversation can shift from:
"Do you qualify for our mortgage?"
to:
"Which available mortgage program may fit your situation?"
That can make a meaningful difference for borrowers with unique income, assets or financing requirements.
How Does a Mortgage Broker Help Compare Loans?
Mortgage shopping should involve more than asking, "What is today's rate?"
Interest rate matters, but so do:
Loan terms. Is the mortgage fixed or adjustable?
Closing costs. What lender fees, discount points and third-party costs apply?
Mortgage insurance. Will the loan require PMI or another form of mortgage insurance?
Down payment. How much cash is actually required?
Reserves. How much money must remain available after closing?
Qualification requirements. How will the lender calculate income, debts and other obligations?
Prepayment considerations. Are there restrictions or costs associated with paying the loan off early where applicable?
A lower advertised rate does not automatically make one mortgage the best financial option.
The entire financing structure should be evaluated.
Mortgage Brokers Can Help Borrowers With Unique Situations
Mortgage brokers can be particularly valuable when borrowers have financial circumstances that do not fit traditional underwriting models.
Consider a self-employed business owner.
Their tax returns may show less taxable income because of legitimate business deductions. A traditional mortgage may therefore be difficult even when the borrower has strong cash flow.
Depending on the circumstances, a bank statement mortgage or another Non-QM program may provide an alternative method of documenting income.
Doctors and dentists may face a different challenge. They can have substantial earning potential but also significant student loan balances or limited accumulated assets early in their careers.
Specialized doctor and dentist mortgage programs may address those circumstances differently than traditional mortgage products.
Real estate investors represent another example.
A DSCR loan may focus heavily on the property's rental income and debt-service coverage rather than qualifying primarily from the borrower's personal employment income.
The appropriate solution depends on the individual borrower, property and loan program.
What Does the Mortgage Broker Do During the Loan Process?
Once an appropriate financing strategy has been identified, the broker can help coordinate the transaction through the lending process.
That may include helping the borrower understand documentation requirements, assembling the mortgage application, submitting the loan package, communicating with the lender, addressing underwriting conditions and coordinating with other parties involved in the closing.
A mortgage transaction can involve borrowers, lenders, processors, underwriters, appraisers, insurance agents, title companies, real estate agents and other professionals.
Part of the broker's role is helping keep that process moving toward closing.
Does Using a Mortgage Broker Guarantee the Lowest Rate?
No.
No mortgage professional should promise that a broker will always produce the lowest rate or lowest cost.
Mortgage pricing changes constantly and depends on numerous factors, including credit profile, loan-to-value ratio, occupancy, property type, loan size, program, lock period and market conditions.
The potential advantage of a broker is access and comparison.
Instead of assuming one institution automatically has the right mortgage, borrowers can evaluate available options and financing structures.
When Should You Talk to a Mortgage Broker?
Ideally, before you start seriously shopping for a home.
Early conversations can help you determine:
How much you may qualify to borrow, what your estimated payment could be, how much cash you may need for closing, which loan programs might fit and whether there are credit or documentation issues that should be addressed before making an offer.
For homebuyers, preparation can make the mortgage process significantly smoother.
For homeowners considering a refinance, a broker can also help evaluate whether refinancing makes financial sense before starting a new loan application.
Why Work With Medallion Funds?
At Medallion Funds, we believe mortgage advice should begin with the borrower—not a predetermined loan product.
We work to understand your goals first and then evaluate financing options that may fit those objectives.
Whether you are a first-time homebuyer, move-up buyer, doctor, dentist, veteran, investor, self-employed borrower or homeowner exploring a refinance, the objective remains the same:
Understand the transaction. Compare the options. Choose the financing structure that fits your goals.
Ready to Explore Your Mortgage Options?
Before assuming your bank is your only option—or that you will not qualify because your financial situation is unconventional—consider speaking with a mortgage broker.
The right mortgage strategy starts with understanding the available options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok