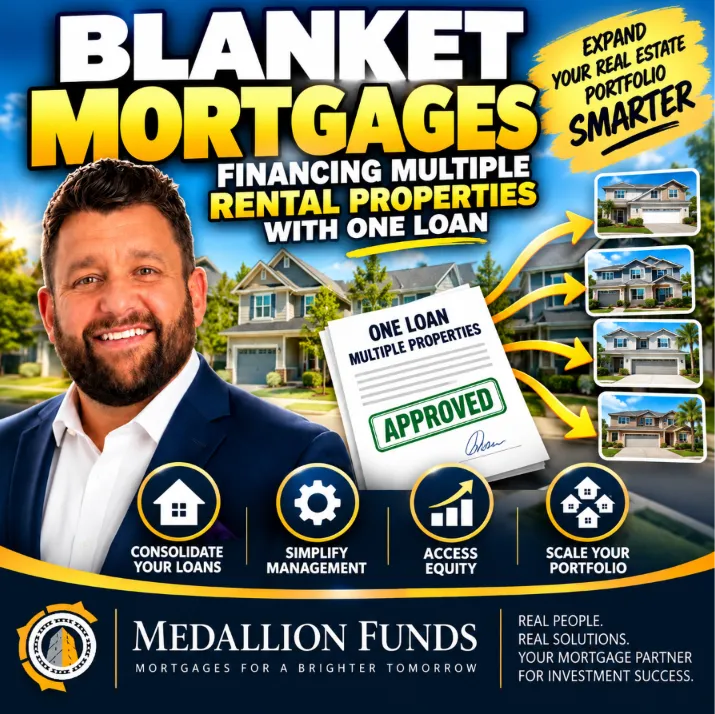
🏘️ Blanket Mortgages Explained: How to Finance Multiple Rental Properties With One Loan 💰
🏘️ Blanket Mortgages Explained: How to Finance Multiple Rental Properties With One Loan 💰
🚀 One Loan, Multiple Rental Properties: How Blanket Mortgages Help Real Estate Investors Scale 🏡
___________________________________________________________
🏘️ Blanket Mortgages: How to Finance Multiple Rental Properties With One Loan
Managing multiple rental properties can be an excellent way to build long-term wealth. However, as your investment portfolio grows, managing separate mortgages, payment schedules, loan maturities, and refinancing requirements can become increasingly complicated.
What if you could finance several investment properties under one mortgage?
That's exactly what a blanket mortgage may allow you to do.
For experienced real estate investors, blanket mortgage loans can offer a way to consolidate financing, simplify portfolio management, and potentially access capital for additional acquisitions.
But these loans aren't right for every investor.
At Medallion Funds, we help investors evaluate financing strategies based on their rental property portfolios, cash flow, equity positions, and long-term investment objectives.
Here's what you need to know.
What Is a Blanket Mortgage?
A blanket mortgage is a single loan secured by two or more real estate properties.
Instead of obtaining individual mortgages for each investment property, a borrower may finance several properties through one loan agreement.
For example, imagine an investor owns five single-family rental homes.
Rather than managing five separate mortgages, the investor might refinance those properties into one blanket mortgage secured by all five homes.
The properties remain separate real estate assets, but they collectively secure the financing.
Important distinction: A blanket mortgage is not simply five loans combined into one payment. It is a financing structure in which multiple properties serve as collateral for one debt obligation.
Example: Financing Five Rental Properties
Combined property value
$1,500,000
Illustrative LTV
70%
Potential loan amount
$1,050,000
Portfolio equity
$450,000
Illustrative financing structure only. Actual proceeds depend on underwriting, existing liens, property eligibility, cash flow, and lender requirements.
How Do Blanket Mortgage Loans Work?
A blanket mortgage lender evaluates the portfolio as a whole, while also reviewing the individual properties.
Underwriting may include:
Combined property values and loan-to-value ratio (LTV)
Rental income and operating expenses
Debt service coverage ratio (DSCR)
Property locations, conditions, and occupancy
Borrower liquidity, credit, and real estate experience
Ownership structure and existing mortgages
The requested loan term and repayment strategy
Some programs emphasize portfolio cash flow, while others also rely heavily on borrower financial strength.
Lenders may offer blanket mortgages for stabilized rental portfolios, acquisition financing, refinancing, or portfolio restructuring.
Five Potential Benefits of Blanket Mortgages
1. Simplified Mortgage Management
One blanket mortgage can replace several individual loans.
That may mean fewer payment schedules, loan statements, and maturity dates to monitor.
For investors managing multiple properties, streamlined financing can reduce administrative complexity.
2. Potential Financing Flexibility
A portfolio with significant equity and strong rental income may provide opportunities to restructure existing debt.
Depending on lender guidelines, investors may be able to refinance multiple properties together or access available equity.
However, combining properties does not automatically increase borrowing capacity.
3. Portfolio Expansion Opportunities
Some blanket loan structures can accommodate additional properties, subject to lender approval and loan terms.
This may benefit investors purchasing several rental properties at once or building a larger portfolio over time.
4. Potential Transaction Efficiencies
Financing several properties together may reduce some duplicated administrative or loan-processing expenses.
However, appraisal fees, title work, legal expenses, recording charges, and other costs may still apply to individual properties.
Investors should compare total financing costs rather than assume one loan will always be cheaper.
5. Flexible Property Release Provisions
One particularly valuable feature of certain blanket mortgage programs is a partial release clause.
This provision may allow the borrower to sell one property and release it from the blanket mortgage without paying off the entire loan.
The lender typically requires a specified principal reduction, sometimes called a release price, and may impose other conditions.
Not all blanket loans include partial release provisions.
Understanding the Partial Release Clause
Suppose an investor has five rental homes securing a $1 million blanket mortgage.
The investor decides to sell one property for $325,000.
If the loan includes a negotiated partial release provision, the lender may allow the property to be released after receiving an agreed principal payment.
For illustration, the lender might require a $250,000 principal reduction, leaving a $750,000 outstanding balance before other adjustments.
The investor could potentially retain the remaining sale proceeds after closing costs and other obligations.
Without an appropriate release provision, selling one property may require lender negotiations or a larger loan paydown.
Investor takeaway: Always understand the property release requirements before signing a blanket mortgage agreement.
Blanket Mortgage vs. Individual Rental Property Loans
Feature | Blanket Mortgage | Individual Mortgages |
|---|---|---|
Collateral | Multiple properties | Typically one property per loan |
Loan payments | Usually one | Multiple |
Underwriting | Portfolio and property-level | Individual property and borrower |
Selling one property | May require partial release | Generally pay off that property's loan |
Financing flexibility | Depends on portfolio loan terms | Each loan can be managed independently |
Cross-collateral risk | Generally higher | Generally isolated by loan |
The right structure depends on how frequently the investor plans to acquire, refinance, or sell properties.
Blanket Mortgage vs. DSCR Loans
Real estate investors often ask whether they should use a blanket mortgage or individual DSCR loans.
A DSCR loan generally emphasizes the rental property's ability to generate sufficient income to support debt payments.
A blanket mortgage describes the collateral structure, not necessarily the underwriting method.
In fact, some blanket mortgage programs use DSCR-based underwriting.
An investor with three rental homes might benefit from individual DSCR loans if the properties will be sold separately.
Another investor holding 15 stabilized rentals for the long term may prefer portfolio financing.
Neither approach is universally better.
How Much Down Payment or Equity Is Required?
Down payment and equity requirements vary by lender, property type, portfolio characteristics, and borrower qualifications.
For illustration, a lender offering 70% LTV on a $2 million eligible portfolio could potentially provide $1.4 million in financing.
That leaves $600,000 in equity.
However, LTV is only one component of underwriting. Rental cash flow, DSCR, borrower liquidity, and other constraints may reduce the available loan amount.
Investors should also account for closing costs and required reserves.
Who Should Consider a Blanket Mortgage?
Blanket mortgages may be particularly useful for:
Investors owning multiple single-family rental properties
Landlords managing several duplexes, triplexes, or fourplexes
Investors acquiring rental property portfolios
LLCs holding multiple investment properties
Buy-and-hold investors seeking consolidated financing
Experienced investors refinancing several properties simultaneously
They may be less appropriate for investors who frequently sell individual properties, prefer separate financing for each asset, or cannot obtain acceptable release terms.
What Are the Risks of Blanket Mortgages?
Although blanket mortgages offer potential advantages, investors should carefully consider the trade-offs.
Cross-collateralization: Multiple properties secure the same debt. A default may expose more than one property to lender remedies.
Refinancing risk: If a loan has a balloon maturity, the investor may need to refinance or repay the remaining balance when it comes due.
Partial release restrictions: Selling one property may require lender approval and a substantial principal paydown.
Portfolio concentration: Weak performance at several properties can affect the financing of the entire portfolio.
Loan terms: Some portfolio products may have prepayment penalties, minimum loan sizes, recourse provisions, or higher financing costs.
Investors should evaluate the complete loan agreement, not just the interest rate.
How to Qualify for a Blanket Mortgage
While requirements vary, lenders commonly request:
A current property schedule identifying each asset, address, value, and outstanding debt.
Rent rolls and current lease information.
Property-level income and expense statements.
Mortgage statements and insurance information.
Entity documents, if the properties are held in an LLC.
Borrower financial information, liquidity documentation, and investment experience.
A clear explanation of the requested financing and exit strategy.
A complete portfolio package helps lenders assess collateral quality, cash flow, and overall risk.
Frequently Asked Questions
Can I combine several rental properties into one mortgage?
Potentially, yes. Eligible properties may be refinanced under a blanket mortgage, subject to lender requirements, lien payoffs, ownership considerations, and underwriting approval.
Can I get a blanket mortgage with an LLC?
Yes, many portfolio lending programs permit eligible LLC borrowers. Lenders may still require personal guarantees or additional documentation.
How many properties do I need for a blanket mortgage?
Generally, at least two properties. Some lenders require more properties or a minimum combined loan amount.
Can I sell one property without refinancing the entire loan?
Possibly. This depends on the partial release provisions and the lender's approval requirements.
Are blanket mortgages available for properties in different states?
Some lenders permit geographically diversified portfolios, while others limit eligible states or markets.
Are blanket mortgage interest rates higher?
Not necessarily. Pricing depends on the lender, collateral, leverage, DSCR, loan term, borrower strength, and market conditions.
Can I use a blanket mortgage to purchase multiple rental properties?
Yes, some programs allow investors to acquire multiple properties through one financing arrangement, subject to program guidelines.
Final Thoughts: Is a Blanket Mortgage Right for Your Rental Portfolio?
A blanket mortgage can be a valuable financing tool for real estate investors who own multiple properties and want a more coordinated approach to managing their debt.
But convenience alone should never determine the financing decision.
The most important considerations include borrowing costs, cash flow, equity, property release flexibility, cross-collateralization, and long-term investment strategy.
At Medallion Funds, we help investors compare financing structures so they can evaluate what works best for their portfolios.
Ready to explore financing for multiple rental properties?
Contact Bill Rapp, CCIM, Director of Capital Advisory at Medallion Funds, to discuss your investment portfolio and available financing strategies.
Bill Rapp, CCIM
Director of Capital Advisory | Medallion Funds
NMLS #228246
Residential mortgage availability depends on applicable state licensing; commercial and investor programs depend on lender eligibility and property location.
MedallionFunds.com | Schedule a Consultation
Educational information only. This is not a commitment to lend or an offer of specific financing terms. All loans are subject to underwriting, program availability, and approval.