🏡 Mortgage Broker vs. Retail Loan Officer: Which Is Better? 💰
🏡 Mortgage Broker vs. Retail Loan Officer: Which Is Better? 💰
🚀 Mortgage Broker vs. Retail LO: Career & Income Comparison 💼
______________________________________________________________________________
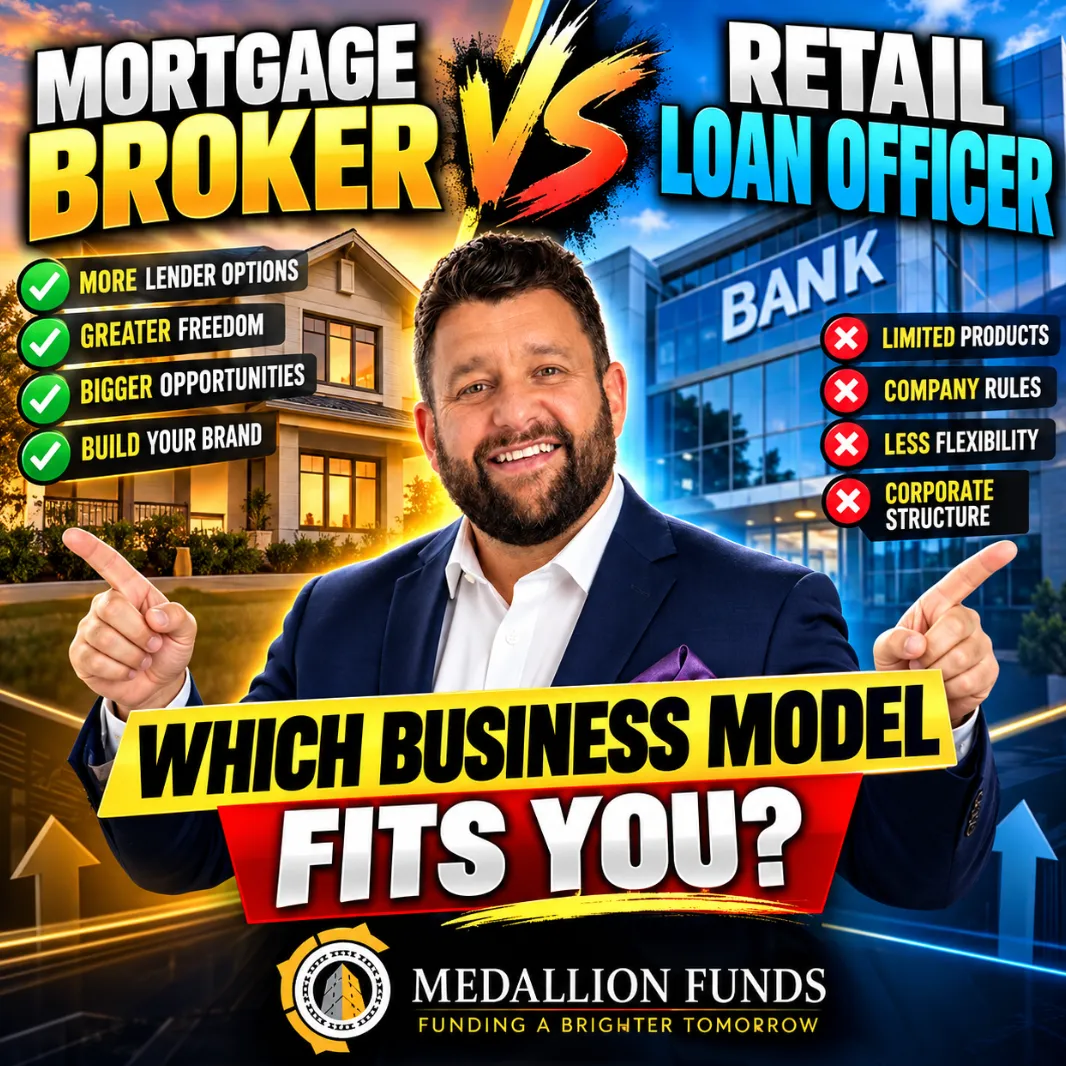
Mortgage Broker vs. Retail Loan Officer: Which Business Model Fits You?
If you're a mortgage loan officer considering a career move, one of the most important decisions you'll make is whether to work in the retail lending channel or the mortgage broker channel.
Both models can provide rewarding careers. However, they differ in lender access, compensation structures, operational support, pricing flexibility, technology, and long-term business development opportunities.
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds. Let's examine how these business models compare and how to choose the right environment for your production goals.
What Is a Retail Mortgage Loan Officer?
A retail mortgage loan officer typically originates loans directly for a bank, credit union, or mortgage lending company. The lender generally controls the products, pricing, underwriting policies, and operational infrastructure.
Retail lenders may offer recognizable brands, marketing resources, employee benefits, company-generated leads, and integrated processing or underwriting.
However, the loan officer usually works within the company's lending platform. If a borrower does not fit the institution's credit box, the officer may have limited alternatives.
What Is a Mortgage Broker?
A mortgage broker helps borrowers obtain financing through third-party wholesale lenders rather than relying on one lender's product menu.
Depending on the brokerage's approved relationships, a broker may access conventional, FHA, VA, USDA, jumbo, renovation, non-QM, bank statement, DSCR, and other mortgage programs.
Brokerage operations vary. Some firms provide extensive processing, technology, compliance, and lead-generation support, while others expect originators to manage more of their own business.
Mortgage Broker vs. Retail Loan Officer: Side-by-Side Comparison
Feature | Retail Loan Officer | Mortgage Broker Channel |
Lender access | Employer's lending platform | Multiple approved wholesale lenders |
Loan products | Employer's programs | Varies across lender partners |
Compensation | Salary, commission or combination | Often commission-based |
Lead generation | May provide company leads | Self-generated, referral or company leads |
Operations | Usually centralized | Depends on brokerage support |
Branding | Employer-led | Varies by brokerage |
Underwriting | Employer or its lending partners | Wholesale lender |
Best suited for | Structured, integrated environments | Originators seeking lender choice and business-building opportunities |
Five Key Differences That Matter
1. Lender Access and Product Options
Retail loan officers generally work within their employer's lending programs. Mortgage brokers can compare options from multiple approved wholesale lenders.
This flexibility may be particularly valuable for self-employed borrowers, real estate investors, physicians, and buyers with nontraditional income.
More lender options do not automatically mean approval or the lowest rate. Each lender applies its own guidelines, fees, pricing, and eligibility requirements.
2. Compensation and Earning Potential
Retail lenders may offer salaries, commissions, benefits, bonuses, and company-provided leads. Mortgage brokerages may offer commission-based structures with different payouts for self-generated, referral, and company-provided opportunities.
Higher advertised commission percentages do not automatically produce higher take-home earnings.
Loan officers should compare actual funded-loan volume, compensation per closed loan, employer-paid expenses, benefits, support costs, lead quality, and compensation compliance.
Mortgage loan originator compensation must follow applicable federal and state requirements, including restrictions on compensation based on loan terms.
3. Lead Generation and Business Development
Retail operations may provide centralized marketing and lead flow. Brokerage models can provide opportunities to build a personal brand and referral network, although actual independence depends on company policies and agreements.
Self-generating originators often focus on real estate agents, builders, financial professionals, past clients, and online educational content.
The strongest business model is the one that supports your preferred method of generating sustainable production.
4. Processing, Technology, and Operations
A retail lender may provide a unified system for loan origination, processing, underwriting, and closing.
A mortgage brokerage may coordinate with multiple wholesale lenders, making lender selection and workflow management especially important.
Before joining a brokerage, ask about processing, disclosures, CRM systems, loan origination technology, pricing tools, compliance oversight, training, and escalation procedures.
5. Career Control and Long-Term Growth
Retail lending may appeal to loan officers who prefer established systems, a recognizable employer brand, employee benefits, and structured lead flow.
Mortgage brokerage may appeal to experienced originators who want broader lender access, more product choices, and a greater emphasis on independently developed referral relationships.
Neither channel guarantees better earnings, faster closings, or greater flexibility.
Real-World Example: A Self-Employed Borrower
Imagine a self-employed business owner who wants to purchase a home but has substantial legitimate tax deductions that reduce the income shown on their tax returns.
A retail lender might have an appropriate program. If it does not, the originator's alternatives may be limited.
A mortgage broker could evaluate the borrower's eligibility with several approved wholesale lenders, potentially including a qualifying bank statement loan.
The broker would still need to evaluate income documentation, assets, credit, down payment, pricing, and program eligibility. A non-QM product may carry different costs or requirements than a conventional mortgage.
The advantage is not a guaranteed approval. It is the opportunity to compare appropriate financing structures.
How to Choose the Right Mortgage Business Model
Before switching channels, ask:
·How many loans do I realistically expect to close each month?
·What percentage of my business is self-generated?
·What compensation will I actually retain after expenses?
·Which loan programs do my clients need most often?
·How reliable is the company's processing and closing support?
·Who owns or controls my client relationships and marketing assets?
·What training, technology, and compliance support will I receive?
A written side-by-side comparison of compensation, support, lender access, and business-building opportunities is more valuable than relying on an advertised split alone.
Why Consider Medallion Funds?
At Medallion Funds, our goal is to help mortgage professionals develop productive, sustainable lending businesses through broad lender relationships, technology, support, and business-development opportunities.
We welcome conversations with experienced loan officers, particularly self-generating originators who value borrower education, referral relationships, and financing flexibility.
Program access, compensation, eligibility, and operational arrangements should be confirmed during the recruiting process.
Final Thoughts: Which Model Fits You?
The mortgage broker versus retail loan officer decision is not simply about who pays the highest commission.
It's about choosing the platform that aligns with your clients, production strategy, preferred working environment, and long-term career goals.
If you're exploring a move into the mortgage broker channel, I'd welcome the opportunity to discuss your goals and how Medallion Funds may fit.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory